LNG, Natural Gas
October 05, 2026
Europe remains top destination for US LNG in September amid winter storage rebuild

By Corey Paul
Editor:
HIGHLIGHTS
Europe receives 53% of September cargoes
Netherlands, Egypt top September destinations
EU storage trails prior years
More than half of US LNG cargoes delivered in September landed in Europe, keeping the region the primary destination for American supply as buyers worked to rebuild gas inventories ahead of winter, an analysis of S&P Global Energy CERA data showed Oct. 5.
Europe plus Turkey received 76 of the 143 US LNG cargoes delivered during the month, representing about 53% of the total. The Netherlands was the top destination for US LNG in September with 15 cargoes, followed by Egypt, Italy and Spain with 14 cargoes each and France with 12.
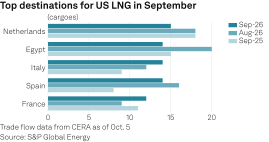
The September flows extended a shift toward Europe that emerged in late August, as recovering US liquefaction utilization made additional supplies available for the region's winter inventory refill effort.
Europe's LNG imports have lagged for much of the year following the start of the war in the Middle East in late February, which led to a runup in spot prices and increased competition with Asian buyers facing the most acute supply disruptions from the conflict now into its eighth month.
EU-wide gas storage was 72% full as of Oct. 3, compared with nearly 83% at the same point in 2025 and about 94% in 2024, according to Gas Infrastructure Europe data.
In terms of volumes, US LNG delivered to Europe plus Turkey in September remained steady at about 5.4 million mt, even as total US deliveries declined substantially month over month.
Some 41 US LNG cargoes in September landed in Asia-Pacific markets, or about 29% of the total, down from a 36% share in August. Delivered volume to the region fell to about 2.7 million mt from 4.2 million mt.
Loadings in September suggested Europe's strong pull on US supplies would continue into October. Europe plus Turkey accounted for 85 of the 156 cargoes loaded during the month, or about 54%.
Headed into October, an annual maintenance turnaround at the single-train Cove Point LNG terminal in Maryland was weighing on overall US LNG output. The turnaround work was expected to be completed in the second half of the month.
Market participants were also watching a supply disruption at the Freeport LNG plant in Texas, which reported taking one of three trains offline Oct. 2 for maintenance.
Freeport on Oct. 5 declined to comment on the status of the facility. Feedgas deliveries were scheduled to rebound to about 2.1 Bcf/d, up from about 1.6 Bcf/d on Oct. 4, CERA data showed, based on nominations for the morning cycle that could later be revised.
Otherwise, the nine major US LNG export facilities were scheduled to receive about 19 billion cubic feet/day of feedgas on Oct. 5, after averaging closer to 19.5 Bcf/d in September.
Global LNG spot prices remain elevated and volatile.
Platts, part of S&P Global Energy, assessed the DES Northwest Europe marker for November at $23.56/million British thermal units, a decline of 73 cents from the prior assessment.
In the Pacific, Platts assessed the JKM benchmark price reflecting LNG delivered to Northeast Asia at $25.569/million British thermal units, an increase of 80 cents from the prior assessment.
Both prices remain more than double year-ago levels, despite easing from September highs.
