Metals & Mining, Non-Ferrous
October 29, 2026
China lithium market braces for 2027 surplus as demand growth slows
Editor:
HIGHLIGHTS
Energy storage battery growth slows to 10%-20%
Lithium carbonate prices fall 19% in October
Global supply to rise 26.8% by 2027: CERA
China's lithium carbonate market has come under renewed pressure as market participants price in slower energy storage demand growth and rising raw material supply in 2027, with many expecting fundamentals to shift from a tight balance or deficit in 2026 toward a surplus next year.
Most market participants expect China's energy storage battery demand to continue expanding in 2027 but see growth slowing sharply to around 10%-20%, compared with this year's rapid pace. Some more bearish participants put growth at below 10%, according to sources at a recent industry event held in China.
The expected slowdown has weighed on lithium sentiment, with energy storage emerging as a major source of incremental lithium demand this year, even as growth in China's electric vehicle sector has moderated.
China's energy storage battery shipments reached 790 gigawatt-hours over January-September, up 84% year over year, according to China-based research agency Gaogong Industry Institute, or GGII.
Strong overseas utility-scale storage orders and concentrated domestic inventory building have kept production schedules elevated into the fourth quarter, according to GGII.
Against that high base, even continued double-digit growth in 2027 would represent a significant slowdown in incremental battery demand, just as the lithium market prepares for higher mine and lithium chemical supply.
However, views differed on the extent of the expected loosening.
"Under a bullish scenario, the market could be oversupplied next year, while our base case points to a tight balance," a Chinese end-user said. "We see limited upside for lithium carbonate."
Several China-based analysts expect the lithium market to swing into surplus in 2027 from a tight balance or deficit this year, while some lithium producers said sentiment toward next year's fundamentals remained bearish.
Futures lead market lower
The shift in expectations has driven sharp volatility in both China's futures and physical lithium carbonate markets, although spot prices have shown relatively stronger resistance.
The most active lithium carbonate futures contract on the Guangzhou Futures Exchange has remained below 100,000 yuan/metric ton ($15,011/mt) since Oct. 21, adding pressure to physical prices.
The spot market also came under downward pressure after domestic industry data showed a month-over-month decline in cathode production schedules for November, while market talk of a possible restart of the Jianxiawo lithium mine before year-end further weighed on sentiment.
Platts, part of S&P Global Energy, assessed battery-grade lithium carbonate at 98,000 yuan/mt DDP China on Oct. 28, flat week over week but 19% lower from a month earlier.
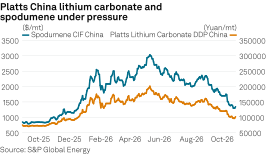
Domestic lithium producers were reluctant to sell large volumes at lower prices, while traders showed limited interest in building inventories in a falling market.
Supply growth reinforces bearish outlook
The shift in demand expectations comes as global lithium supply is forecast to accelerate.
Adjusted global lithium raw material supply is expected to rise 26.8% year over year to around 2.5 million mt of lithium carbonate equivalent in 2027, with supply growth outpacing lithium chemical consumption, according to a September report by S&P Global Energy CERA.
In China, one of the largest near-term supply uncertainties is the Jianxiawo lithium mine in Jiangxi province.
The mine moved closer to a potential restart after its mining project's environmental impact assessment entered the final pre-approval public notice stage Oct. 22, with the notice period scheduled to end Oct. 28.
Overseas raw material availability has meanwhile continued to rise.
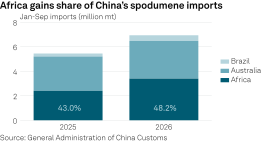
China's spodumene imports rose 25.9% year over year over January-September, with African countries accounting for 48.2% of total imports, according to China customs data.
The rising share of African supply, together with expectations of domestic mine restarts, has reinforced market expectations of ample feedstock availability in 2027.
However, increasingly bearish supply projections are themselves becoming sensitive to lithium prices.
Some China-based market participants questioned whether mine restarts and new projects would proceed as quickly as expected if lithium carbonate prices continued to fall toward marginal production costs.
The potential supply response could be particularly important for higher-cost Chinese lepidolite production and some emerging overseas projects.
