ECONOMICS COMMENTARY — 26 Oct, 2026
US sees growth surge outpace rivals, but also reports higher inflationary pressures
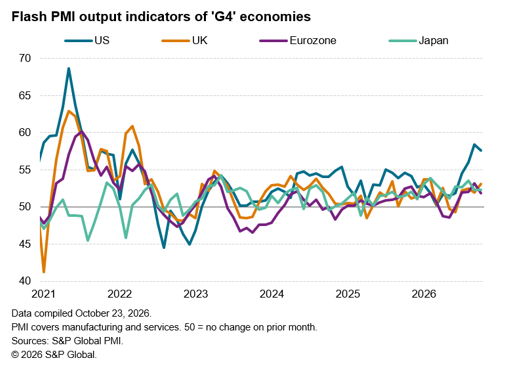
S&P Global’s October flash PMI surveys signalled continued growth across the four largest advanced economies, led by a substantial US outperformance. Although the G4 expansion eased, it remained the second-strongest since April 2022, with the UK, eurozone and Japan also showing resilience despite geopolitical uncertainty and higher energy prices.
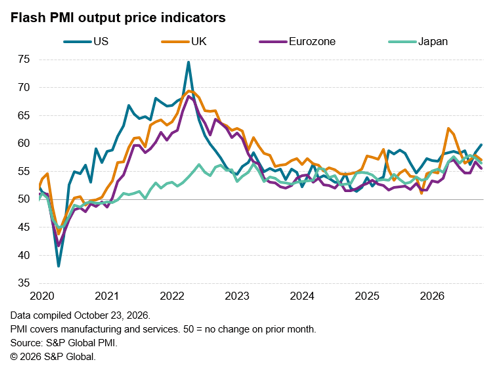
Price pressures nevertheless remained elevated across all four economies, with US selling price inflation notably reaching its highest since August 2022. Strong US hiring also contrasted with broadly stalled employment elsewhere, heightening the risk of second-round US inflation effects. Resilient growth and persistent inflation therefore send a hawkish signal to policymakers, particularly in the US.
US sustains its outperformance
Business activity rose across all four largest advanced economies – the US, eurozone, Japan and the UK (the ‘G4’) – in October, according to flash PMI data, but once again the US led by a wide margin.
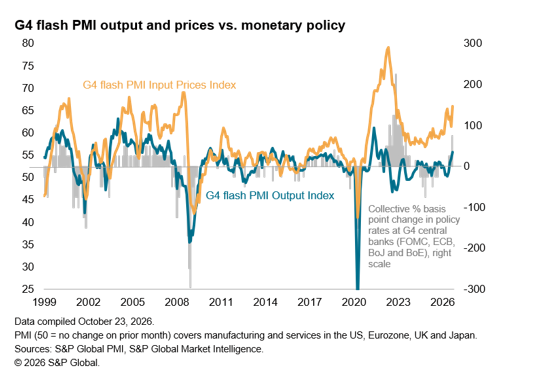
Although the GDP-weighted output index for the G4 economies fell from 55.7 in September to 55.0 in October, the latest expansion was the second-strongest recorded since April 2022.
Despite the US’s expansion cooling slightly, October saw the second-sharpest rise in output since March 2022, with the US outperforming all other G4 economies in terms of both manufacturing and service sector growth, in both cases by substantial margins as growth rates remained among the highest seen over the past five years.
The US survey data point to annualized GDP growth of 5.0%, with a 4.0% pace having been indicated for the third quarter as a whole.
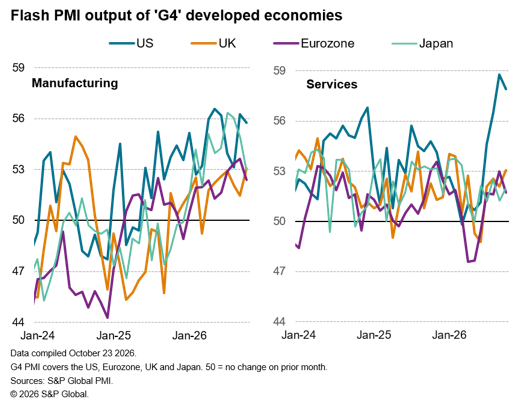
While the other G4 economies lagged the US in terms of growth, their performances were nevertheless encouraging, showing resilience in the face of the ongoing geopolitical uncertainty and energy price rises.
Growth in the United Kingdom accelerated to the fastest since the outbreak of the war in the Middle East in late February, consistent with the economy growing at a quarterly rate of 0.7%. While eurozone growth slowed, it remained one of the strongest performances seen for the single currency area over the past four years, indicative of 0.3% quarterly GDP growth.
In Japan, the composite PMI output index held its ground on September’s reading, albeit running below levels seen earlier in the year. The latest Japan PMI is nevertheless still consistent with 0.5% quarterly GDP growth.
US also reports steepest price rise
However, all four major advanced economies continued to report elevated price growth, most notably in the US. Although rates of selling price inflation moderated in the eurozone, UK and Japan, in all cases the survey indices point to inflation running well ahead of central bank targets. In the US, selling price inflation meanwhile accelerated to the highest since August 2022.
Employment trends to warn of second-round inflation effects
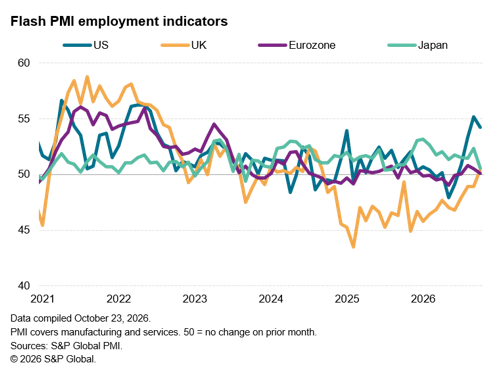
A key concern among policymakers is the degree to which elevated price pressures become ingrained and feed through to more worrying increases in underlying inflation, specifically energy prices. With a key transmission mechanism of second-round inflation effects being wage growth, the employment indices from the PMI are therefore also important to consider in the inflation outlook.
In this respect, the US stands out again, with recent months having seen strong job gains in the US, contrasting with largely stalled employment pictures in the other G4 economies (though in the UK this represents a major improvement on job declines seen throughout the past two years).
Outlook and policy
The resilience of the output data from the PMI points to across-the-board resilience of the G4 major developed economies in October, despite sustained strong price growth. As such, the data send a hawkish signal to policymakers, most notably in the US, where not only have output and price growth risen sharply in recent months, but employment gains also point to a tightening labour market, raising the risks of second-round inflationary effects developing.
© 2026, S&P Global. All rights reserved. Reproduction in whole or in part without permission is prohibited.
Purchasing Managers' Index™ (PMI®) data are compiled by S&P Global for more than 40 economies worldwide. The monthly data are derived from surveys of senior executives at private sector companies, and are available only via subscription. The PMI dataset features a headline number, which indicates the overall health of an economy, and sub-indices, which provide insights into other key economic drivers such as GDP, inflation, exports, capacity utilization, employment and inventories. The PMI data are used by financial and corporate professionals to better understand where economies and markets are headed, and to uncover opportunities.
Read our latest PMI commentary here.
This article was published by S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Theme
Location
Products & Offerings