Research — October 15, 2026
Tesla's revenue, earnings expected to edge lower despite delivery beat

By Disha Mandavia
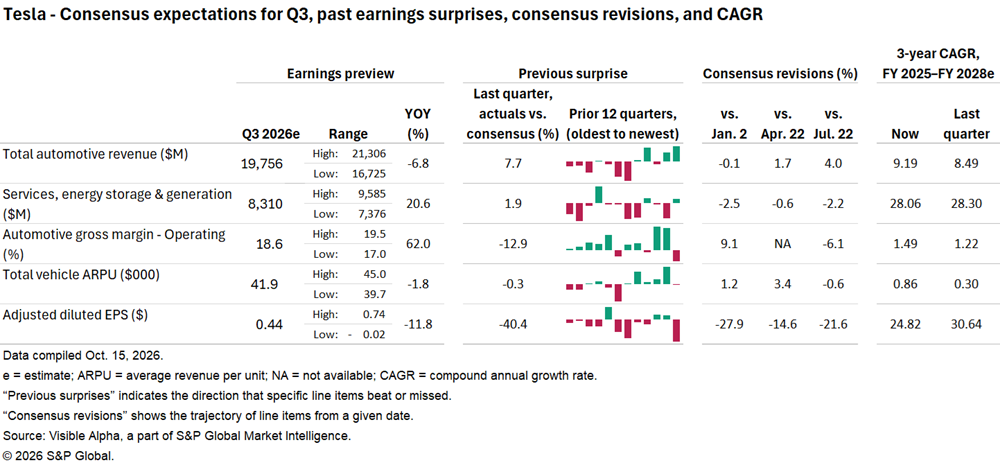
The third-quarter earnings report of Tesla Inc., trading under TSLA on the Nasdaq, will highlight whether stronger-than-expected vehicle deliveries and continued growth in energy storage can offset pressure on its automotive business. The report is due Oct. 21.
The electric-vehicle maker recently disclosed third-quarter production of 464,391 vehicles and deliveries of 486,532, down 2.1% year over year but exceeding the Visible Alpha consensus estimate of 469,000 units. Energy storage deployments reached 13.7 gigawatt-hours during the quarter, up 9.6% from the prior-year period, an indicator of momentum in a business that has increasingly helped diversify Tesla's revenue base.
Despite the stronger-than-expected delivery figures, revenue and earnings are projected to remain broadly under pressure. Visible Alpha consensus estimates put third-quarter revenue at $28.04 billion, down 0.2% from a year earlier and 0.7% from the previous quarter. Adjusted diluted earnings per share are forecast at 44 cents, a 11.8% decline from the prior-year period.
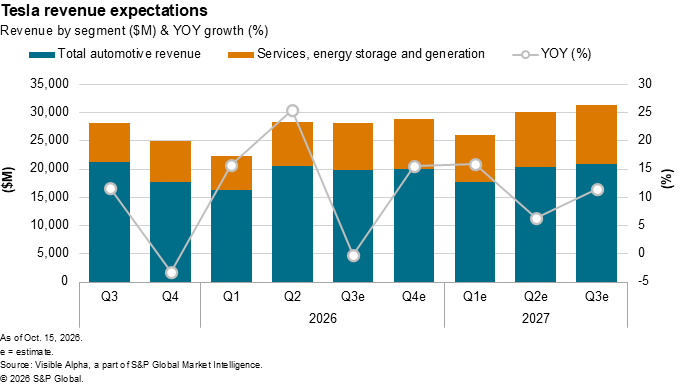
Automotive revenue is expected to remain the principal drag, falling 6.8% year over year to $19.94 billion. Revenue from the Model 3 and Model Y is projected to decline 4.0% to $18.97 billion, while sales of other vehicles, including the Model S, Model X and Cybertruck, are forecast to fall 0.9% to $527.5 million.
Tesla launched its Cybercab in Austin, Texas, during the third quarter, with Dallas targeted as the next deployment market. Third-quarter revenue from the autonomous vehicle service is estimated to reach $23.8 million. Revenue from Tesla's full self-driving software program, meanwhile, is expected to fall 37.5% year on year to $298.8 million.
The services, energy generation and storage segment is likely to provide a counterweight. Revenue from the business is forecast to increase 20.6% year over year to $8.31 billion.
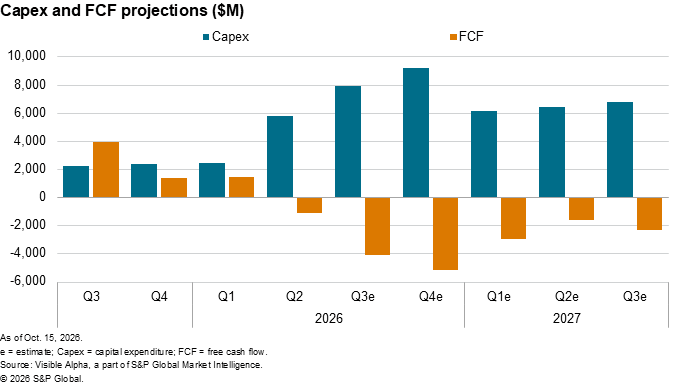
Cash generation is expected to remain under pressure.
Tesla's free cash flow is expected to worsen, reaching negative $4.09 billion, a decline of 202.4% compared to a year earlier. The company's free cash flow turned negative in the second quarter as the company increased spending on AI initiatives and expanded manufacturing capacity.
Third-quarter capital expenditure is forecast to reach $7.94 billion, up from $5.79 billion in the second quarter and an increase of 253.1% from the prior-year period.
Tesla's earnings release and accompanying commentary should also offer clues about automotive demand, pricing pressures and the contribution of newer business lines, including an update on Optimus, the company's humanoid robot.
This article was published by Visible Alpha, part of S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Content Type
Products & Offerings
Segment