Research — October 19, 2026
Meta and Netflix earnings previews

By Melissa Otto, CFA
A look at capex spending
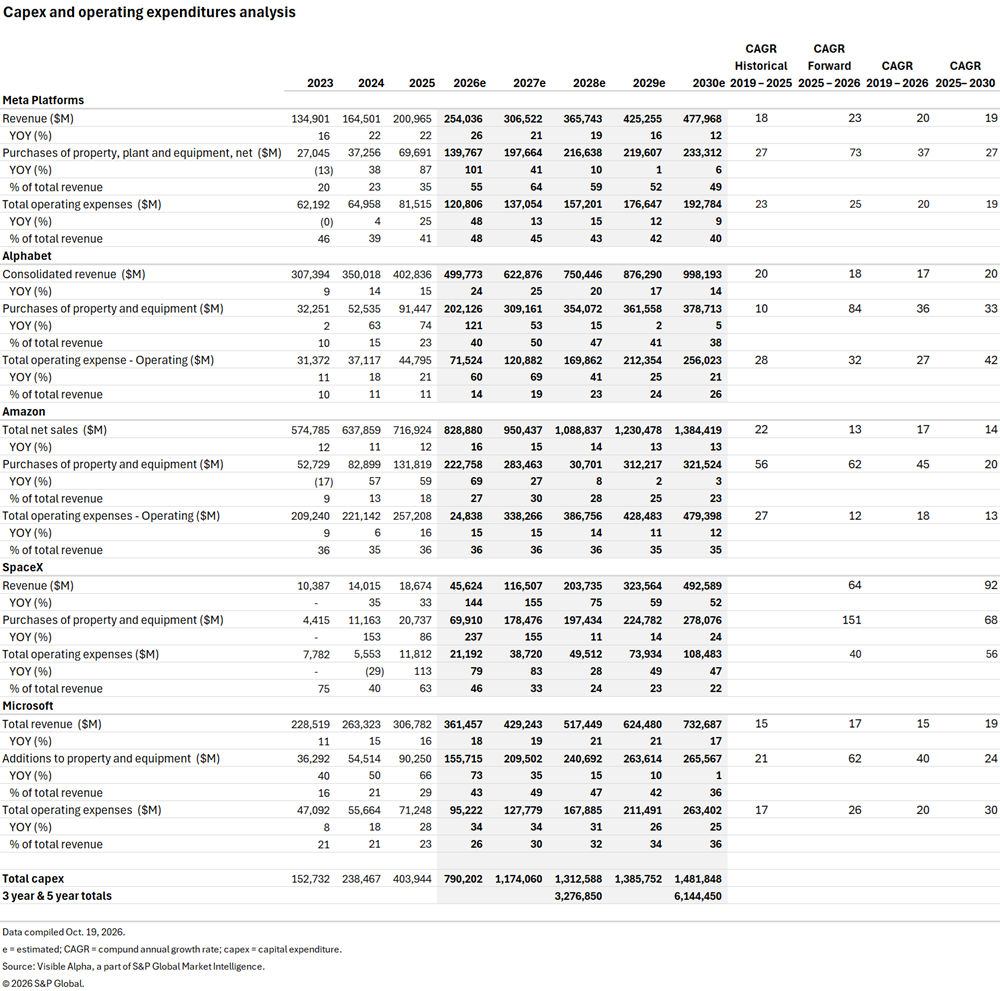
The strong growth in investing in technology infrastructure to support AI has been a focus the past year and is projected to expand this year and next. The expectations for capital expenditure (capex) spending by the hyperscalers continue to move higher.
For 2026, consensus year-over-year capex is expected to almost double from $404 billion to $790 billion.
For 2027, this spending is projected to further increase to $1.17 billion, totaling almost $2 trillion in only two years. The much stronger pace of the expected capex to support the technology infrastructure for AI has caused some concern as the significant ramp in spending is projected to grow faster than revenues.
Will Meta maintain or further increase their capex guidance?
Meta Platforms
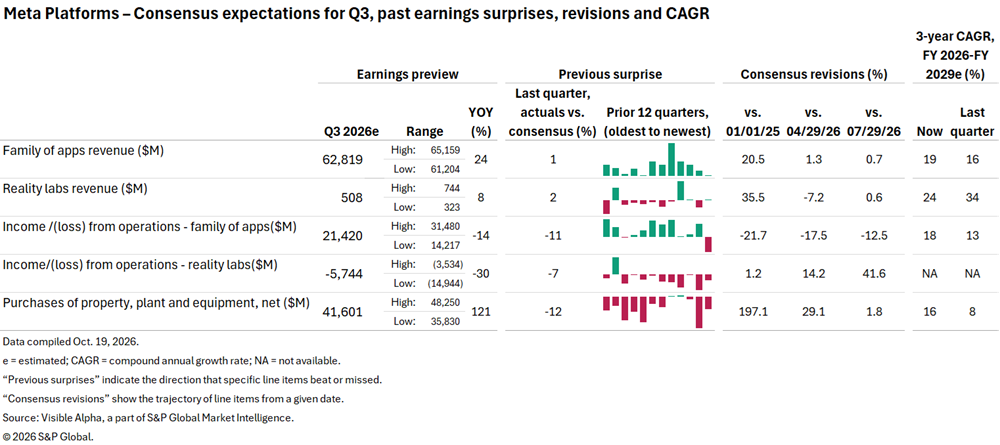
According to Visible Alpha consensus, Meta Platforms Inc.'s total revenue for Q3 is expected to be $63.3 billion, driven by $62.8 billion in the Family of Apps segment, especially in the US and Europe. Operating profit is expected to be $16.9 billion with declining profitability in the Family of Apps of around $22.0 billion and consensus losses remaining around -$5.7 billion for Reality Labs.
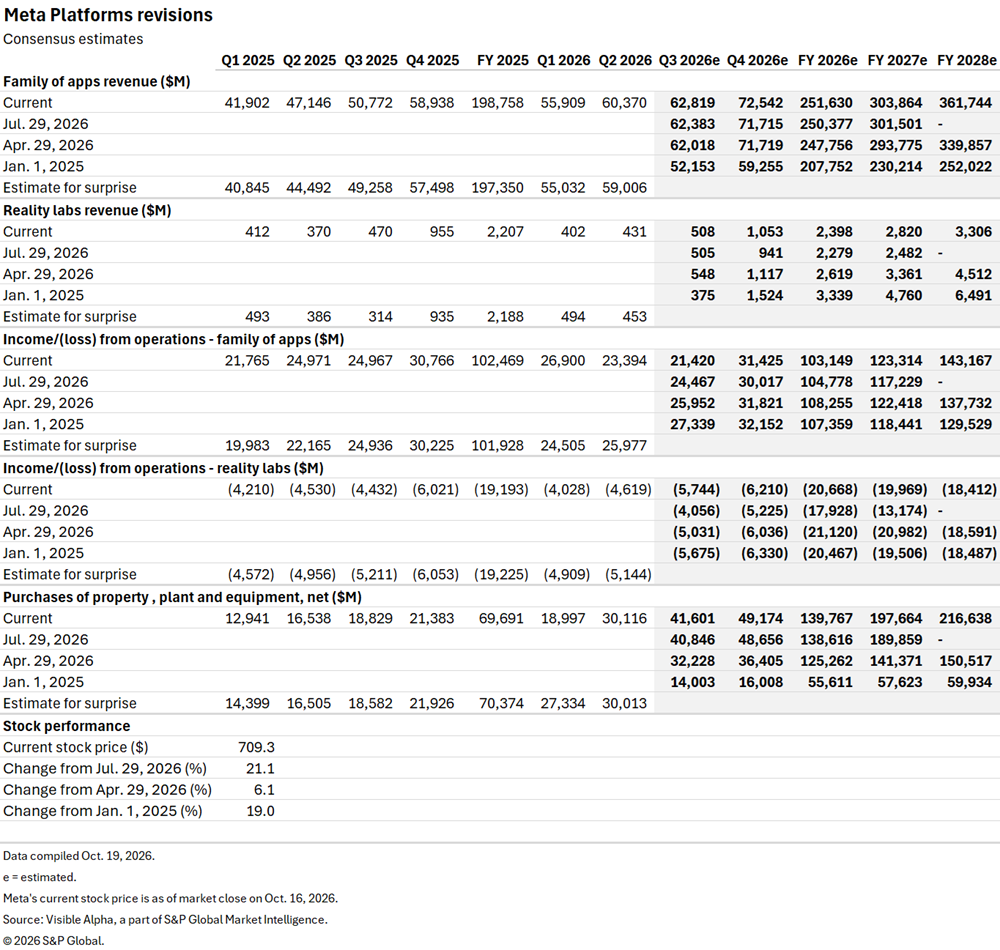
For 2026, earnings expectations for operating income from the Family of Apps have decreased $3 billion to $21.4 billion since July 2026, driven by slightly shifting views about ad revenue per DAU in the US and internationally. The management commentary on the outlook in the earnings call will be key to assessing the potential direction of revisions for Q4 2026 and FY 2027. In addition, the projected losses from Reality Labs for 2026 have increased $2.8 billion for 2026 to -$20.7 billion, due to higher expected ongoing losses in the division.
Last year, CEO Mark Zuckerberg highlighted that the company planned to invest in servers and data centers to support AI. Since the April quarter, capex consensus increased over $14 billion to $139.7 billion for FY 2026, almost double from FY 2025. There are questions about whether Meta will further increase their capex this year. Estimates for capex have moved notably higher for FY 2027 and FY 2028 since last quarter.
The market will likely want some clarity around how these investments translate into returns for shareholders.
Meta stock has been outperforming since July, up 26% since last quarter. The consensus implied return is currently 17.5% on a P/E multiple for FY 2028 of 18x down from 21x last year.
Will Meta be able to deliver a profit surprise in Q3 2026 and continue to outperform?
Netflix
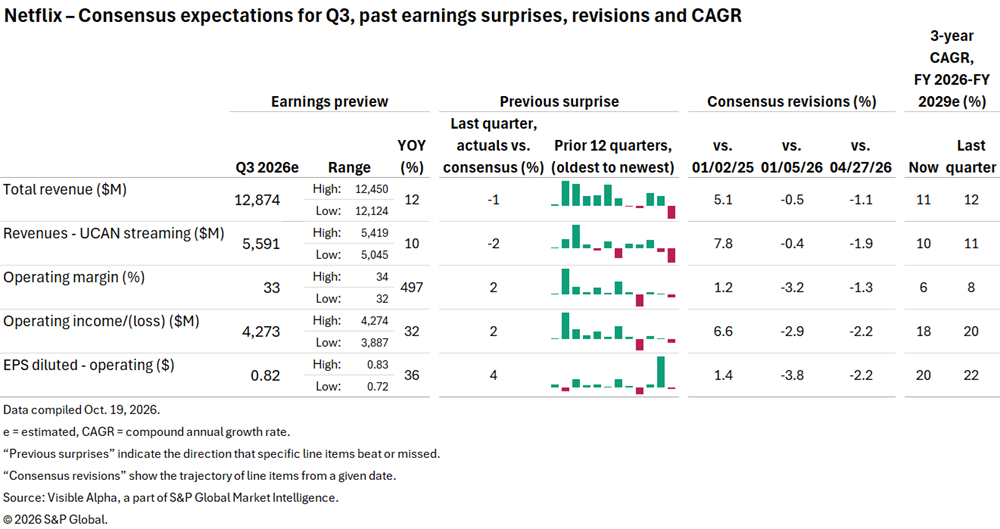
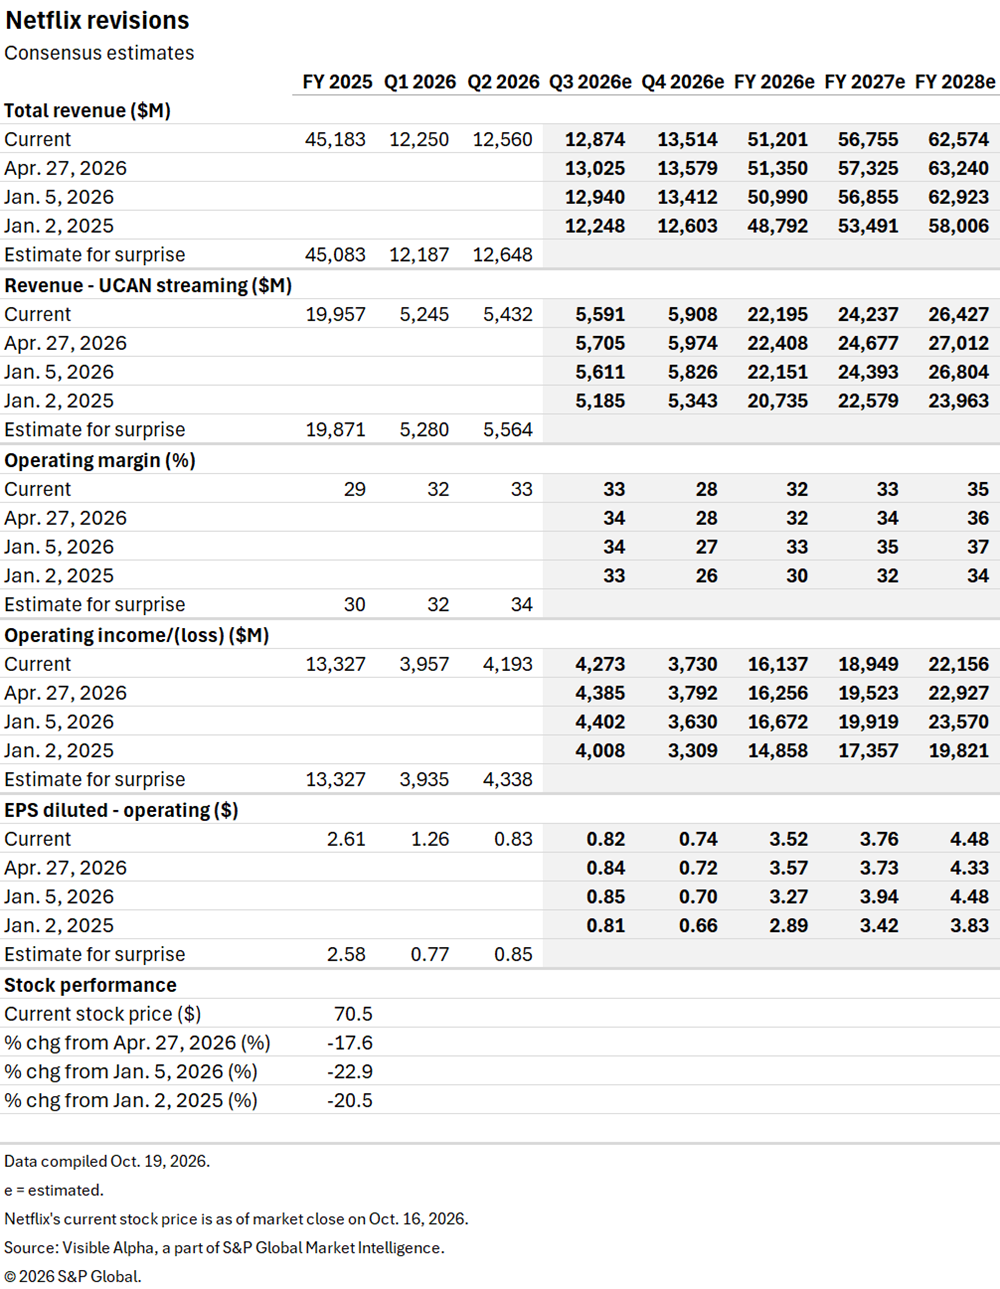
Netflix Inc. expectations into Q3 have remained stable all year. Visible Alpha consensus is expecting $12.9 billion in revenue for Q3 and $51.2 billion for FY 2026. Revenues are expected to be supported by continued new membership and monetization. Offering a range of pricing and plans combined with continuing growth in the ads business is expected to further increase monetization and engagement. Consensus expects the operating margin to be 33% in Q3, down from earlier expectations of 34% due to assumptions about higher expenses, and to be 32% for FY 2026.
The company expects to grow revenues by increasing engagement trends and reducing churn while offering a more diverse entertainment offering. Gaming and the growth of ads could be key drivers in 2027. According to consensus, analysts now expect the company to generate the 32% margin, on expected revenue of $51.2 billion and $16.1 billion in operating profit in FY 2026.
Netflix remains upbeat about the long-term opportunity for advertising, given the size of its user base. FY 2026 expectations are $7.7 billion for ad-supported revenues in global streaming from six sources. For FY 2027, ad-supported revenue is expected to increase 44% to $11.1 billion for ad-supported revenues.
Based on Visible Alpha consensus, the operating profit margin is expected to grow from 26.7% in FY 2024 to 35.0% in FY 2028, down from previous expectations of 37%. However, there is significant debate among analysts with respect to FY 2026 and FY 2027 margin estimates, as the market has a range of views around how much the company will ramp up operating expenses.
This margin trajectory is expected to take FY 2027 expected diluted EPS to $3.76/share or 19x FY 2027 P/E, lower than the 30x it traded last summer. The current consensus target price has ticked down to $93 from the previous target of $130 or 28% upside from the current levels.
Netflix shares have been underperforming. Will this quarter start to turn things around for the stock?
Visible Alpha is a part of S&P Global Market Intelligence. Full Visible Alpha data is available only via subscription. For more information or to express your interest, please contact your S&P Global Inc. relationship manager.
Content Type
Products & Offerings

