Research — November 5, 2026
Data center strength powers AMD's revenue in Q3
Advanced Micro Devices Inc. (NASDAQ: AMD) released its third-quarter fiscal 2026 earnings on Tuesday, Nov. 3. Drawing on S&P Global Pronto NLP earnings summaries, Capital IQ Pro earnings-call transcripts and Visible Alpha consensus estimates, here are the key takeaways.
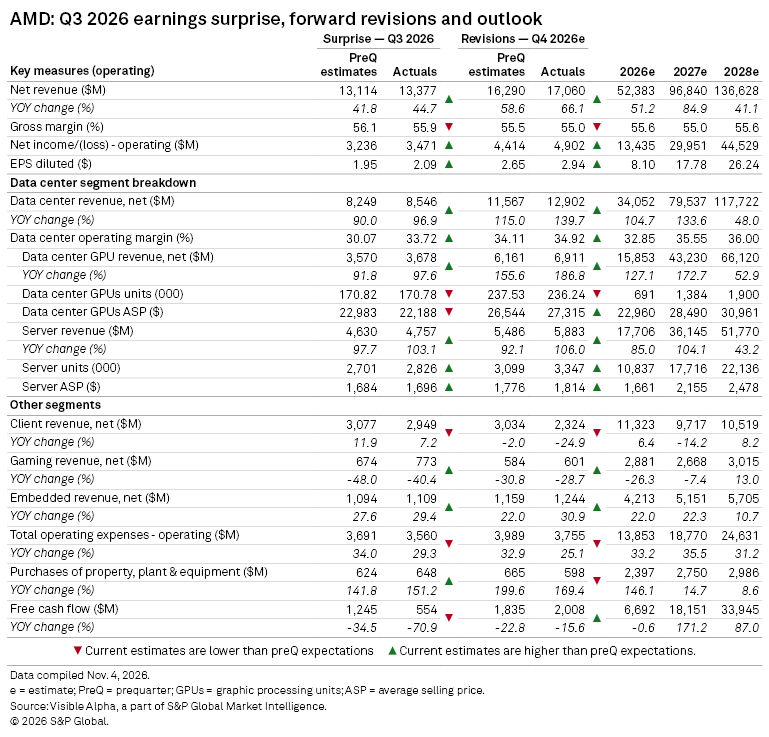
AMD generated $13.38 billion of revenue in the third quarter, beating Visible Alpha's consensus estimate, thanks chiefly to the performance of its data center business.
Revenue in the data center division nearly doubled year over year to $8.55 billion, well ahead of the $8.25 billion consensus estimate. The segment's operating margin reached 33.7%, exceeding the consensus estimate by 365 basis points. Within the data center segment, server revenue jumped 103% year over year to $4.76 billion, while GPU sales rose 97.6% to $3.68 billion, both exceeding analyst forecasts.
Data center sales account for about 64% of AMD's total net sales, up from 47% a year ago.
AMD's client business revenue, which includes PC processors, ticked up just 7%. That was below expectations as higher memory and component costs suppressed demand. Gaming sales dropped 40.4% to $773 million, but that was better than analyst estimates.
Capital expenditure surged 151% to $648 million, highlighting AMD's aggressive investment in AI infrastructure and capacity expansion. Free cash flow dropped to $554 million, missing estimates by 55.5%, as higher spending and working capital requirements weighed on liquidity. Non-GAAP diluted earnings per share came in at $2.09, beating the consensus by 7.1%.
Data center revenue expected to ramp further
The chip giant said revenue in the fourth quarter will come in around $17 billion, ahead of analyst expectations of $16.29 billion. For the data segment, fourth-quarter revenue is expected to be $12.90 billion.
Analysts have become more constructive on AMD's longer-term data center prospects. Visible Alpha estimates for data center revenue have increased by $1.3 billion to $34.05 billion, reflecting expectations for a production increase of Helios rack-scale AI systems and next-generation Venice server processors. Consensus forecasts now place data center revenue at $79.54 billion in 2027, rising further to $117.72 billion in 2028.
Visible Alpha estimates for fourth-quarter client revenue were cut by 23.4%, while full-year forecasts are now down by 6.3%. Expectations for the gaming and embedded segments, however, moved higher.
AMD expects fourth-quarter non-GAAP gross margin of approximately 55%, compared with 56% in the third quarter, due to a modestly less favorable product mix.
Non-GAAP operating expenses are forecast at approximately $3.75 billion as the company continues investing in AI silicon, software capabilities and strategic initiatives.
Important notice
Copyright © 2026 by S&P Global Market Intelligence, a division of S&P Global Inc. All rights reserved.
The disclosures, disclaimers, and other important legal information applicable to this material are incorporated herein by reference and available at https://www.spglobal.com/market-intelligence/en/legal/disclosures.
This article was published by Visible Alpha, part of S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Content Type
Theme
Products & Offerings
Segment

