Research — Sep 18, 2026
US coal production is trending lower year over year
By Steve Piper
Lower natural gas prices have persisted through peak summer months, favoring gas-fired generation over coal in the US, which has reduced thermal coal demand. This has been exacerbated by elevated coal stockpiles and seasonal shoulder-period weakness, further limiting domestic coal burn and shipments. The Energy Information Administration (EIA) recently forecast US total coal consumption to fall 8% year over year in 2026. Finally, domestic metallurgical coal demand has also been pressured by weak global steel demand, especially affecting US production.
Exports have grown this year, however, partially offsetting weakness in domestic demand. US coal exports were up 19.1% year over year during the second quarter. Higher LNG and natural gas prices tied to the Middle East conflict led to gas-to-coal switching in Europe and Asia, boosting seaborne thermal coal demand. While domestic metallurgical demand trended lower, metallurgical coal exports were supported by the reopening of West Virginia mines and the opening of Warrior Met Coal's Blue Creek mine, which added exportable supply. These factors boosted producer second-quarter results despite lackluster US demand.
Lower-priced natural gas combined with high coal stockpiles are forecast to constrain coal production through 2027. Although natural gas prices are expected to normalize after 2027, the US coal market will face renewed pressure from the expansion of solar and wind generation in regions with supportive economics and supportive state policies. The S&P Global Market Indicative Power Forecast further projects coal plant retirements and reduced utilization through 2035, when 44.4 GW of coal plants are forecast to retire. Coal plant generation share through 2035 is forecast to decline to 7.2% from 16.3% of total generation in 2027.

➤ Domestic coal prices continued to fall modestly during August, with high inventories more than offsetting summer power demand.
➤ Elevated domestic coal inventories and competitive natural gas are likely to result in lower aggregate production this year compared to 2025, with Powder River Basin coal showing large declines.
➤ In the longer term, S&P Global Market Indicative Power Forecast now projects 44.4 GW of coal plant retirements by 2035, an increase of 8.3 GW from prior forecasts as natural gas generation adds competitive pressure.

Coal benchmark prices eased further during August, as natural gas prices remained low and stockpiles remained high. Export benchmark prices mostly declined, with CAPP region export benchmarks down $1.00/short ton to $81.00/st (1.2%), NYMEX CAPP also down $1.00/st to $79.00/st (1.3%), and NAPP Pittsburgh Seam 13,000 British thermal units per pound up by $0.25/st to $70.25/st. Domestic coal benchmark prices eased slightly as well, with Illinois Basin 11,500 mid-sulfur falling $0.25/st to $54.00/st (0.5%), while the NYMEX Powder River Basin benchmark lost $0.15/st to $14.50/st (1.0%).
While global crude oil and natural gas prices continued to be volatile during August, US natural gas prices declined as summer peak demand eased in most regions. Henry Hub spot prices opened August at $2.59 per million Btu, rising modestly over the month to close at $2.82/MMBtu. Spot prices averaged $2.76/MMBtu for the month. Seasonal storage injections continued, with working gas at 3,184 billion cubic feet as of Aug. 21. This was 167 Bcf above the five-year average and 30 Bcf below the same week of 2025.
Regional gas market discounts followed their normal pattern for the summer months. Chicago Gate averaged $2.54/MMBtu, a $0.22/MMBtu discount to Henry Hub. TCO Pool's discount was $0.85/MMBtu for a monthly average of $1.91/MMBtu, while TETCO M3 moved to a discount of $0.86/MMBtu for a monthly average of $1.90/MMBtu. Summer draws of natural gas for generation surged in the Western US, with SoCal Border moving to a premium to Henry Hub of $0.61/MMBtu, at $3.37/MMBtu during August.
The EIA estimated May coal stockpiles at 120 million st, 4 million st higher than April. Spring months typically see coal plants add to their stockpiles, but with stockpiles already elevated this year, stockpile growth may be limited.
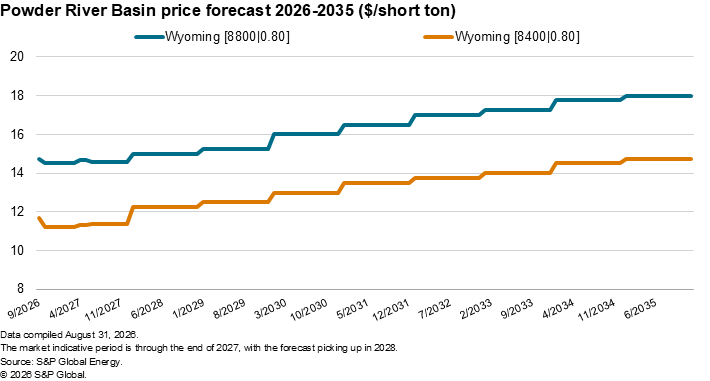
Current forward pricing for PRB coal has been flat and stable, reflecting surplus inventories at power plants. After 2027, competitive natural gas prices and declining coal demand are forecast to restrain price growth.
Bituminous coal price levels are primarily influenced by export markets, with today's price levels making domestic coal generation uncompetitive against Northeast natural gas. The current disruption in international energy markets has elevated export coal prices, likely through 2027. As natural gas prices normalize after 2027, we project coal prices to ease.
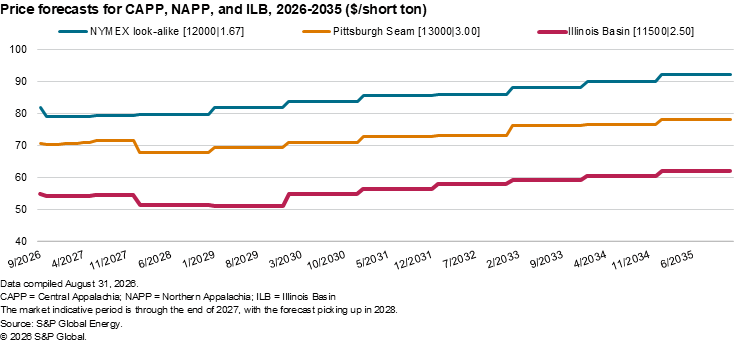
Pricing benchmarks exceeding $70/st suggest sustainable returns for eastern bituminous coal, with Atlantic Basin export coal above that threshold and coal competing in Pacific Basin export markets generally much closer. Bituminous coal demand for electric generation is expected to remain stable through 2027 on higher electricity demand. Declines in steam coal demand are expected to resume after 2027, and overall Eastern US coal demand is forecast to decline 55 million st in 2025-30.
Outlook for US coal production, demand
For the four weeks ending Aug. 22, coal shipments averaged 10.2 million st, 6.4% below the same period in 2025. While August shipments trended higher than July, ongoing subdued shipments during the summer peak season indicate the impact of high inventories and modest coal plant utilization.
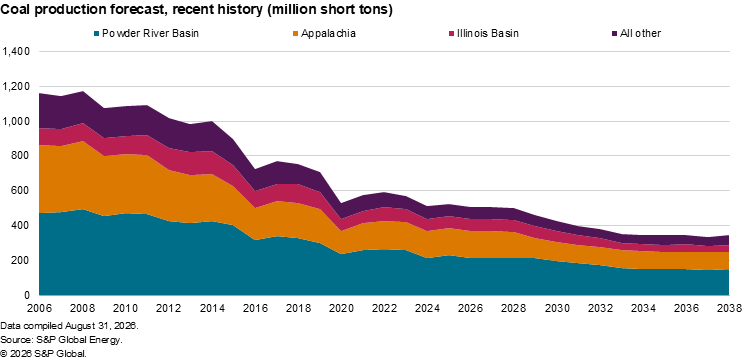
The chart below compares the current production forecast with recent history. Where previously we forecast overall production growth this year, we now forecast production at 510 million st this year, a 3.2% decline from 2025. We forecast flat production in 2027, with higher natural gas prices offset by robust coal inventories. Beginning with 2028, growth in generation from natural gas and green energy is forecast to reduce coal generation. The overall coal market, including domestic demand and exports, is forecast to decline by 122 million st between 2026 and 2031.
Production outlook — Powder River Basin
Forecasts of reduced aggregate production this year are mainly attributable to declines in Powder River Basin production. Production reports of the Mine Safety and Health Administration (MSHA) covering the first half of 2026 indicate year-to-date production of 101.4 million st, an annualized rate of 202.9 million st. Production for 2026 is now forecast at 212 million st, 7.8% below 2025. Production is forecast to grow slightly through 2029 against higher natural gas prices. By 2030, S&P Global Energy projects that coal retirements in the Midwest and expansion of wind generation in PRB's core markets will gradually shrink coal demand to 198 million st, declining further to 149 million st through 2035.
Production outlook — Illinois Basin
MSHA's 2026 second-quarter production reports indicate first-half 2026 production of 35.0 million st, an annualized rate of 70.0 million st. We forecast production will hold at 67 million st this year through 2028, after which the expansion of wind generation and announced coal retirements are forecast to erode ILB coal demand. Coal production in the ILB is forecast to fall to 61 million st by 2030, declining further to 41 million st by 2035.
Production outlook — Appalachian basins
MSHA's production reports for the second quarter of 2026 indicate first-half 2026 production of 81.9 million st, an annualized rate of 163.9 million st. Appalachian coal demand tends to be more sensitive to global seaborne markets than to domestic natural gas prices, compared to the PRB or the ILB, which are forecast for improved demand against natural gas generation; therefore, gains in Appalachian coal will be more limited. We forecast stable production levels of 160 million st per year through 2027. As remaining domestic demand erodes after 2027, with only modest offsets from export growth, Appalachian production is forecast to fall to 110 million st by 2030.
Further information
Market Indicative coal forecasts by S&P Global Energy represent forward curves for spot-traded instruments, analogous to a strip of contracts. The shorter tenors — current year and prompt year, plus additional years, if available — are driven by the observed/assessed marker prices. The longer tenors — typically forecast years three to 20 for physically assessed markers — are driven by fundamental estimates of cash costs of production, accepted returns to capital, regional productive capacity, and forecast supply and demand. For the long-tenured portion of the curve, S&P Global Energy forecasts prices for specific coal markers and defines the remaining markers via historical spreads.