Research — SEPTEMBER 15, 2026
Higher realized oil prices to drive Occidental’s return to growth in 2026

By Karan Sadh
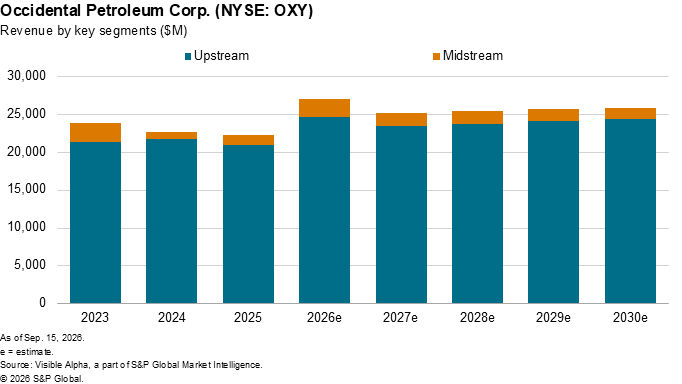
US oil and gas producer Occidental Petroleum Corp. (NYSE: OXY) is expected to return to revenue growth in 2026, with higher realized oil prices doing most of the work as production remains broadly flat. Analysts expect net revenue to rise 6% to $26.4 billion, reversing three consecutive years of decline, while upstream revenue is forecast to increase 18% to $24.7 billion.
The recovery is expected to be driven largely by pricing rather than higher output. Analysts forecast Occidental’s crude oil and natural gas liquids production to remain broadly unchanged at about 384 million barrels in 2026, compared with 385 million barrels in 2025. By contrast, the average oil price excluding hedging is expected to rise 24% to $82 a barrel, while NGL prices are forecast to increase 9% to $22 a barrel.
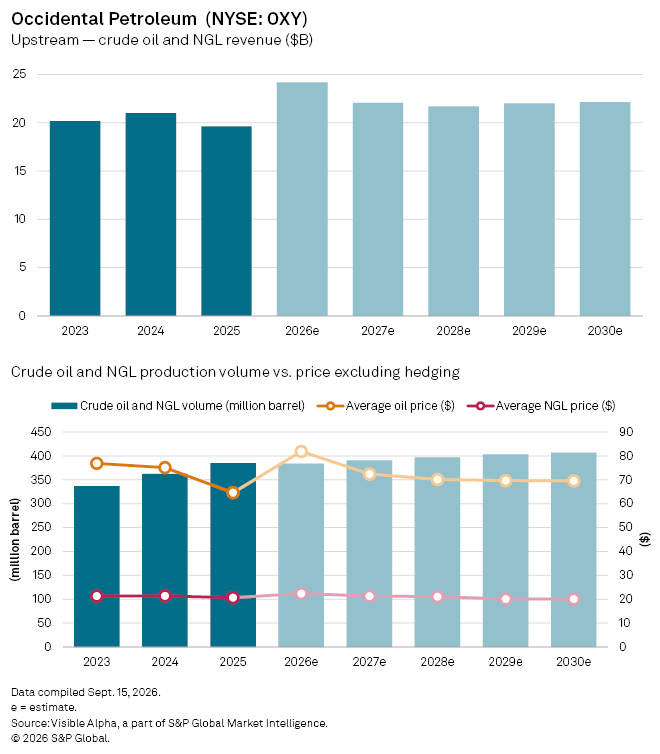
The pricing tailwind is reflected in analysts’ expectations for crude oil and NGL revenue, which is forecast to rise 23% to $24.1 billion in 2026. With production largely unchanged, the increase points to higher commodity prices as the primary driver of Occidental’s upstream recovery.
The stronger upstream outlook is also expected to support a sharp increase in cash generation, with analysts forecasting free cash flow to rise nearly 80% in 2026. The additional cash should help Occidental reduce debt and lower its leverage following the 2024 acquisition of CrownRock, which expanded its Permian Basin position but increased its debt burden. Management has also pointed to cost savings and lower interest expense as key drivers of cash-flow improvement. As free cash flow strengthens, analysts expect Occidental’s leverage ratios to decline significantly, potentially improving its financial flexibility and capacity to return capital to shareholders.
The growth trajectory is expected to reverse in 2027 as the benefit from higher commodity prices fades and the loss of OxyChem revenue following its divestiture on January 2, 2026. Analysts expect net revenue to decline 8% in 2027.
This article was published by Visible Alpha, part of S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Content Type
Products & Offerings
Segment

