Research — October 19, 2026
SpaceX earnings preview: Q3 2026

By Melissa Otto, CFA
A look at capex spending
The strong growth in investing in technology infrastructure to support AI has been a focus the past year and is projected to expand this year and next. The expectations for capital expenditure (capex) spending by the hyperscalers continue to move higher. For 2026, consensus year-over-year capex is expected to almost double from $404 billion to $790 billion. For 2027, this spending is projected to further increase to $1.17 billion, totaling almost $2 trillion in only two years. The much stronger pace of the expected capex to support the technology infrastructure for AI has caused some concern as the significant ramp in spending is projected to grow faster than revenues. Will Space Exploration Technologies Corp. (SpaceX) maintain or further increase their capex guidance?
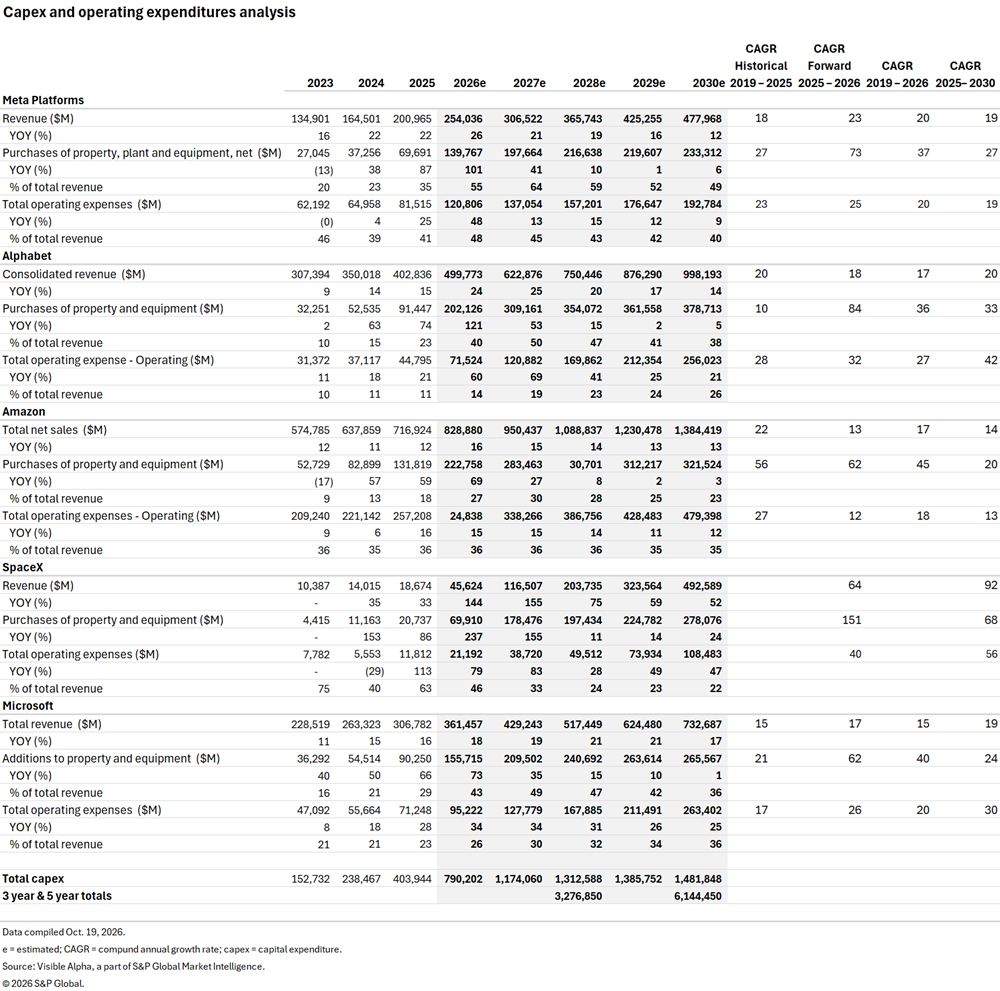
We are closely watching what the company will say about its capex investments into each of its segments, as SpaceX’s capex numbers are expected to increase from $69.9 billion this year to $194.3 in FY 2028. According to consensus projections, Connectivity capex estimates are projected to surge 5x from $4.2 billion in FY 2025 to $22.8 billion in FY 2028. In addition, SpaceX’s overall debt is also projected to grow nearly 7x from $50.7 billion in FY 2025 to $350.0 billion in FY 2029.
Q3 earnings preview
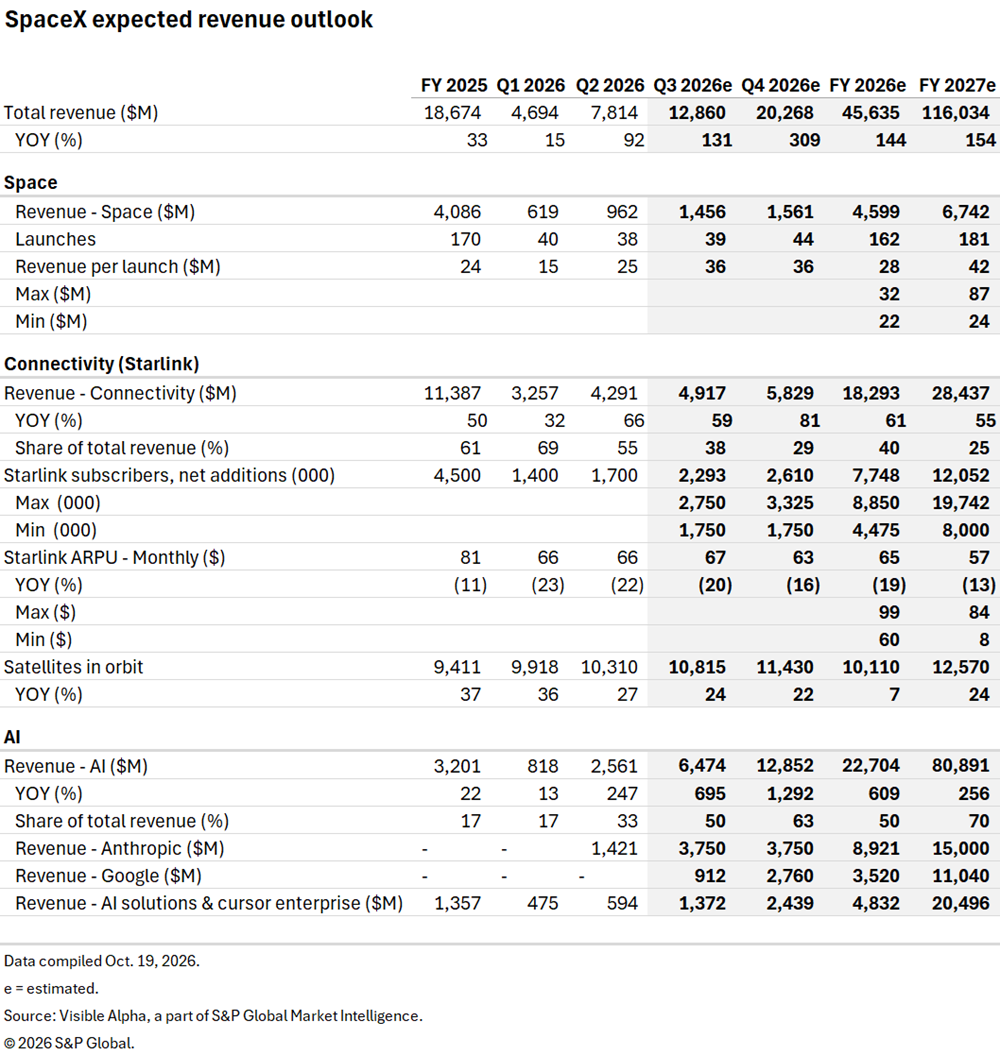
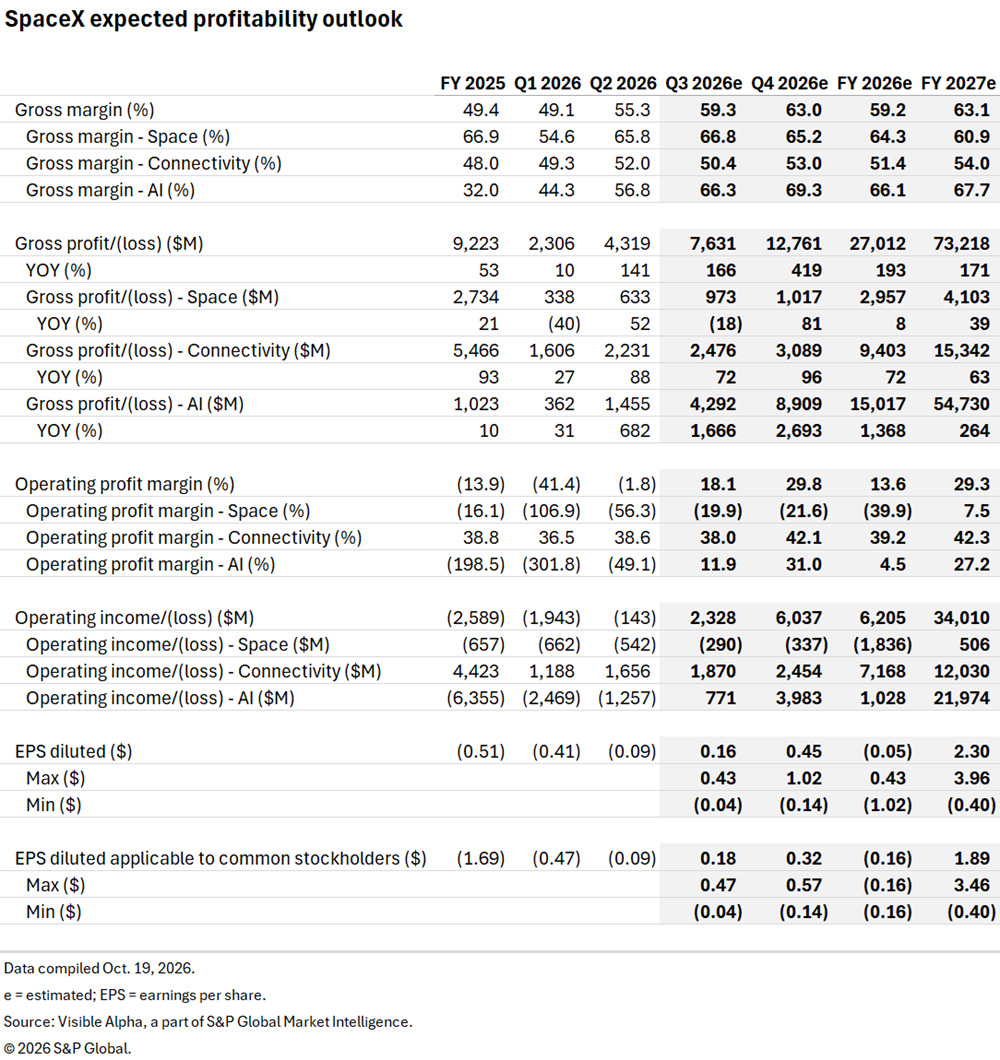
Looking ahead to Q4 2026, analysts expect the Connectivity business to grow revenue year-over-year over 80% to $5.8 billion and to deliver a 42.1% operating profit margin, up over 400 bps from last quarter. It will be interesting to assess the overall Connectivity segment performance in Q3 and to hear what SpaceX says about the Q4 and 2027 outlook. Longer term, analysts are also split in their views. For the Connectivity business, Visible Alpha consensus expects the operating profit margin to increase to 42.3% in FY 2027. In addition, Space and AI operating profit estimates for FY 2027 are expected to turn positive and support earnings growth. Currently, the total operating profit margin is expected to go from 13.6% this year to 28.6% next year, driven by significant margin expansion in AI and Space.
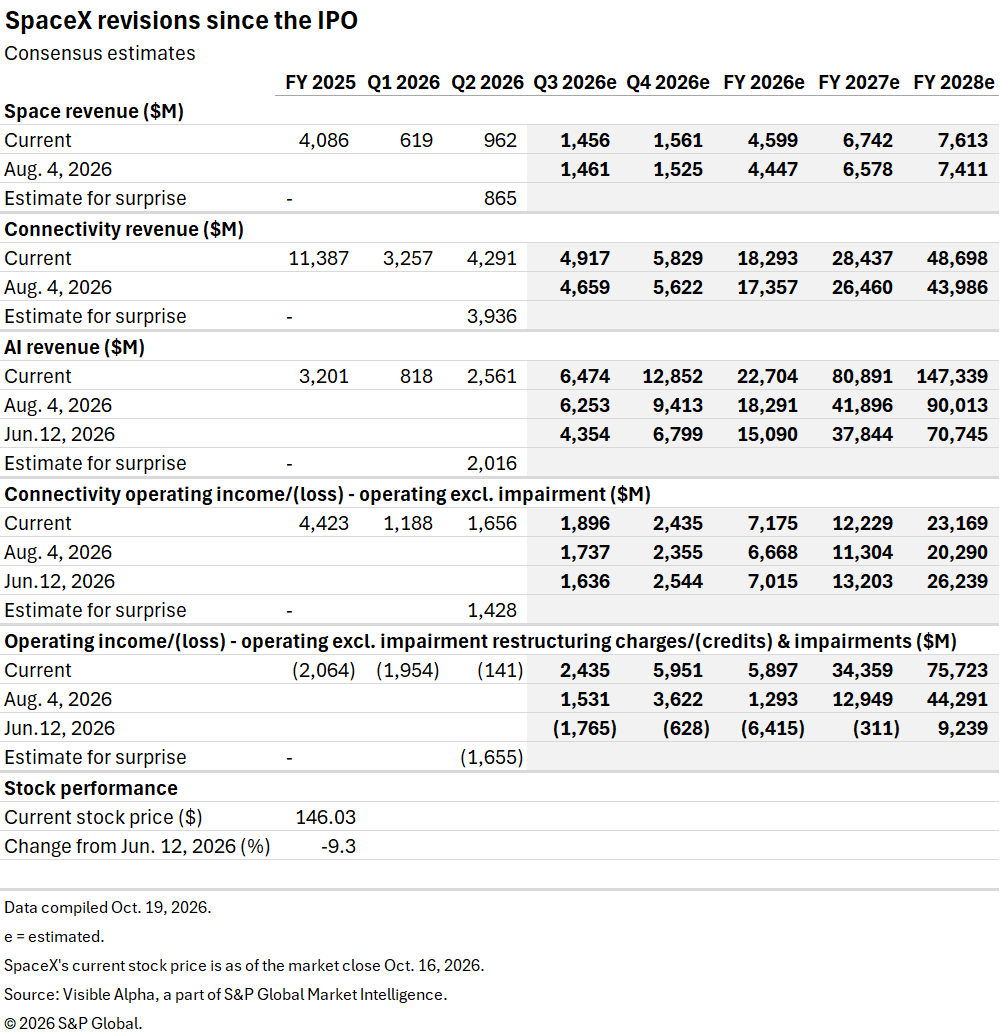
The expectations for the AI revenues and profitability have significantly increased for 2027 and 2028 since the IPO. The FY 2028 AI revenue expectations have doubled since the IPO and total operating profit is up over 8x since the IPO, signaling strong optimism for the AI business’s growth and profitability.
SpaceX stock has declined 7.7% since the June IPO, underperforming the S&P 500. The stock seems to be far from its consensus target price of $274 with a current implied return of 84%. The weakness has been partially driven by concerns about overgrowth around AI and data centers. There is increasing concern in the market that AI infrastructure investments will not be able to generate a return in line with the level of cash needed. Could the Q3 release provide more visibility into the trajectory of investments and profitability and give shares a boost?
Visible Alpha is a part of S&P Global Market Intelligence. Full Visible Alpha data is available only via subscription. For more information or to express your interest, please contact your S&P Global Inc. relationship manager.
Content Type
Products & Offerings
Segment
