Research — October 15, 2026
Shanghai Putailai poised for sharp growth as battery demand strengthens
By Deepak Jain
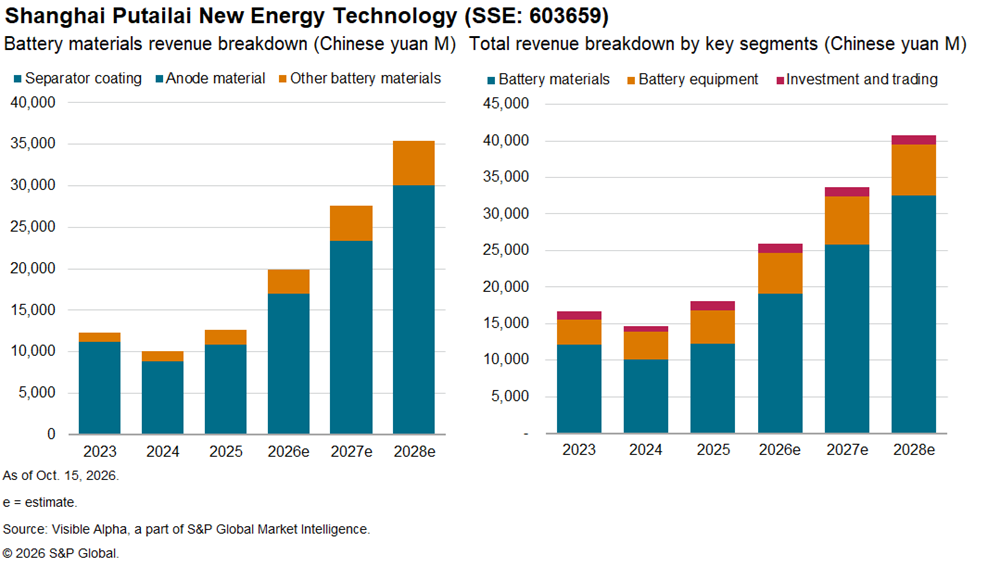
Shanghai Putailai New Energy Technology Group Co. Ltd., a Chinese supplier of materials and equipment for lithium-ion batteries trading as 603659 on the Shanghai Stock Exchange, is expected to accelerate growth in 2026 as recovering prices and stronger demand support its core battery materials business.
The company's full-year 2026 revenue is estimated to grow 48% year over year to 23.3 billion Chinese yuan, according to Visible Alpha consensus estimates, with battery materials expected to drive most of the increase as segment revenue rises 56% to 19.2 billion yuan.
The recovery comes as China's battery materials industry emerges from a prolonged downturn, marked by falling prices and excess capacity. Improving demand for electric vehicles and energy storage systems supports production volumes, while stabilizing prices in parts of the supply chain could improve suppliers' revenue growth, even as pricing conditions remain uneven across products.
Separator coating and anode materials are expected to drive growth in Shanghai Putailai’s battery materials business, with separator coating revenue forecast to rise 44% to 9.6 billion yuan in 2026 and anode material revenue projected to increase 76% to 7.4 billion yuan.
The anode-material business is expected to stage a particularly strong rebound after revenue fell 6% in 2025 and 30% in 2024, amid declining average realized prices and weaker sales volumes. For 2026, analysts expect average realized prices to recover 8%, alongside a 63% surge in sales volumes, supporting a sharp turnaround in segment revenue.
Meanwhile, separator coating is expected to benefit primarily from volume growth. Segment sales volumes are forecast to increase 59% to approximately 17.4 billion square meters in 2026, more than offsetting an expected 9.3% decline in average realized prices. The segment's share of battery materials revenue is also expected to increase to nearly 50% in 2026 from 39% in 2023, underscoring its growing importance to the company's business mix.
Shanghai Putailai is scheduled to report its next earnings results on Oct. 20.
This article was published by Visible Alpha, part of S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Content Type
Products & Offerings
Segment
