Research — October 26, 2026
Microsoft and Alphabet earnings previews

By Melissa Otto, CFA
Capex overview
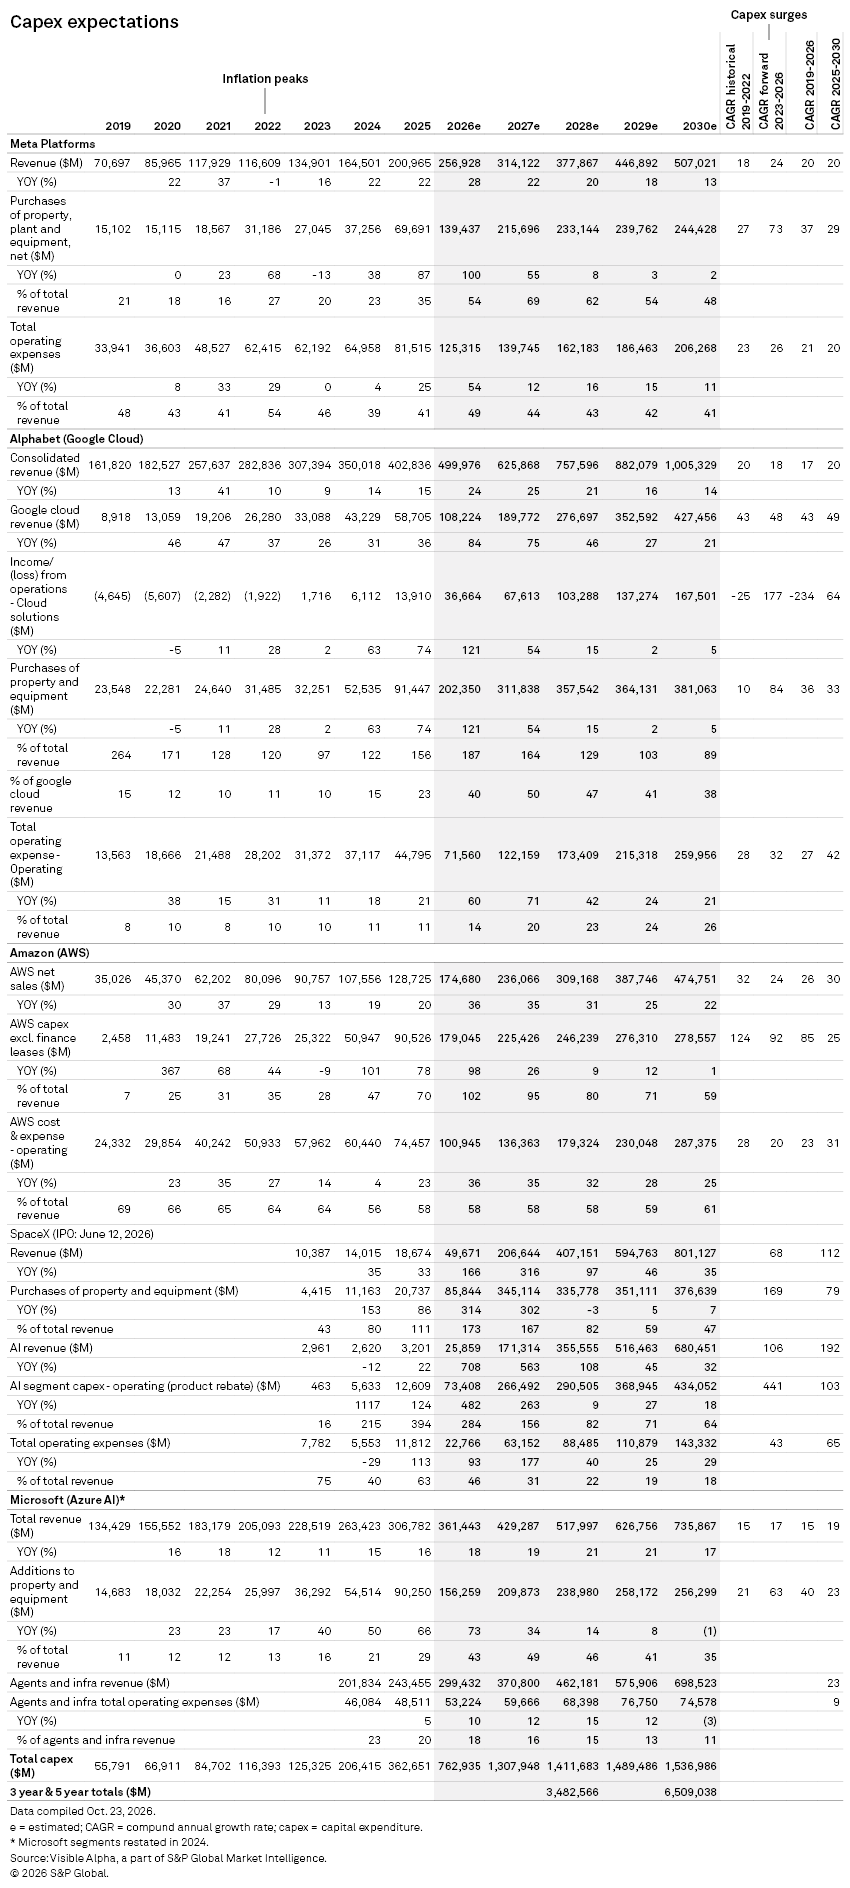
The strong growth in investing in technology infrastructure to support AI has been a focus the past year and is projected to expand this year and next. The expectations for capital expenditure (capex) spending by the hyperscalers continue to move higher. For CY 2026, consensus year-over-year capex is expected to more than double from $362 billion to $763 billion. For CY 2027, this spending is projected to further increase to $1.3 trillion, totaling over $2 trillion in only two years. The significant ramp in spending is projected to grow faster than revenue in the near term, implying adverse margin impact. Will Microsoft Corp. and Alphabet Inc. maintain or further increase their capex guidance to keep pace with peers?
Microsoft earnings preview
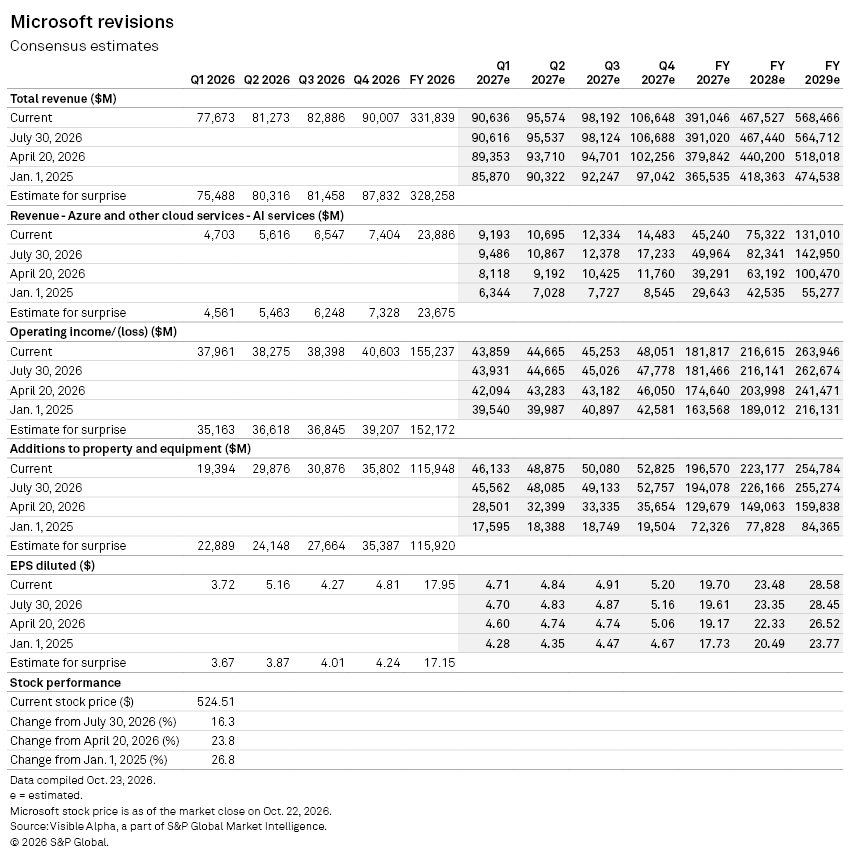
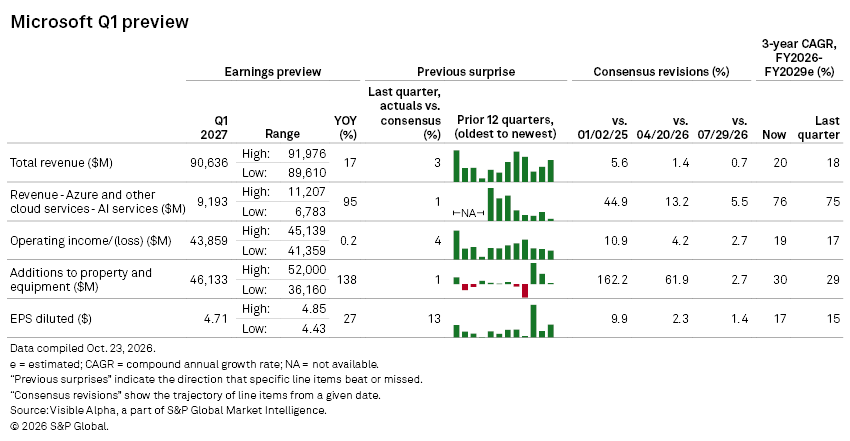
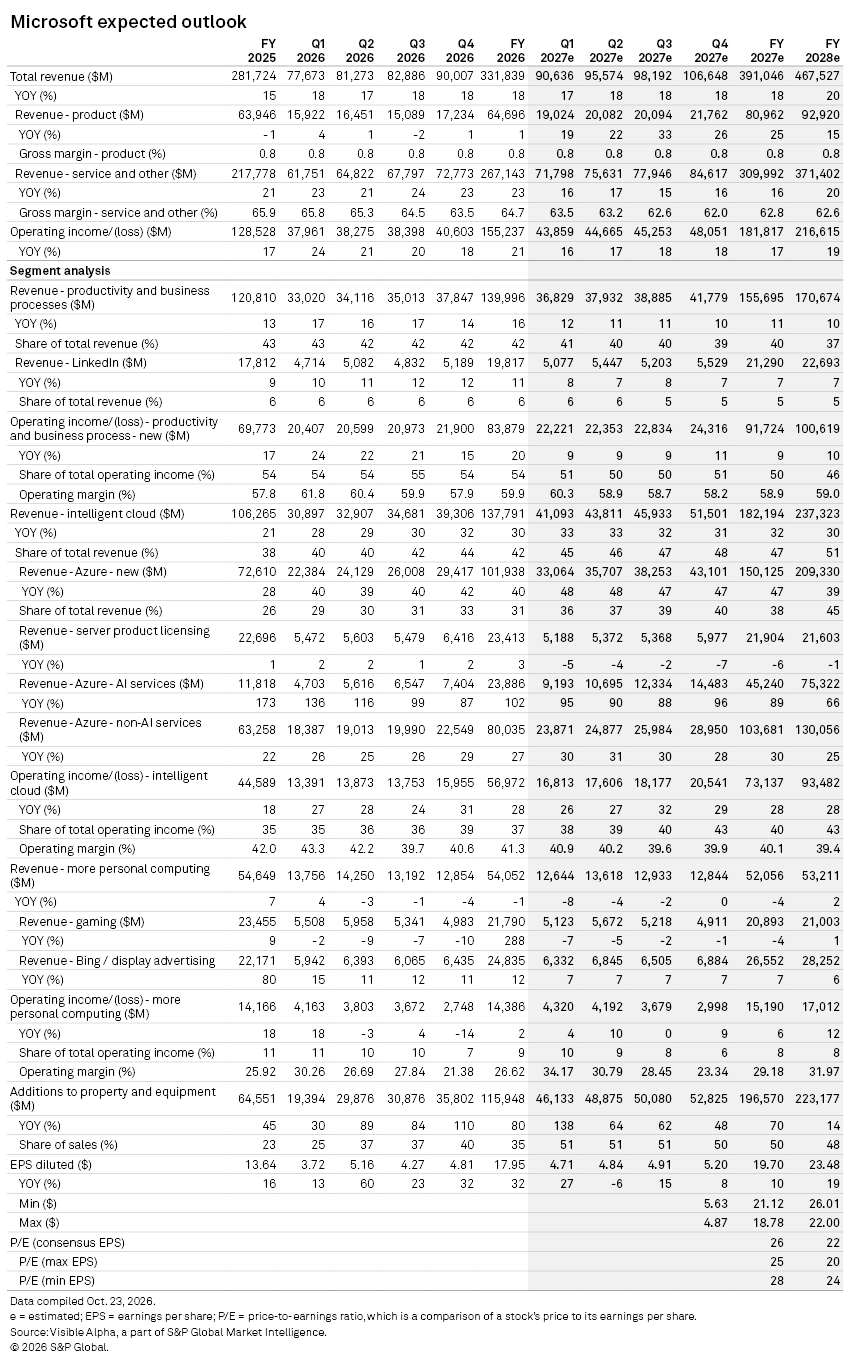
Total revenues expected for Q1 have remained stable this year, driven by a resilient view of Microsoft's business. Expectations for the new Azure AI Services segment have been increasing. This segment is projected to nearly double year-over-year for FY 2027. Consensus estimates for Q1 2027 project $9.2 billion, up from $8.1 billion in April 2026. Expectations for this segment in Q2 2027 have also ticked up since April 2026, suggesting the market's optimism has been increasing around this segment. The market will likely focus on the AI Services growth and adoption and how these metrics may provide a runway for the outlook. Consensus profitability for Q1 2027 has edged up for the Company, driving EPS expectations for the quarter and outlook years higher. The market will likely want clarity about the trajectory of growth in the Azure AI business and its overall impact to the Intelligent Cloud segment and to the overall business going forward.
We are also closely watching what the company will say about the outlook for Azure and OpenAI, as Microsoft's 2027 and 2028 capex numbers have continued to increase steadily. According to current consensus projections, capex estimates are expected to triple from $64.6 billion in FY 2025 to currently $196.6 billion in FY 2027, up $8 billion from July estimates.
Microsoft stock has traded up 23.3% since the April release, outperforming the S&P 500 index. The consensus P/E for 2028 has come down from 27x last July and is now 22x with a consensus target price of $611 and an implied return of 17%.
Alphabet earnings preview
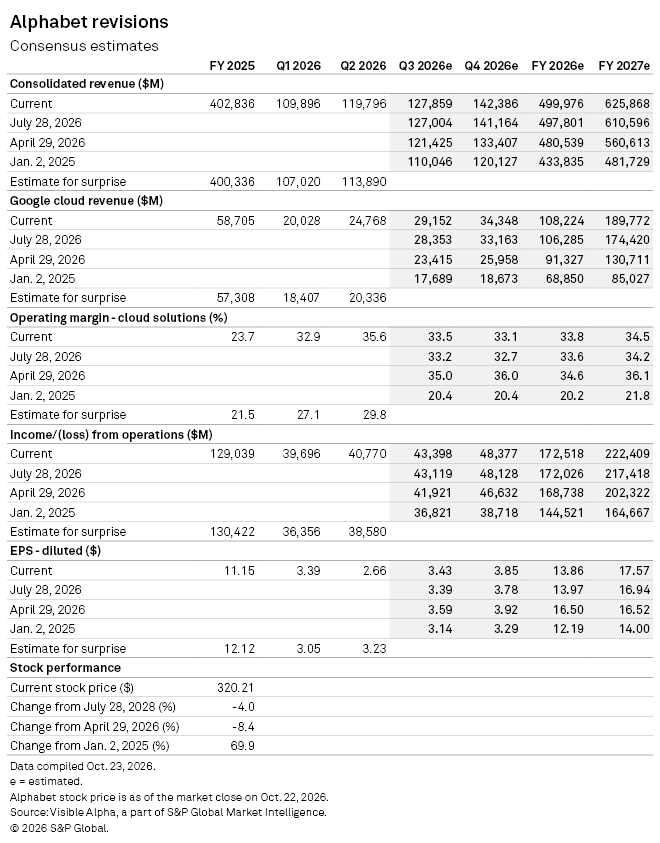
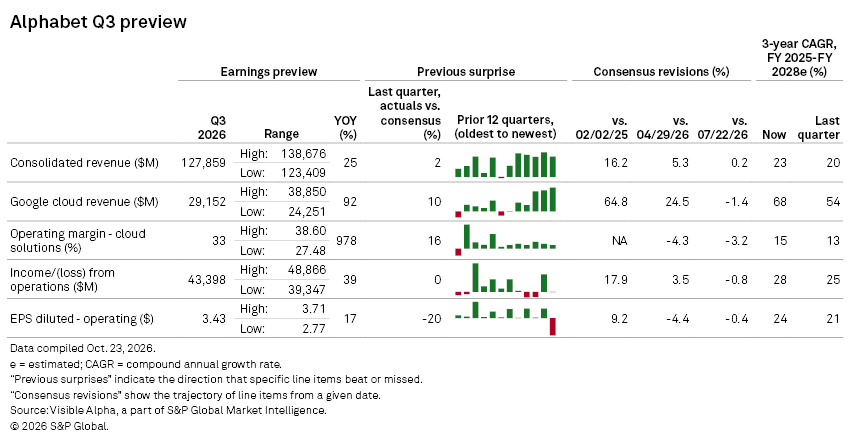
According to Visible Alpha consensus, total revenues expected for Q3 2026 have increased to $127.9 billion from $121.4 billion in April, driven by resilience in its ad business and potential strength in Google Cloud. In contrast, the Q3 consensus expectations for operating income and EPS have been more muted, due to a lower Cloud margin expectation. Since April 2026, the Google Cloud margin has decreased from an expected 35% to now 33.5% in Q3. Since July, the expected Q3 and Q4 cloud margin has increased slightly but has not returned to the levels projected in the spring, driving the consensus EPS expectation for the full year down to $13.86/share. There are differing assumptions around costs, particularly in its Cloud business, leading the Google Cloud margin to range from 27.5% to 38.6%. It will be interesting to assess the overall Cloud segment performance in Q3 and to hear what Alphabet says about the outlook. There is a looming question about whether the Cloud margin has peaked, given the higher cost of Memory and chips.
Next year, analysts are also split in their views. For the Cloud business, Visible Alpha consensus expects the operating profit margin to hit 34.5% in FY 2027 but with a significant range of operating profit estimates. If the core Search and Ads business remains resilient, the performance of Alphabet stock is likely to be driven by the Cloud segment once again. While it seems the cloud margin estimates were too high in April, the market will likely be looking for an indication that consensus has settled at the correct levels.
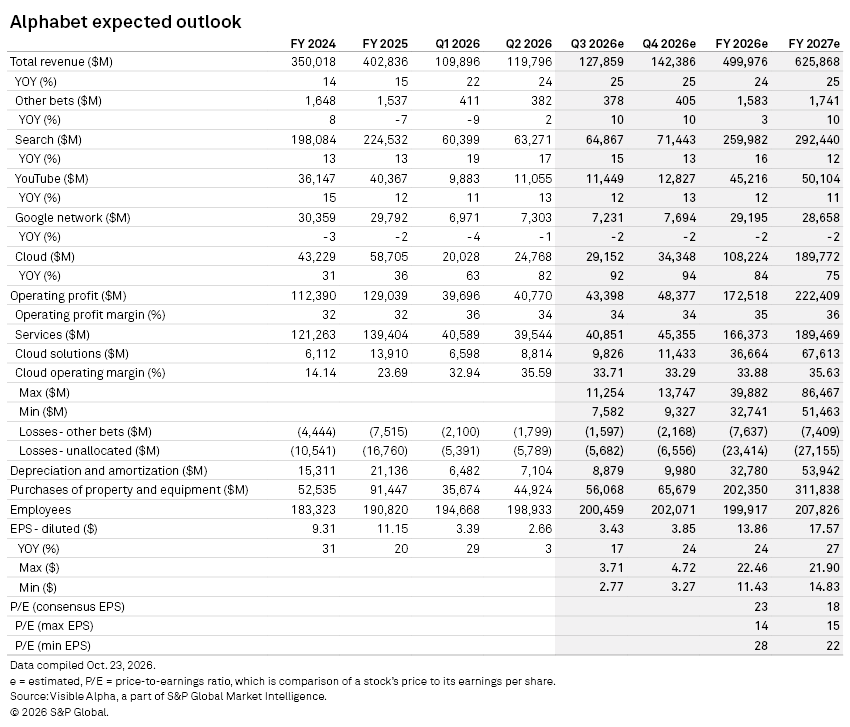
We are closely watching what the company will say about its capex investments for AI infrastructure, as Alphabet's FY 2026 and FY 2027 capex numbers have continued to increase. According to consensus projections, capex estimates have surged over 3x from $91.4 billion in FY 2025 to $311.8 billion in FY 2027. While Alphabet's expected consensus total debt/total equity remains healthy at .35 for FY 2027, the amount of long-term debt is expected to more than double year over year to $100.9 billion in FY 2026 and a further 12% increase in FY 2027 to $112 billion. Last quarter, Alphabet's free cash flow turned negative, causing the market to be critical of the excessive use of cash for AI infrastructure capex without a clear ROIC. Alphabet's negative free cash flow is projected to continue till June 2028.
Alphabet stock has underperformed the S&P 500 this year and, since the April earnings release, is down 7.3%. The consensus P/E for 2027 is 18x with a target price of $427 and an implied return of 32%. Market views seem to be shifting around the Cloud business expectations and the company's projected surging capex. Could the Q3 release provide more visibility into the trajectory for 2027 profitability and give shares a boost?

Visible Alpha is a part of S&P Global Market Intelligence. Full Visible Alpha data is available only via subscription. For more information or to express your interest, please contact your S&P Global Inc. relationship manager.
Copyright © 2026 by S&P Global Market Intelligence, a division of S&P Global Inc. All rights reserved.
The disclosures, disclaimers, and other important legal information applicable to this material are incorporated herein by reference and available at https://www.spglobal.com/market-intelligence/en/legal/disclosures.
Content Type
Products & Offerings
Segment
