ECONOMICS COMMENTARY — 06 Oct, 2026
Global PMI hits joint-highest since 2021 as economic expansion reaches all sectors
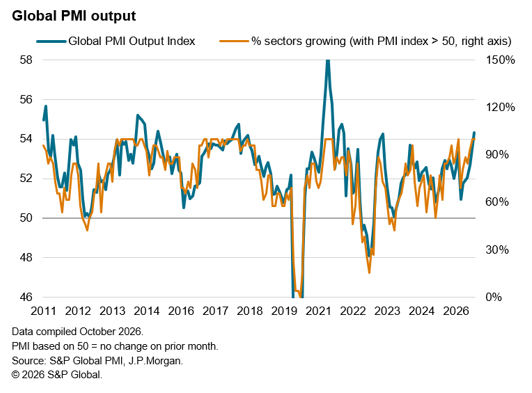
Global economic growth accelerated for a sixth consecutive month in September, with the J.P. Morgan Global Composite PMI rising to its joint-highest since November 2021. The reading is consistent with above-trend annualised global GDP growth of 3.4%. Moreover, the recent survey data signal a broadening out of the global expansion by industry, encompassing all sub-sectors of services and manufacturing worldwide, albeit with the upturn very much led by technology, where the expansion hit the fastest since 2010.
Global PMI at 40-month high
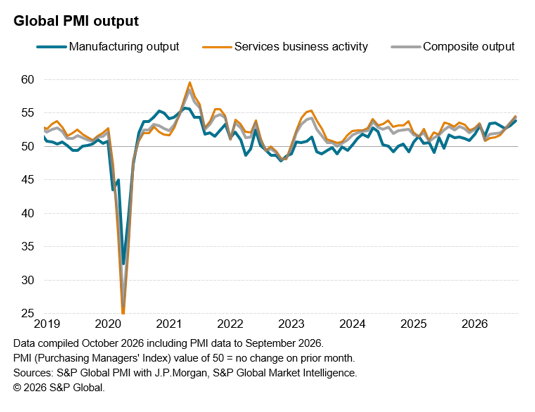
Global business activity growth gained momentum for a sixth straight month in September, signaling the joint-fastest economic growth since November 2021.
The J.P. Morgan Global Composite PMI Output Index, compiled by S&P Global, rose from 53.5 in August to 54.3 in September, matching the prior highs seen in May 2023 and December 2021. Notably, this level has not been exceeded since the post-COVID economic rebound in late 2021.
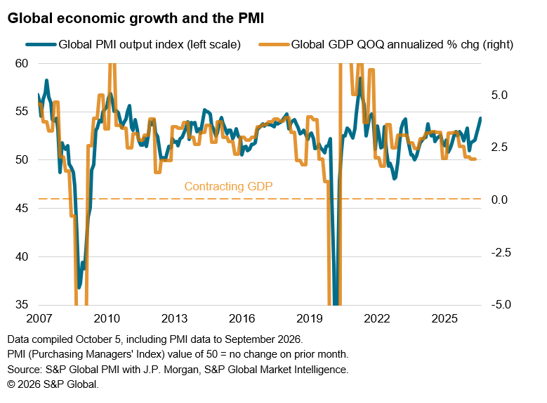
Historical comparisons indicate that the September PMI is broadly indicative of global GDP growth running at an annualised rate of 3.4%, with growth in the third quarter as a whole at 3.0%, above the long-run average.
The survey data therefore point to a marked acceleration of growth since the second quarter, for which official estimates currently point to a modest 1.9% annualised increase in global GDP.
Service sector growth surge accompanied by factory upturn
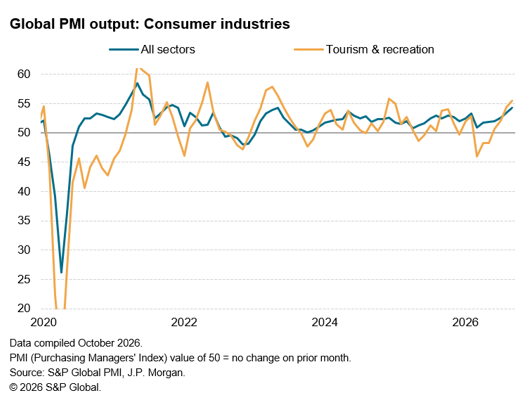
For a second successive month, the global upturn was led by the service sector, where growth accelerated again in September to reach its fastest rate since May 2023. Services growth had slowed sharply at the onset of the war in the Middle East, with activities such as travel and tourism hit hard by both geopolitical uncertainty and the ensuing travel concerns, as well as soaring fuel and transport costs. The recent data therefore point to a recovery in these activities, despite still-elevated oil prices.
However, growth also improved in the manufacturing sector in September, where output rose at the sharpest rate since July 2021 to indicate an increasingly broad-based global economic expansion.
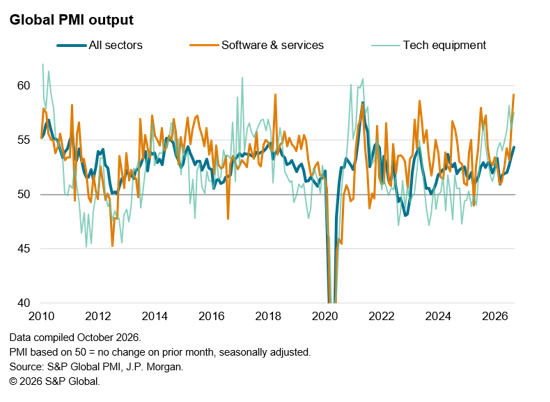
Tech leads the upturn with fastest growth since 2010…
All major industries and sub-sectors reported growth in September, albeit to varying degrees. The strongest expansion was led by technology, where growth surged further to reach its fastest rate since January 2010, with accelerating growth seen in both software & related services (a joint-record high) and tech equipment, which led the sub-sector rankings.
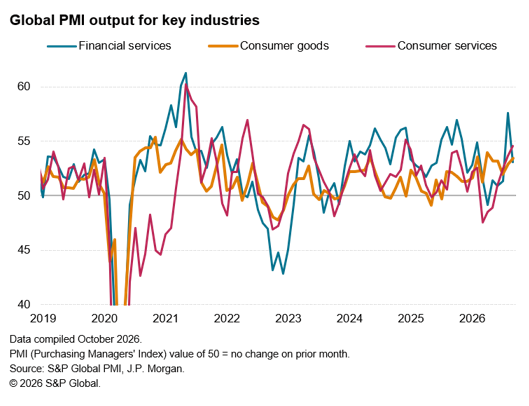
…but all industries report growth
Growth of both consumer services (led by tourism & recreation) and consumer goods also accelerated, contrasting with a slowdown in financial services from a spike in August.
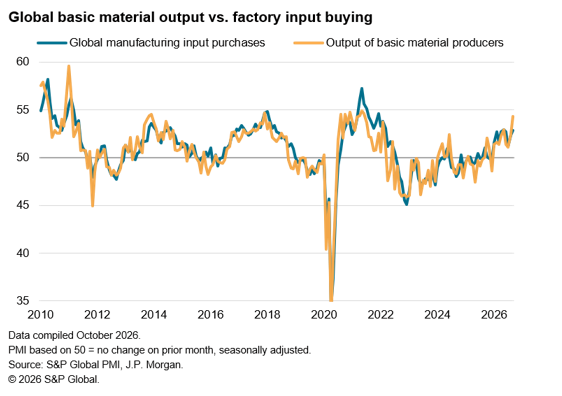
Of note, basic materials, which have lagged in recent months, saw a notable upturn in growth to the fastest rate since June 2021, potentially auguring a further broadening of the global economic upturn to some of the worst-performing economies.
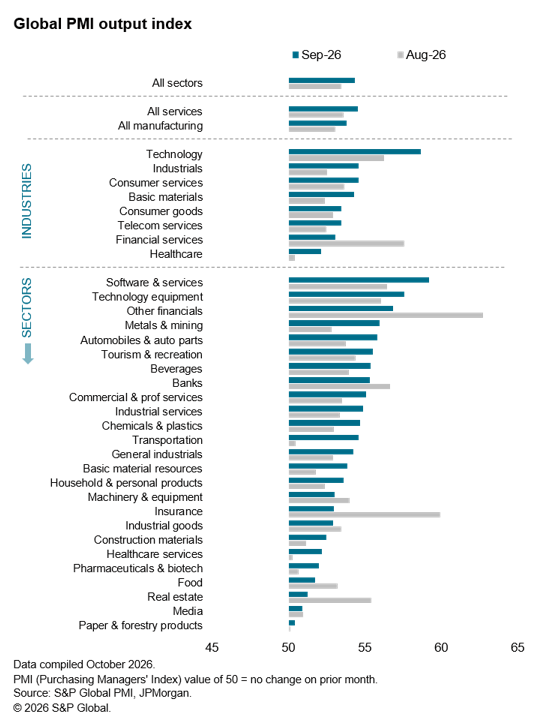
With September seeing 100% of sub-sectors covered by the global PMI reporting output growth, the upturn is more broad-based than at any time since a brief ‘full house’ just prior to the outbreak of war in February. Prior to that, the last time all sectors were in expansion territory was during the post-COVID rebound in 2021, and prior to that such broad-based growth had not been seen since early 2018.
© 2026, S&P Global. All rights reserved. Reproduction in whole or in part without permission is prohibited.
Purchasing Managers' Index™ (PMI®) data are compiled by S&P Global for more than 40 economies worldwide. The monthly data are derived from surveys of senior executives at private sector companies, and are available only via subscription. The PMI dataset features a headline number, which indicates the overall health of an economy, and sub-indices, which provide insights into other key economic drivers such as GDP, inflation, exports, capacity utilization, employment and inventories. The PMI data are used by financial and corporate professionals to better understand where economies and markets are headed, and to uncover opportunities.
Read our latest PMI commentary here.
This article was published by S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Theme
Location
Products & Offerings