ECONOMICS COMMENTARY — 24 Sep, 2026
Japan sees ongoing strong growth and elevated inflation pressures, says September flash PMI
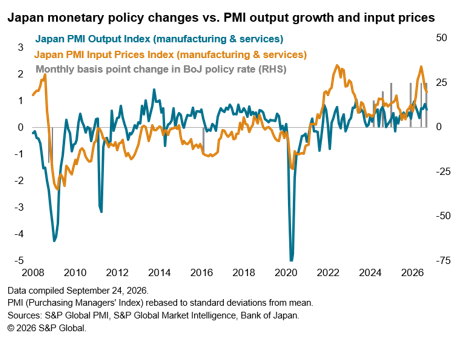
The S&P Global Flash PMI® data indicated a further strong expansion in output across Japan’s private sector in September, with the pace of expansion cooling slightly but remaining among the fastest seen in recent years. Manufacturing growth remained especially impressive amid a sustained export surge, in part linked to the weak yen. However, growth remained marred by supply chain delays, often linked to the war in the Middle East, which added to elevated inflationary pressures. Together, the robust growth and sustained price increases will keep the heat on the Bank of Japan to consider further imminent interest rate hikes.
September data round off fastest quarterly growth since Q1
Japanese business activity continued to grow at a strong pace in September, according to the flash estimates of the S&P Global PMI. The survey’s Composite Output Index fell from 53.5 in August to 52.5 but remained at a level broadly indicative of GDP rising at a quarterly rate of approximately 0.5%. The September figure also rounds off a solid third quarter, which saw the PMI average 52.9, up from 52.0 in the second quarter.
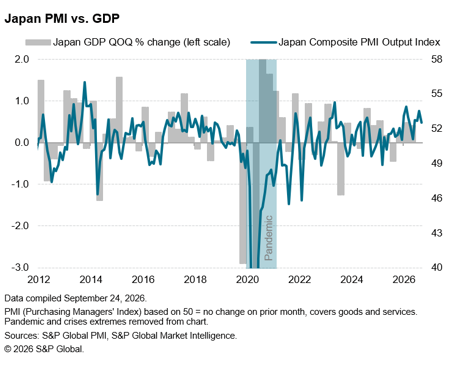
The survey data therefore suggest that the economy has grown robustly again in the third quarter, with growth picking up further momentum from the 0.4% reported for the second quarter.
While the service sector continued to expand in September, its growth rate remained weaker than seen prior to the outbreak of the war in the Middle East, in part linked to falling exports.
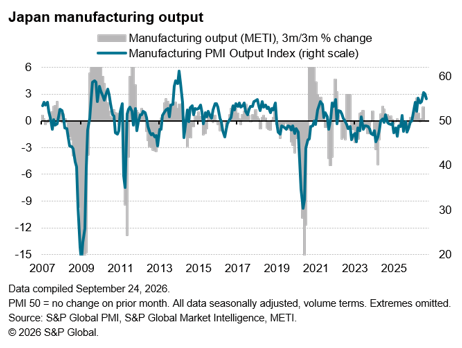
The manufacturing sector therefore remained the main engine of the robust economic performance in September. Although the factory output expansion slowed from the surging pace enjoyed in July and August, it remained the third strongest since early 2014.
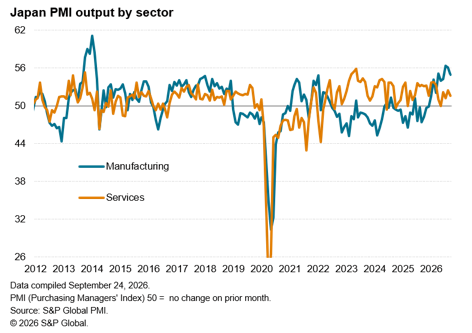
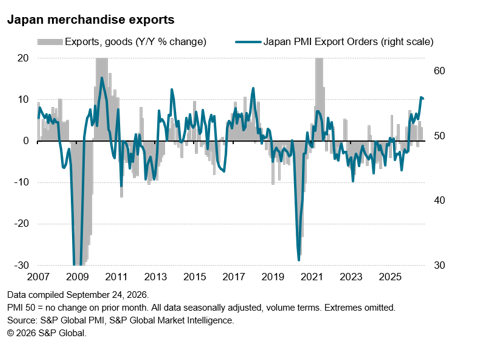
Japan’s factories were again buoyed by the weakened yen, still trading near a four-decade low against the US dollar in September, helping to drive a further marked upturn in goods exports. The past two months have seen some of the largest jumps in new export orders in the PMI survey history.
Additionally, factory order books were again also supported by stock building, as customers sought to build buffer stocks amid ongoing concerns over supply chains and associated price hikes linked to the war in the Middle East.
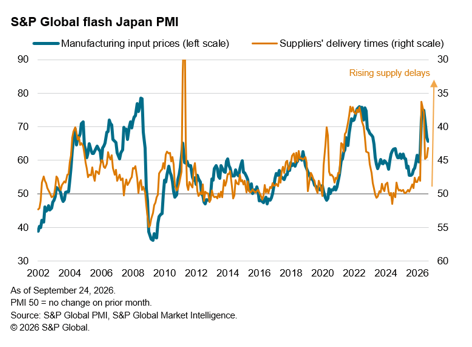
Supplier delivery times lengthened again on average in September, to a lesser degree than seen over the second quarter but more so than in August, thereby remaining more widespread than at any time since 2022.
Factory input costs meanwhile continued to rise at an elevated rate by historical standards, albeit with the rate of inflation easing further from the peak seen in May and June.
Inflation rates hold near record highs
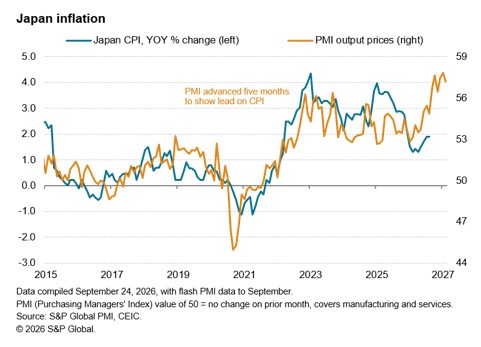
Alongside the ongoing elevated rise in raw material prices, and perhaps of greater concern to policymakers due to their typically stronger relationship with core inflation, charges levied for services also rose at a rate only slightly below the near-record pace seen in July.
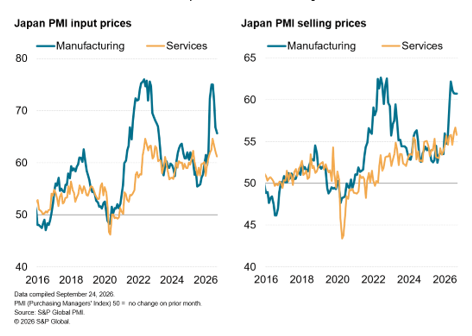
As a result, average prices charged for both goods and services collectively rose at a rate just below August’s all-time high. While some of these increases may have reflected severe weather disruptions, especially in the third quarter, overall price pressures signalling further – potentially marked – upward pressure on consumer price inflation in Japan in the coming months.
Flash PMI hints at more rate hikes
The August flash PMI follows the latest decision by the Bank of Japan to raise the policy rate to 1.25%, the highest since 1995, continuing a tightening cycle that began in early 2024. The decision followed an increase in consumer price inflation to 1.9%, drawing closer to the bank’s 2% target. The sustained upward price pressures seen in the PMI survey, alongside the improving growth picture, suggest another rate rise could soon be on the cards, potentially as soon as October. Market reaction shortly after the release of the flash PMI data showed the Japanese yen strengthening slightly against the greenback as prices looked past the slower growth picture to the still elevated inflation pressure on interest rates.
© 2026, S&P Global. All rights reserved. Reproduction in whole or in part without permission is prohibited.
Purchasing Managers' Index™ (PMI®) data are compiled by S&P Global for more than 40 economies worldwide. The monthly data are derived from surveys of senior executives at private sector companies, and are available only via subscription. The PMI dataset features a headline number, which indicates the overall health of an economy, and sub-indices, which provide insights into other key economic drivers such as GDP, inflation, exports, capacity utilization, employment and inventories. The PMI data are used by financial and corporate professionals to better understand where economies and markets are headed, and to uncover opportunities.
Read our latest PMI commentary here.
This article was published by S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Theme
Location
Products & Offerings