Research — November 18, 2026
Walmart earnings preview: Q3 2027
Walmart Inc. (NASDAQ: WMT) is set to report its fiscal third-quarter 2027 financial results on Thursday, Nov 19. Based on Visible Alpha consensus, analysts expect the retailer to deliver another quarter of steady revenue growth, with consensus forecasting Q3 FY 2027 revenue of $187.3 billion, up 4.3% year-over-year. Consensus revenue estimates range from $185.6 billion to $188.9 billion.
Diluted operating EPS is estimated at $0.64, with consensus ranging from $0.61 to $0.66, marking a 2.6% increase from Q3 2025. The prior quarter saw a 9.5% positive surprise on EPS, and consensus revisions for key line items have been modest since August 2026. The three-year compound annual growth rate for total revenue is projected at 4.9%, with EPS CAGR at 11.1%.
While revenue expectations remain relatively stable, earnings estimates have shown signs of recovery more recently. Operating EPS consensus has increased 0.9% since Walmart's Q2 earnings on August 20, partially reversing downward revisions of 6% since its Q1 results on May 21 and 9% since the start of the year.
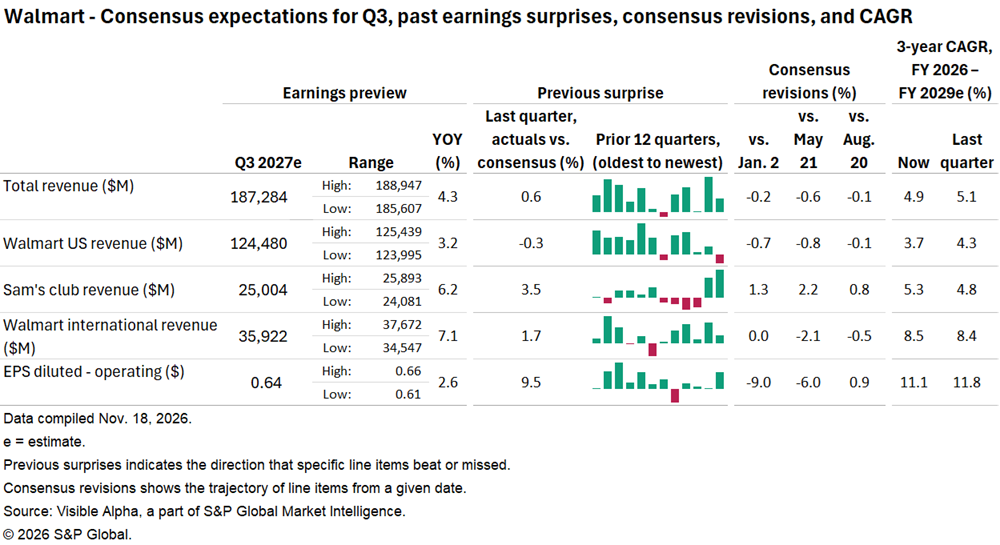
Q3 growth is expected to be led by Walmart International and Sam's Club, although the domestic business will remain the largest contributor to group sales.
International operations are expected to contribute $35.9 billion, up 7.1% year-over-year, buoyed by a 16.4% growth in sales at Flipkart, Walmart’s Indian e-commerce platform.
However, the timing of Flipkart’s flagship Big Billion Days shopping event is expected to distort the quarterly comparison. Unlike last year, when nine days of the promotion fell in Q3 and two in Q4, the 2026 event shifted almost entirely into Q4. Walmart flagged a headwind of more than 100 basis points to Q3 sales growth in its August results, with a corresponding benefit expected in Q4.
Sam’s Club, the group’s warehouse chain, is forecast to deliver $25 billion in revenue, a 6.2% increase from Q3 2026, with comparable sales growth accelerating to 5.92% from 2.60% a year ago.
Walmart’s US operations, which account for the bulk of group sales, are expected to generate $124.5 billion in revenue, up 3.2% from a year earlier. However, the segment’s comparable sales growth is projected to slow to 2.82%, down from 4.50% in the prior year.
Overall, group comparable sales growth, including fuel, is projected at 3.27% for the quarter, down from 4.50% in Q3 2026.
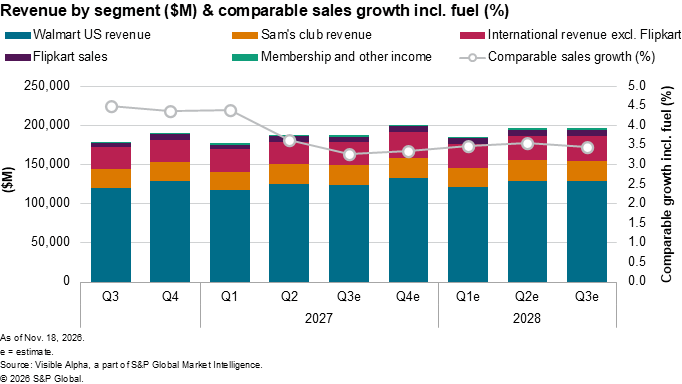
E-commerce remains a bright spot, with online sales forecast to reach $47.08 billion, up 21.8% from the previous year. E-commerce sales grew 23% in Q2, while the company has highlighted improving fulfilment economics and the contribution of marketplace and store-based delivery.
Advertising and membership income are also expected to expand higher-margin revenue streams. Walmart’s advertising business is expected to grow 25% year-over-year to $1.98 billion in Q3, while membership and other income rise by an estimated 8.2% to $1.87 billion.
The physical footprint is expected to expand to 11,029 from 10,822 a year earlier.
Important notice
Any views not otherwise cited are based on Visible Alpha data and a compilation of the corresponding broker research reports.
Usage of this product is governed by the S&P Global Market Intelligence Agreement, as applicable.
Privacy Policy and Cookie Notice Terms of Use Legal Disclaimer Third Party Disclaimer
Site content and design Copyright © 2026, S&P Global Market Intelligence
This article was published by Visible Alpha, part of S&P Global Market Intelligence, and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Content Type
Products & Offerings
Segment

