Research — SEPTEMBER 21, 2026
Civitas acquisition, oil rally boost SM Energy's 2026 revenue outlook
By Simran Dua
US shale producer SM Energy Co. (NYSE: SM) is poised for a step change in 2026 following its all-stock acquisition of Civitas Resources Inc. in January. The deal, which reshaped SM Energy's asset base, positions the Denver- and Houston-focused group to benefit from increased scale in the Permian Basin and Denver-Julesburg Basin, two of the most prolific oil and liquid-rich gas regions in the US.
SM Energy, which produces crude oil, natural gas and natural gas liquids primarily from Texas and Utah, gained significant exposure to the Permian, where rivals such as ExxonMobil Holdings Corp. and Chevron Corp. have also expanded their presence.
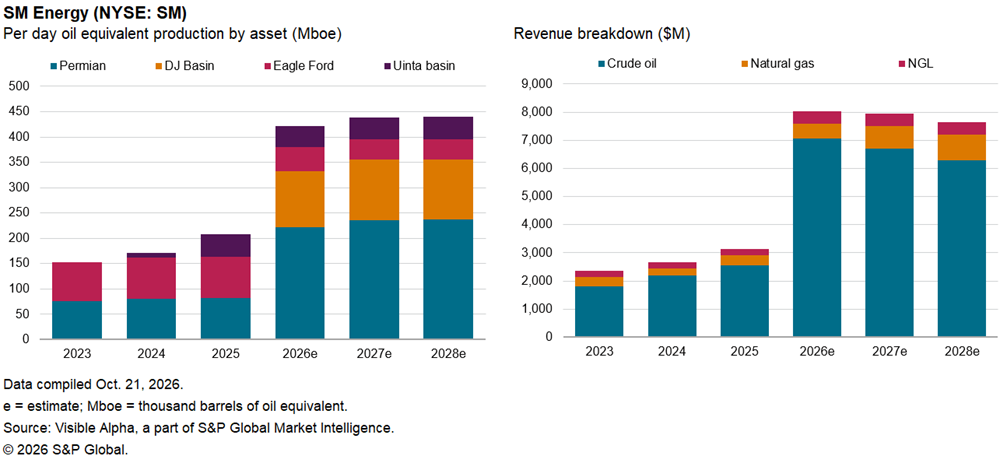
SM Energy's total oil-equivalent production is expected to jump 104% year over year to 422,000 barrels of oil equivalent per day in 2026, up from 207,000 boe/d in 2025. Output from the Permian Basin alone is projected to surge 169% to 222,000 boe/d, making it the company's largest asset and accounting for about 53% of total daily production. The Denver-Julesburg Basin portfolio, acquired from Civitas, is expected to contribute about 110,000 boe/d in 2026, or about 26% of the combined group's output, further diversifying SM Energy's production mix.
The production uplift is set to flow through to the top line, with higher commodity prices providing an additional tailwind. Consensus estimates point to total operating revenue rising 152% year over year to about $8 billion in 2026. Crude oil remains the principal revenue driver, with oil revenue projected to increase 176% to $7.1 billion. NGL revenue is expected to rise 102% to $453 million, while natural gas revenue is projected to increase 44% to $510 million. The magnitude of the revenue increase is principally about acquisition and volume, reinforced by firmer oil prices, with Brent crude trading above $80/barrel for much of 2026, which supports sector profitability.
The stronger top-line outlook is expected to result in higher profitability. EBITDA is projected to increase 121% to $4.9 billion in 2026, while net income is projected to rise 160% to $1.7 billion. Diluted EPS is projected to increase 29% to $7.29, reflecting the impact of the larger share base after the Civitas transaction.
This article was published by Visible Alpha, part of S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Content Type
Products & Offerings
Segment
