Research — SEPTEMBER 23, 2026
Nike heads into Q1 2027 results with sales still under pressure
By Shlok Jain and Cristalina Pinto
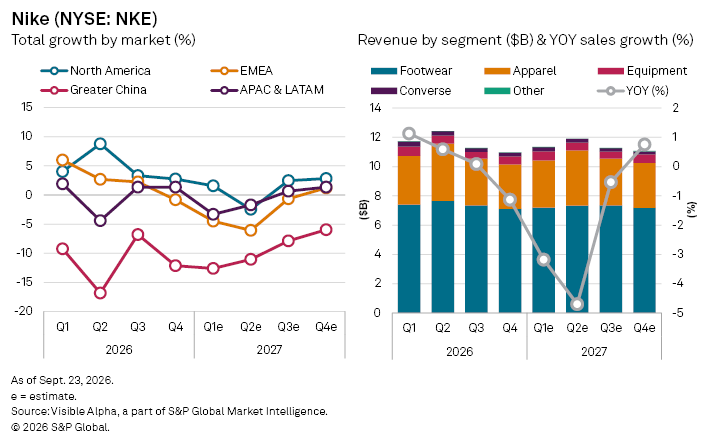
Nike Inc. (NYSE: NKE) is set to report first-quarter fiscal 2027 results on Thursday, October 1, with Visible Alpha consensus pointing to another quarter of declining sales as CEO Elliott Hill’s “Win Now” turnaround continues to work through the business. Analysts expect revenue of $11.3 billion in Q1, down 3.2% year-on-year, as weakness in Greater China and Europe, Middle East and Africa offsets modest growth in North America.
Nike’s shares have fallen about 43% year-to-date and 49% over the past year, leaving the company with a market capitalization of roughly $54 billion at the September 21 close.
Nike’s declining market standing was reflected this month when S&P Dow Jones Indices removed the company from the S&P 100, effective September 21, ending its nearly 18-year tenure in the index.
The biggest regional concern remains Greater China, where revenue is forecast to fall 12.6% to $1.3 billion. Analysts have also materially reduced their fiscal 2027 sales expectations for the region.
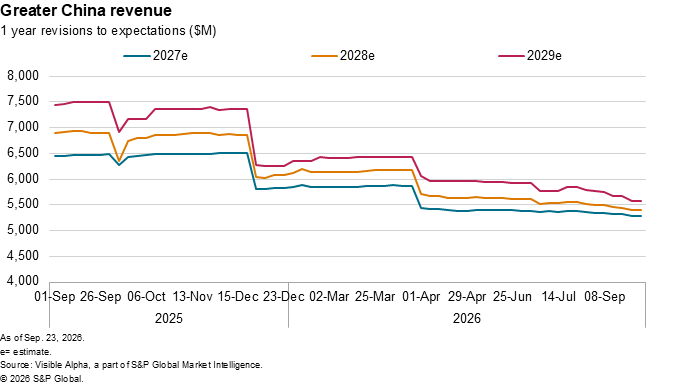
Nike has been restructuring its distribution model in China and is moving to a more tightly controlled digital marketplace. From January, key wholesale partners are expected to stop selling Nike products online, with the company concentrating its digital sales through its own website, app and branded stores on platforms including Tmall, JD.com Inc. and Douyin Ltd.. The move is intended to improve brand presentation and reduce the fragmentation of Nike’s online marketplace, but could weigh on sales in the near term.
Competition is adding to the pressure. Chinese sportswear groups such as Anta Sports and Li Ning Co. Ltd. have been gaining ground as Nike contends with weaker consumer demand and a need for more locally relevant products. Nike’s China revenue has declined for several consecutive quarters, making the region a key test of whether Hill’s broader product and marketplace reset can restore growth.
Elsewhere, the recovery is expected to remain uneven. North American revenue is forecast to rise 2% to $5.1 billion in Q1, while sales in Europe, Middle East and Africa are expected to fall 4% to $3.2 billion and Asia-Pacific and Latin America to decline 3% to $1.4 billion.
By category, footwear, which accounts for nearly two-thirds of Nike’s revenue, is expected to decline 3% to $7.2 billion in Q1. Apparel is forecast to fall 2% to $3.2 billion and equipment 4% to $604 million. Converse remains a particularly weak spot, with revenue forecast to drop 19% to $296 million.
The channel mix also points to an uneven recovery. Wholesale revenue is expected to fall 1% to $6.8 billion, while Nike Direct-to-Consumer (DTC) is forecast to decline 4% to $4.4 billion. Within DTC, analysts expect an 8% decline in sales from Nike-owned stores and a 1% decline in digital sales.
The quarter will also mark an early test for new CFO David Denton, who joined Nike in August after Matthew Friend stepped down. Denton is taking over as Nike seeks to improve profitability and execute its turnaround, making the company’s November 16–17 Investor Day particularly important for investors looking for greater visibility on the path back to revenue growth and margin recovery. Nike has said it plans to resume full-year and long-term guidance at the event. Denton previously served as CFO at Pfizer and Lowe’s.
This article was published by Visible Alpha, part of S&P Global Market Intelligence and not by S&P Global Ratings, which is a separately managed division of S&P Global.
Content Type
Products & Offerings
Segment
