28 Sep, 2026
Investors sour on energy IPOs amid interest rate, data center, credit risks
By Allison Good
|
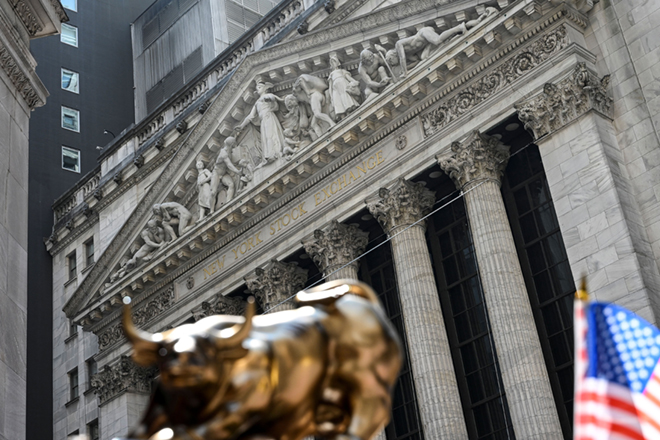
The New York Stock Exchange, above. A recent wave of data center demand-driven energy IPOs has stalled amid "new questions about how stable" the industry is, Matthew Kennedy, a senior strategist at Renaissance Capital, said. |
Wall Street's appetite for power sector initial public offerings is waning as rising interest rates, negative sentiment toward data center development and counterparty credit risk weigh on investors.
US nuclear vendor Holtec International, which plans to license and deploy its SMR-300 advanced small modular reactor, in mid-September postponed a proposed $100 million initial public offering amid a sectorwide selloff of stock in SMR developers. The company in its Sept. 17 announcement cited data center development uncertainty, rising energy costs, ongoing military conflicts and global trade tensions, and swiftly rising interest rates all weighing industry share prices.
Days later, reports emerged that SoftBank Group Corp.'s SB Energy Corp., which filed a registration statement for a proposed IPO on Sept. 1, was struggling to find buyers for its targeted $50 billion valuation and had delayed the public offering to October.
Bloomberg reported that the solar-plus-storage and gas generation developer plans to start marketing its IPO once the SEC completes its review of the filing, but industry experts agreed that a recent wave of enthusiasm that saw geothermal developer Fervo Energy Co., SMR developer X-Energy Inc. and power infrastructure services provider SOLV Energy Inc. begin trading on public markets during the first half of 2026 has subsided.
"Not long ago, virtually anything in the AI value chain could get funded, no problem," Matthew Kennedy, a senior strategist at IPO-focused research and exchange-traded funds provider Renaissance Capital, said in an interview. "The billions are still pouring in, but there are new questions about how stable that is."
Share prices of Fervo, X-Energy and SOLV declined 72%, 27% and 35%, respectively, in the last three months to the Sept. 25 market close, even though Fervo and SOLV have firm contracts to service and supply data centers and X-Energy is in the final stages of an agreement with a major investor-owned utility for a 1-gigawatt project to power AI infrastructure.
"One hundred billion dollars in contracted revenue doesn't look as good as inflation starts to rise," Kennedy noted.
Stabilizing rates could help turn the tide on investor sentiment, but "the fact we have another rate hike on the horizon makes it trickier to understand where we're going," he added.
The Federal Reserve's Federal Open Market Committee voted Sept. 16 to increase its benchmark federal funds rate by 25 basis points to a range of 3.75% to 4%, its first increase in more than three years, and indicated there may be another increase before the end of 2026.
The prospect that Democrats may retake the US House and Senate in 2027, plus mounting political and environmental opposition to data centers across the country, also make it "harder to underwrite longer-dated stories" that may not see stable cash flows in the immediate future, Chris Dendrinos, vice president of equity research at RBC Capital Markets, said in an interview.
Additionally, "the investor base wants to see a broad spectrum of customer demand not concentrated into any one hyperscaler," he emphasized.
Credit risks
Hyperscalers' credit quality is "gradually weakening," analysts at S&P Global Ratings wrote in a Sept. 3 report. "Every time we take a deep dive into this sector, we find that capex is rising faster than we anticipated, financings are becoming more complicated and less transparent, and that returns on investment will take years to realize."
"An emerging web of interconnected financings is supporting demand, and not just raw end-market economics," Ratings analysts continued. "It also increases the chances that the failure of an unrated entity could dent the credit standing of a highly rated firm."
Chipmaker NVIDIA Corp., for one, recently disclosed that it bought an additional $1.5 billion in SB Energy shares, bringing its total investment to $3 billion.
NVIDIA is also providing a $105 billion residual value guarantee to help fund SB Energy's planned $500 billion data center campus in Ohio, where OpenAI LLC will be the primary tenant, enabling SB to "borrow against the assets" without a public credit rating, according to Ratings.
American Electric Power Co. Inc. subsidiary Ohio Power Co., which will build 10 GW of new power generation and new high-voltage electric transmission infrastructure for the data center campus, could ultimately be left with stranded assets if NVIDIA's credit is compromised, Neil Kalton, co-founder and principal at AK Capital Consulting, said in an interview.
"If OpenAI defaults and no other hyperscaler comes in, and then NVIDIA ends up defaulting … my understanding is that the risk would be that [AEP Ohio] would have to go back their regulators and ask to recover the investment and the return from the rest of their customer base," Kalton said.
NVIDIA's additional investment in SB Energy, he continued, "is cash out the door."
Oracle Corp., whose long-term issuer credit rating S&P Global downgraded in June to BBB- from BBB, the lowest tier of investment-grade debt, sued the Public Service Commission of Wisconsin that month over the regulator's requirement that major data center developers maintain a minimum A- credit rating or provide a financial guarantee.
The commission included the security requirement in WEC Energy Group Inc. subsidiary Wisconsin Electric Power Co.'s new "very large customer" rate structure — which is designed to protect ratepayers from the financial risks associated with infrastructure upgrades needed to bring data centers or other large projects online — for the 1-GW Stargate project in Port Washington, Wisconsin.
Regardless of the lawsuit's outcome, the $15 billion project is still a go, WEC Energy CEO Scott Lauber told analysts and investors in July.
"Oracle has stated it remains committed to the project, paying its full share of energy and providing the financial support needed, so there's no risk to other Wisconsin customers," Lauber said during the company's second-quarter earnings call. "We are actively working with Oracle to update the financial security in line with the [Public Service Commission of Wisconsin] requirements."
Unlike NVIDIA's residual value guarantee for SB Energy, Oracle would make WEC whole if, for some reason, the project fails, AK Capital's Kalton said.
"It's up to these utilities to make sure that with these contracts and the risks that they have, they're not leaving their customers exposed," he said.