19 Oct, 2026
SocGen opens up to M&A as growth comes back on agenda
| Commercial and investment banking is seen as one of the most likely areas SocGen will aim to grow through M&A. Source: Anadolou via Getty Images Europe. |
Société Générale SA looks set to return to the M&A market as a significant buyer in the coming years as it chases growth targets and tries to close the gap to European peers.
The French banking giant has been a bystander amid a stream of large-scale European banking M&A moves since 2024.
SocGen is now more open to considering M&A as part of its growth plans, CEO Slawomir Krupa said during the bank's presentation of its latest three-year strategy in September. Among the businesses the Paris-based bank could look to boost through M&A are its investment bank's fixed income and equities units, while moves into adjacent geographies, products or client segments could be entertained for other businesses, said Krupa.
"If SocGen wants to compete with the largest European banks, it will likely need to grow and further diversify its business mix," Sonja Forster, vice president, financial institutions at Morningstar DBRS, said in an email.
SocGen's profitability and valuation
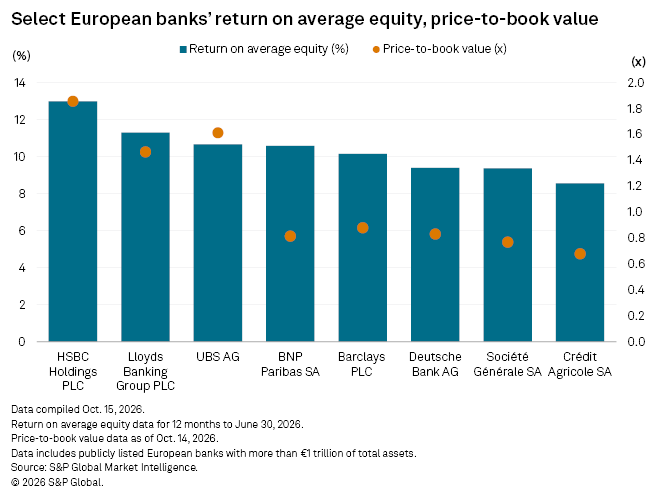
The bank's return on average equity — a measure of profitability — for the 12 months to June was 9.38%, the second-lowest among the 10 publicly-listed European banks with assets of more than €1 trillion. Its share price traded at 0.77x book value as of Oct.14, also the second-lowest among the sample, the data shows.
SocGen's new three-year plan targets a return on tangible equity — a key measure of bank profitability that excludes goodwill and other intangible assets — of between 13% and 14% by 2029, advancing to more than 15% in 2030 and beyond.
Achieving these gains will require significant change at the bank in the coming years, Nuria Álvarez, bank equity analyst at Madrid-based Renta4Banco, said in an email.
"Any global bank looking to quickly boost its profitability needs to pursue some sort of corporate action," said Álvarez, who covers Spanish, French and Italian lenders.
Priority areas
Acquisitions in SocGen's corporate and institutional banking (CIB) division
The CIB's prime brokerage business, which offers services like financing, securities lending, trade execution and clearing to hedge funds and other institutional investors, is also a candidate for growth through M&A. Prime brokerage "will be a key priority" as hedge funds and asset managers account for a "substantially lower" share of SocGen's client mix than the industry average, presenting "significant potential to scale our presence in this segment," said Krupa.
"If there were acquisitions, we would expect them [in the CIB]," Johann Scholtz, bank equity analyst at Morningstar DBRS, said in an email. "Especially where they think they have gaps in their product or coverage."
A more surprising M&A target for SocGen could be Spanish lender Banco de Sabadell SA. Krupa suggested that Spain's fourth-largest bank by assets
Still, Sabadell's share price would need to be "a little bit cheaper" for SocGen to consider a move, Krupa added. Sabadell has traded at 1.42x its book value in the last 12 months compared to an average of 1.97x for its three larger Spanish peers and 0.78x for SocGen, Market Intelligence data shows.
While some analysts told Market Intelligence that they disregarded the comments due to Krupa's seemingly light-hearted delivery — SocGen did not respond to requests for clarification — others see the appeal of the move.
"This would be a highly complementary addition to their business model, significantly supporting their profitability improvement targets," said Álvarez of Renta4Banco.
Retail banking in Spain tends to be more profitable than in France due to a higher proportion of variable-rate lending, lower deposit costs due to an absence of regulated savings accounts and lower costs due to smaller branch networks.
Any move for Sabadell by SocGen would extend a recent trend among French banks for retail banking acquisitions in other markets, including Groupe BPCE's purchase of a 7% stake in Sabadell just two weeks after Krupa's comments. SocGen already operates retail banks in Czechia, Romania and several African countries. (13)
Still, the purchase of a retail bank in a market where SocGen is not present would raise questions.
"I don’t see significant synergies as SocGen doesn't operate a sizeable retail franchise in Spain," Gilles de Bourrousse, senior fixed income analyst, financials at Paris-baed Octo Finances, said in an email.
|
Alternative options
SocGen is also setting the bar high for any M&A deal. Acquisitions must be a "compelling strategic fit, reinforce one of our core franchises and be consistent with our risk appetite," said Krupa. Moreover, SocGen does not need M&A to deliver on its targets for 2029 and beyond, he added.
The bank may consider share buybacks, which would boost the bank's stock, a more attractive option than M&A due to its low price-to-book multiple, said Scholtz of Morningstar DBRS.
SocGen's last major M&A deal was the purchase of European auto-leasing giant LeasePlan for €4.9 billion in 2022.
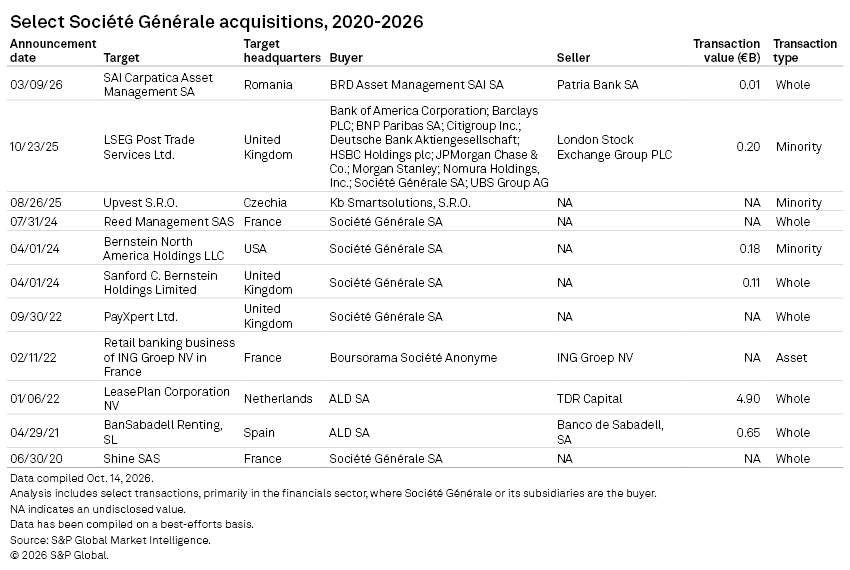
French peers BNP Paribas SA and Crédit Agricole SA have been among the European lenders engaged in large-scale M&A since then. BNP completed its acquisition of AXA Investment Managers SA for €5.1 billion in 2025, while CredAg is reportedly considering a joint bid with UniCredit SpA for Italy's Banco BPM SpA after building an almost 30% stake in the sought-after lender.
While CredAg already has a presence in Italy, long-standing reluctance among SocGen and other European banks to consider cross-border deals
"AI could make cross-border bank mergers more attractive over time," she said. "It may allow banks to simplify and harmonize their technology stacks much more quickly, potentially making integration easier and increasing the attractiveness of cross-border consolidation."