17 Sep, 2026
Florida gains push P&C insurers to profit peak - S&P webinar

➤ Underwriting gains across the property and casualty industry have reached unprecedented levels in recent quarters, with Florida homeowners insurers leading the profitability surge.
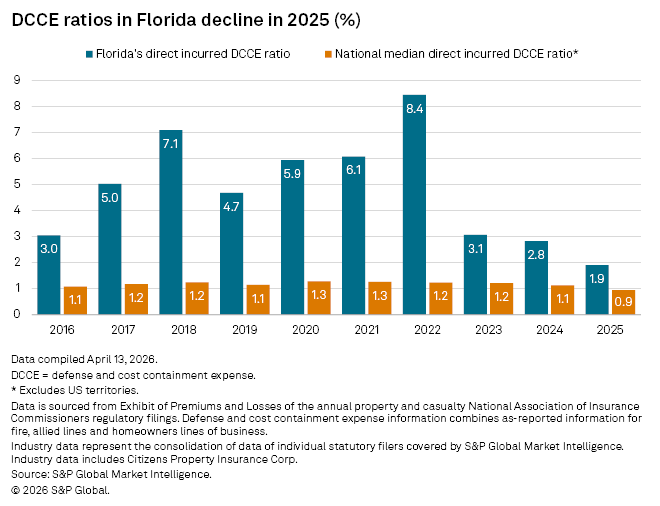
➤ Florida's tort reform legislation dramatically reduced litigation costs, with defense costs as a percentage of earned premium dropping by at least 5 percentage points from 2022 highs.
➤ The absence of major hurricanes, combined with tort reform, has transformed Florida into a top performer for P&C insurers.
Property and casualty insurers are experiencing "generational" profitability highs, with underwriting gains reaching unprecedented levels in recent quarters, according to experts who spoke during a recent S&P Global Market Intelligence webinar.
"P&C profitability is at generational highs," said Chris Winter, associate director, insurance, at Market Intelligence. "That's the lens we should use to talk about the performance ranking of the top performance companies," he said.
Six of the past seven quarters have produced the US P&C industry's best-performing underwriting periods, according to Market Intelligence data. There was $15.99 billion in underwriting gains recorded in the second quarter of 2026, and $21.98 billion in the prior quarter.
Florida homeowners insurance drives performance
The dramatic turnaround in Florida's homeowners insurance market has largely driven the gains, the experts said during the Sept. 16 "2026 Top P&C Insurance Company Performance Rankings" webinar.
The top three companies in the annual ranking — Florida Peninsula Holdings LLC, Frontline Insurance Group and Slide Insurance Holdings Inc. — are specialized homeowners writers in Florida.
Access a replay of the webinar.
"[Florida] was a good area to be in, at least for last year. There were no major hurricanes last year. And there's also been a lot of tort reform ... which has helped these companies as well in their profitability," Terry Leone, manager at Market Intelligence's financial institutions research, insurance, team, pointed out during the webinar.
The defense and cost containment expense (DCCE) ratio for Florida was 7.1% 10 years ago, Market Intelligence data shows, and climbed to a decade-high of 8.4% in 2022. But for 2025, the ratio declined significantly to just 1.9%.
"There's no question there has been fundamental reforms in the Florida marketplace as a result of actions taken by the Florida legislature, primarily in their special sessions in 2021 and where they address specifically the one-way attorney fees," Kevin McCarty, manager and founder at Celtic Global Consulting, said.
However, McCarty, a former Florida Insurance Commissioner, emphasized that the reforms extended beyond legal fee structures.
"One should not mistake that this is just the one-way attorney fees. There has been a culture building in Florida with, one would say, less than scrupulous public adjusters, attorneys and builders and roofers," he said, describing how assignment of benefits issues had enabled small projects to balloon into massive claims. "So we're not looking at just the cost of defense, but the behavioral change that we're seeing in Florida," McCarty said.
The Florida success story has contributed to broader industry profitability gains. The P&C industry is now approaching $8 trillion in total cash and invested assets, with continued growth expected in the coming quarters. Rate increases have significantly boosted premium collections across the industry.
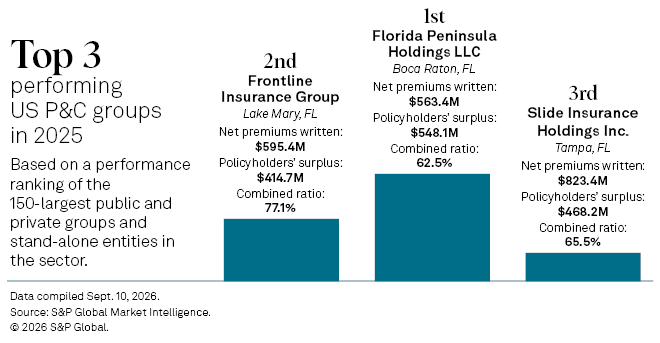
Beyond the Florida homeowners writers, several mortgage insurers also appeared among the top performers, reflecting strong results in that specialized sector.
This high-profitability environment has created significant strategic opportunities for P&C insurers. Companies now have greater flexibility in portfolio management decisions and rate-setting strategies, and their strong capital positions, resulting from sustained underwriting profits, allow insurers to take a longer-term view on competitive positioning.
Looking ahead with optimism
Looking ahead, both mortgage insurance and Florida property insurance executives expressed optimism about continued improvements in their respective markets.
Nathan Colson, executive vice president, CFO and Chief Risk Officer at MGIC Investment Corp. and MGIC, said technology and data analytics are likely to drive further improvements in the mortgage insurance industry.
"I think what we've done as an industry over the last, I think, five to seven years, [is] getting more sophisticated on pricing individual risk, how we think about capital, much more efficient with how we manage capital. Those are all directionally things that have been really favorable for the industry. And I'm sure that there's more to go there," he said.
He also emphasized the potential for artificial intelligence to transform the broader mortgage origination process.
"The mortgage industry more broadly has been focused on efficiency. It's still expensive to manufacture a loan. How can AI potentially enable us to be much more efficient at how we do business?" he said.
Disclaimer: This content may be AI-assisted and is composed, reviewed, edited and approved by a human at S&P Global. S&P Global uses generative AI to create content in accordance with our Terms of Use.
|