
IN THIS LIST

2023 SPIVA Institutional Scorecard: SMAs/Wrap Accounts Are Here!

Fees and Fortunes

Size, Momentum and Value

Drill Baby Drill: Commodity Performance in U.S. Election Years

Back to the Future

2023 SPIVA Institutional Scorecard: SMAs/Wrap Accounts Are Here!

First published in 2002, the S&P Indices versus Active (SPIVA®) U.S. Scorecard measures the performance of active mutual fund managers against their respective S&P DJI benchmarks over various time horizons and across asset classes. In 2015, we extended the analysis to include institutional accounts to understand how institutional asset owners fared versus mutual funds against their respective benchmarks and the impact of fees on performance.

In our 2023 edition, we have further expanded our purview of assessing active manager performance to now include separately managed accounts (SMAs)/wrap accounts. SMAs may offer potential benefits such as increased customization, greater transparency and direct ownership of securities in a portfolio. With the addition of these accounts, we can examine the performance of professionally managed portfolios held by retail investors against their respective benchmarks.

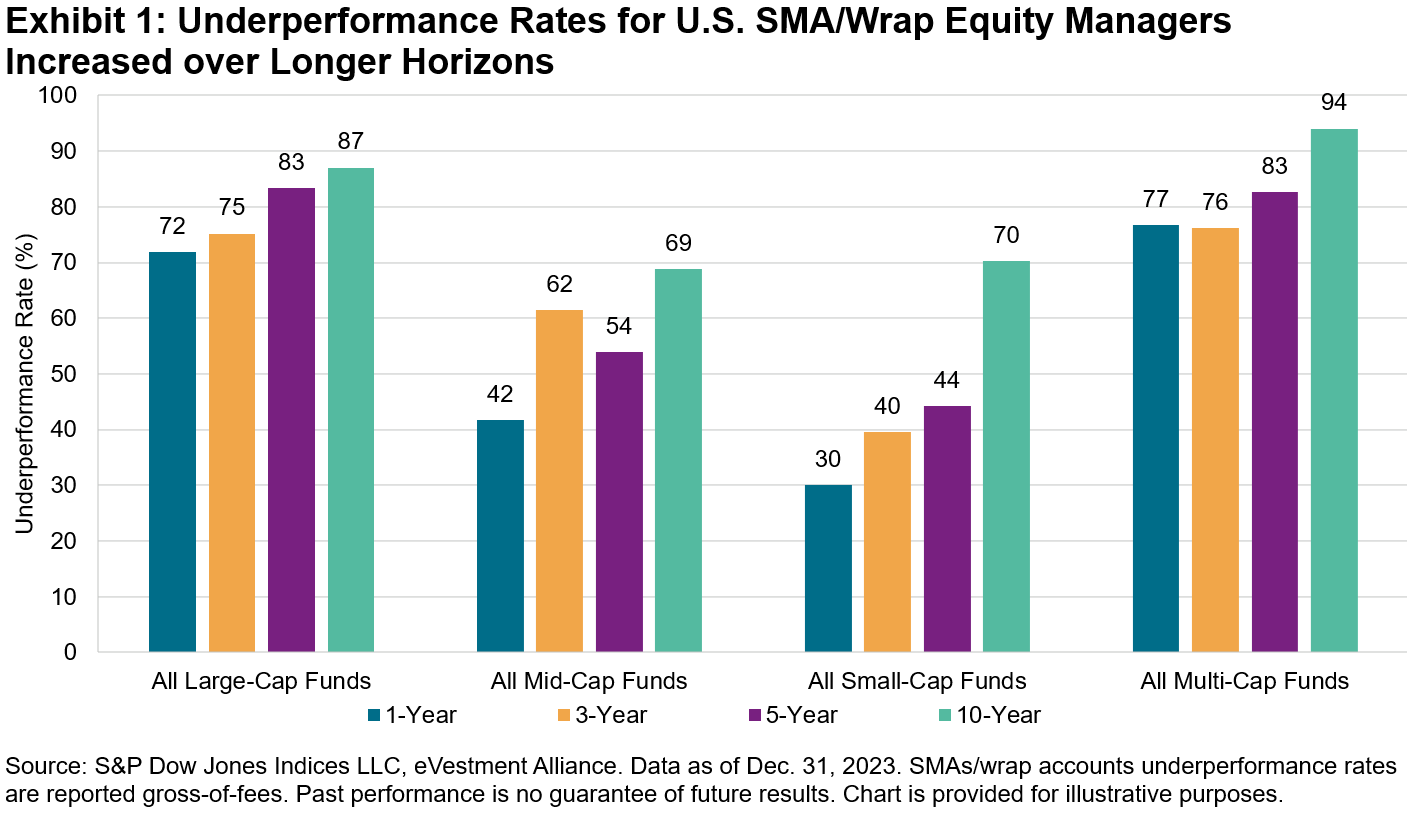
Our reported SMA/wrap categories span across equities and fixed income. In 2023, in our most closely watched category of All Large-Cap Funds, 72% of SMA/wrap managers underperformed the S&P 500® on a gross-of-fees basis, lagging their institutional account and mutual fund peers (see Exhibit 1).  Large-cap managers may have been hampered by the dominance of mega-cap stocks, especially if they were underweighted in comparison to their benchmark weights.

In contrast, mid- and small-cap managers fared much better. Only 42% of mid-cap and 30% of small-cap managers underperformed their respective benchmarks. One potential explanation for these results may be style bias opportunities among smaller-cap managers, who may have benefited by taking strategic tilts toward outperforming larger-cap stocks, with the S&P 500 outperforming the S&P MidCap 400® and the S&P SmallCap 600® by 9.9% and 10.2%, respectively.

Style bias often explains performance across the capitalization spectrum; it may be easier for small- and mid-cap managers to tilt their portfolios toward larger companies with greater liquidity or to let their winners run. Historically, the odds of success for mid- and small-cap managers have improved when larger stocks have outperformed, with majority outperformance for small-cap mutual funds in 7 out of the past 22 years, of which 6 years coincided with large-cap outperformance.
SMA/wrap results within fixed income were mixed in 2023 across our three reported categories (see Exhibit 2). U.S. Aggregate accounts posted majority outperformance, followed by a moderate showing for Core, with 51% of accounts underperforming, and bleaker results within the muni space, with 86% of Municipal accounts underperforming the S&P National AMT-Free Municipal Bond Index.
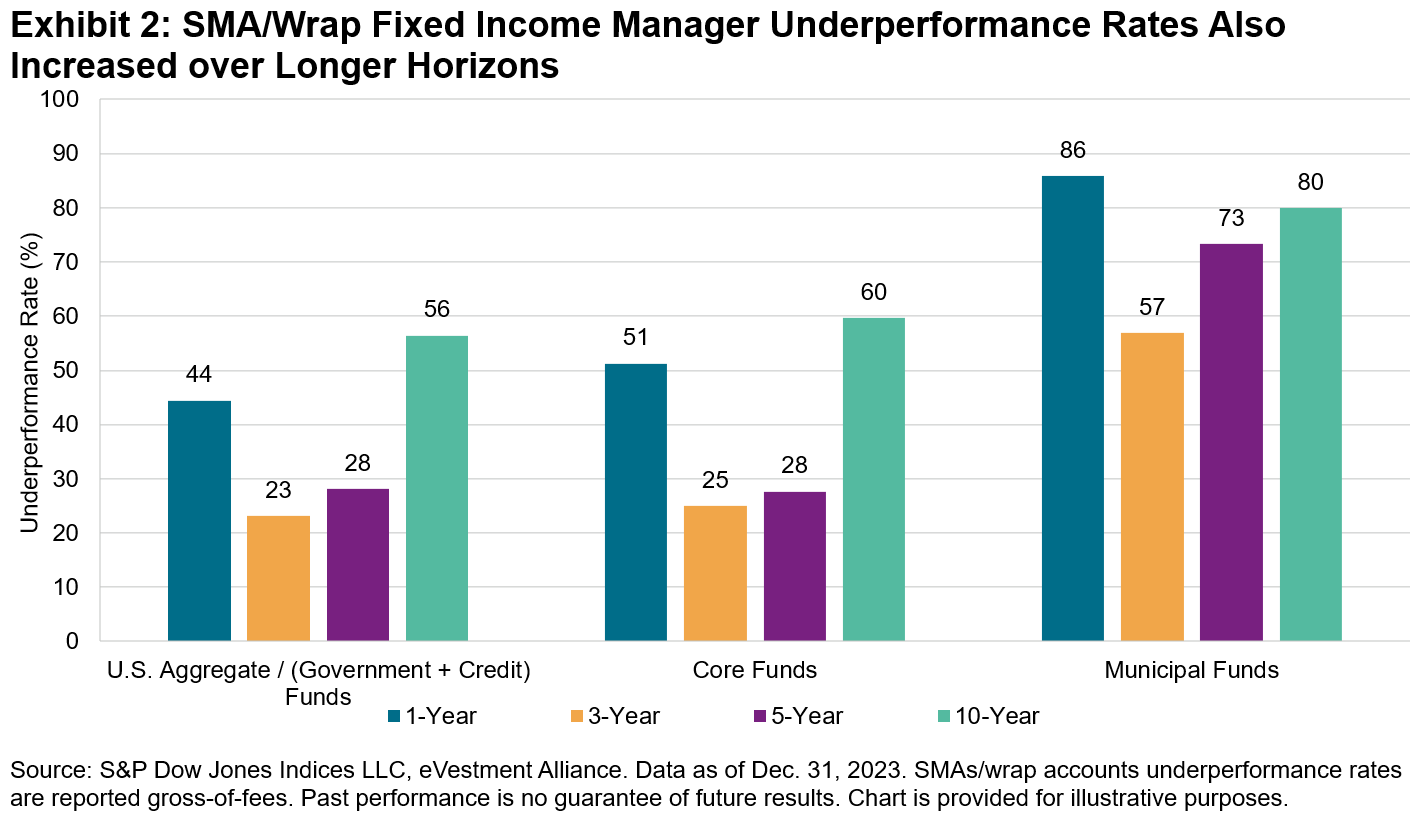
While there were a few categories with majority outperformance in 2023, our SPIVA scorecards have consistently shown that outperforming a benchmark over time is challenging, and this continues to ring true for SMAs/wrap accounts. Exhibits 1 and 2 show that more than 70% of accounts across equity SMA/wrap categories and more than 50% across fixed income categories underperformed their respective benchmarks over the 10-year period ending Dec. 31, 2023. For more detailed information on how SMAs/wrap accounts fared last year, please see our 2023 SPIVA Institutional Scorecard.

The author would like to thank Anu Ganti and Davide Di Gioia for their contributions to this post.
Fees and Fortunes

Contributor Image
Anu R. Ganti

Head of U.S. Index Investment Strategy

S&P Dow Jones Indices

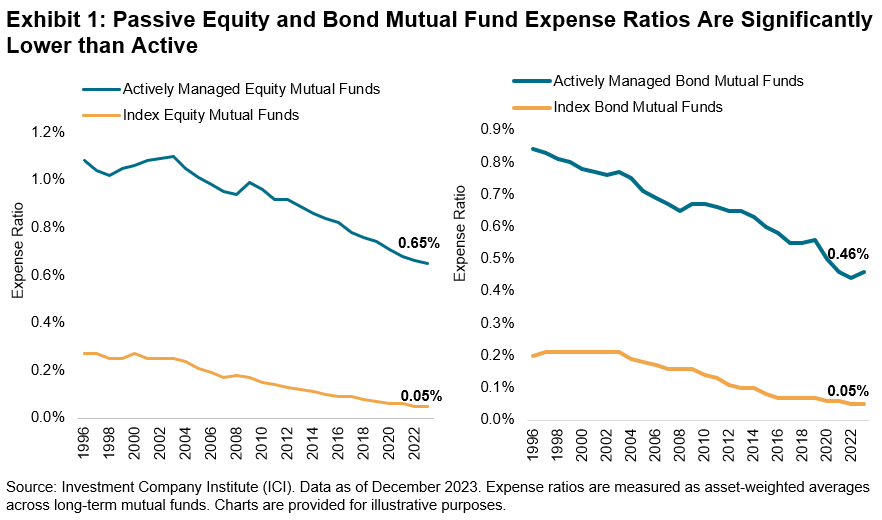
One of the potential advantages of indexing is its typically lower cost relative to active management. Investors have benefited substantially by saving on fees. And as indexing has expanded across asset classes, these rewards have compounded, especially in fixed income, where fees can prove more influential.

In Exhibit 1, we see that index mutual fund expense ratios in the U.S. have been consistently lower than their active counterparts for the past couple of decades. Although that spread has narrowed in recent years, we still observe a fee differential of 60 bps across equities and 41 bps across bonds as of 2023.

Exhibit 1- Passive Equity and Bond Mutual Fund Expense Ratios Are Significantly Lower than Active

In addition to fee savings, index-tracking investors may have also benefited by avoiding active underperformance. Particularly germane to the equity markets, our SPIVA® Scorecards show that only a handful of actively managed mutual funds have outperformed the benchmark. But how do we account for institutional investors who, unlike retail investors, claim an advantage in selecting skillful asset managers coupled with a better vantage point to negotiate fees?

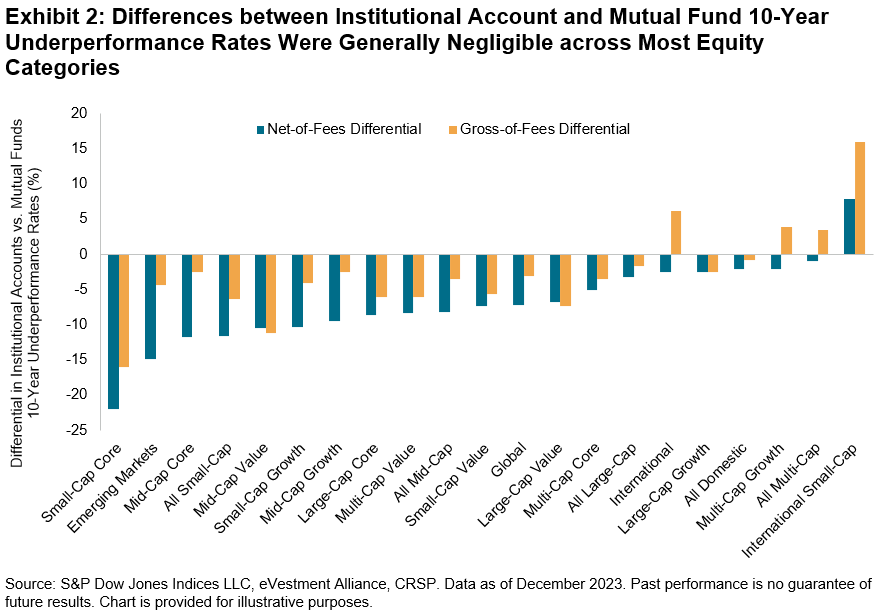
Our SPIVA Institutional Scorecard seeks to shed light on these questions, providing coverage of the performance of institutional accounts along with mutual fund data from the flagship SPIVA U.S. Scorecard. Exhibit 2 plots the differential in 10-year underperformance rates between institutional accounts versus mutual funds on both a net and gross-of-fees basis.

The chart illustrates several notable observations. First, long-term net-of-fees performance for institutional accounts was better compared to mutual funds in 20 out of 21 reported equity segments, with International Small-Cap Funds a noticeable outlier. Second, gross-of-fees relative performance for institutional accounts was better for 17 out of 21 equity categories. Third, except for a few categories, differences between mutual fund and institutional account underperformance rates were generally negligible, with majority underperformance for institutional accounts across all categories, on both a gross and net-of-fees basis.

Exhibit 2- Differences between Institutional Account and Mutual Fund 10-Year Underperformance Rates Were Generally Negligible across Most Equity Categories

While long-term results may slightly favor institutional accounts versus mutual funds, results can vary over the short term. In our most closely watched category, All Large-Cap Funds, 66% of institutional accounts underperformed the S&P 500® in 2023, worse than the 60% rate we observed for active large-cap mutual funds. Consistent 10-year majority underperformance rates across categories highlight the challenges of outperformance and show that institutional investors are no exception to the rule. Find out more about how institutional equity and fixed income managers fared last year in our SPIVA Institutional Year-End 2023 Scorecard.


Size, Momentum and Value

Contributor Image
Anu R. Ganti

Head of U.S. Index Investment Strategy

S&P Dow Jones Indices

Burgeoning optimism surrounding impending potential Fed rate cuts and a rotation toward smaller-cap stocks in July may have been short-lived, as global market jitters led to the trouncing of stocks across the capitalization spectrum on Aug. 5, 2024. The S&P 500® plunged 3%, its largest daily decline in almost two years.

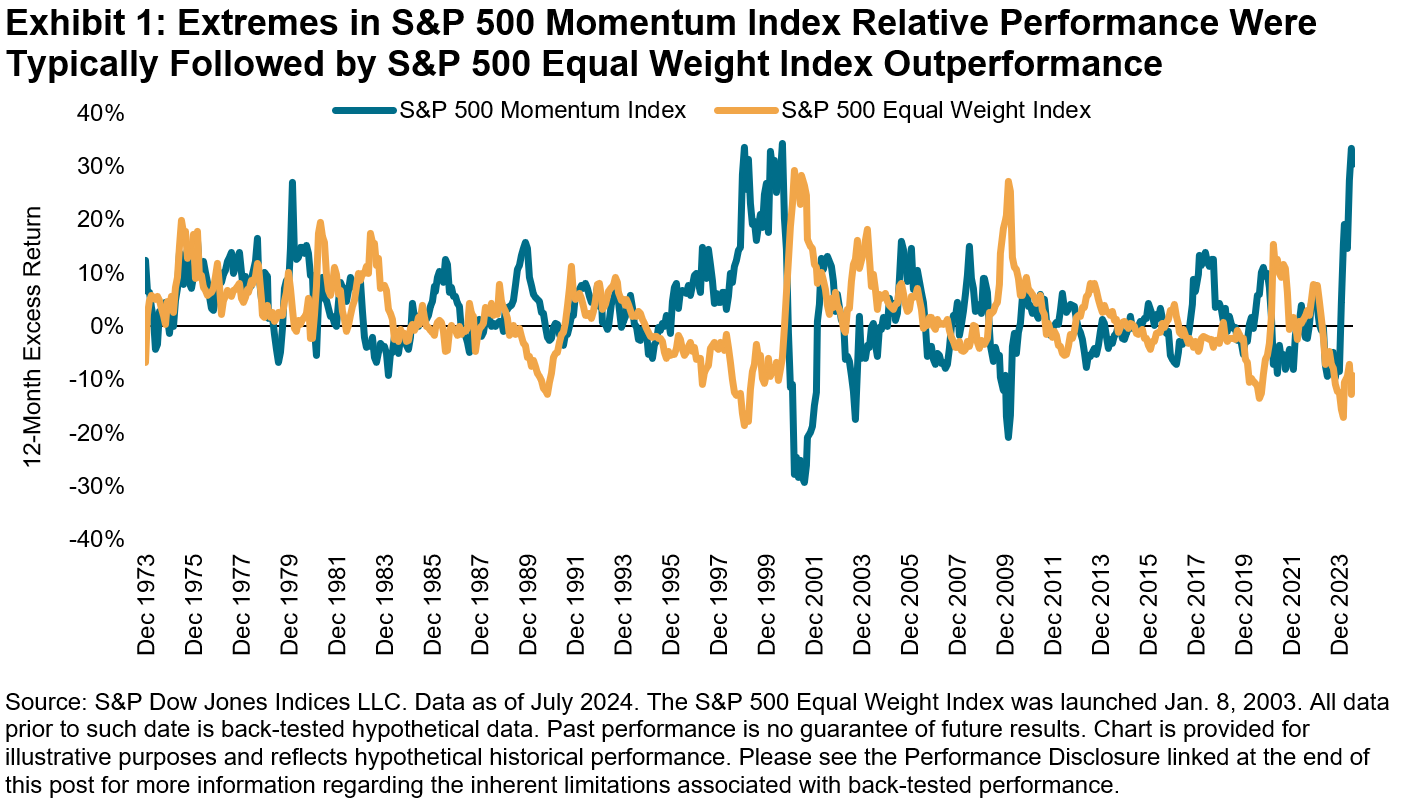
Despite this recent pullback, the outperformance of mega-cap stocks has been one of the most analyzed market themes of the past year, leading to severe underperformance of the small size factor. In parallel, the continuous outperformance of winning stocks across the cap spectrum led to the dramatic outperformance of the momentum factor. The S&P 500 Momentum Index outperformed the S&P 500 by more than 30% through the 12 months ending in July 2024, while the S&P 500 Equal Weight Index, which has a smaller-cap bias by design, underperformed the S&P 500 by 9% over the same period.

Exhibit 1 plots the historical 12-month relative performance for both indices, from which we can glean two observations: the S&P 500 Momentum Index and S&P 500 Equal Weight Index have an inverse relationship, not surprising given the latter's innate rebalancing mechanism of selling relative winners and buying relative losers, which is the opposite of momentum-based strategies. Secondly, the S&P 500 Equal Weight Index's outperformance tended to follow after peaks in the S&P 500 Momentum Index outperformance, most prominently after the burst of the tech bubble in the late 1990s, which makes the current environment an interesting one to examine the S&P 500 Equal Weight Index.

Larger stocks often carry heftier valuations than smaller stocks, and stocks that have fallen in price more than their peers are often more favorably valued as their prices continue to decline. As a result, we can expect the S&P 500 Equal Weight Index, which has a small size and anti-momentum bias, to also have a value bias.

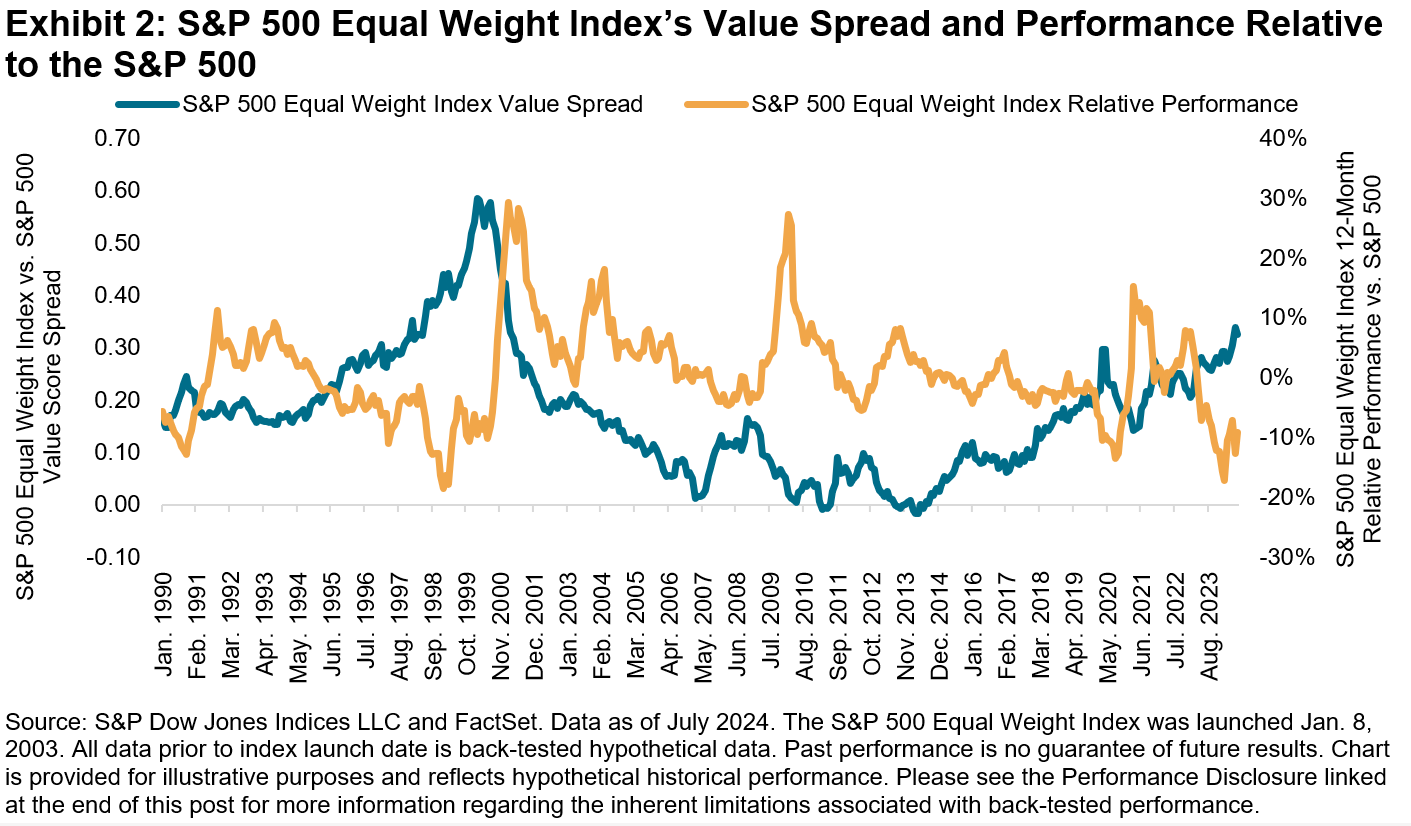
The S&P 500 Equal Weight Index's positive value tilt is evident from Exhibit 2, which calculates the spread of the index-weighted value score for the S&P 500 Equal Weight Index versus the S&P 500. The spread is generally positive, and we see that the index's value tilt has increased over the past year, as performance has suffered.

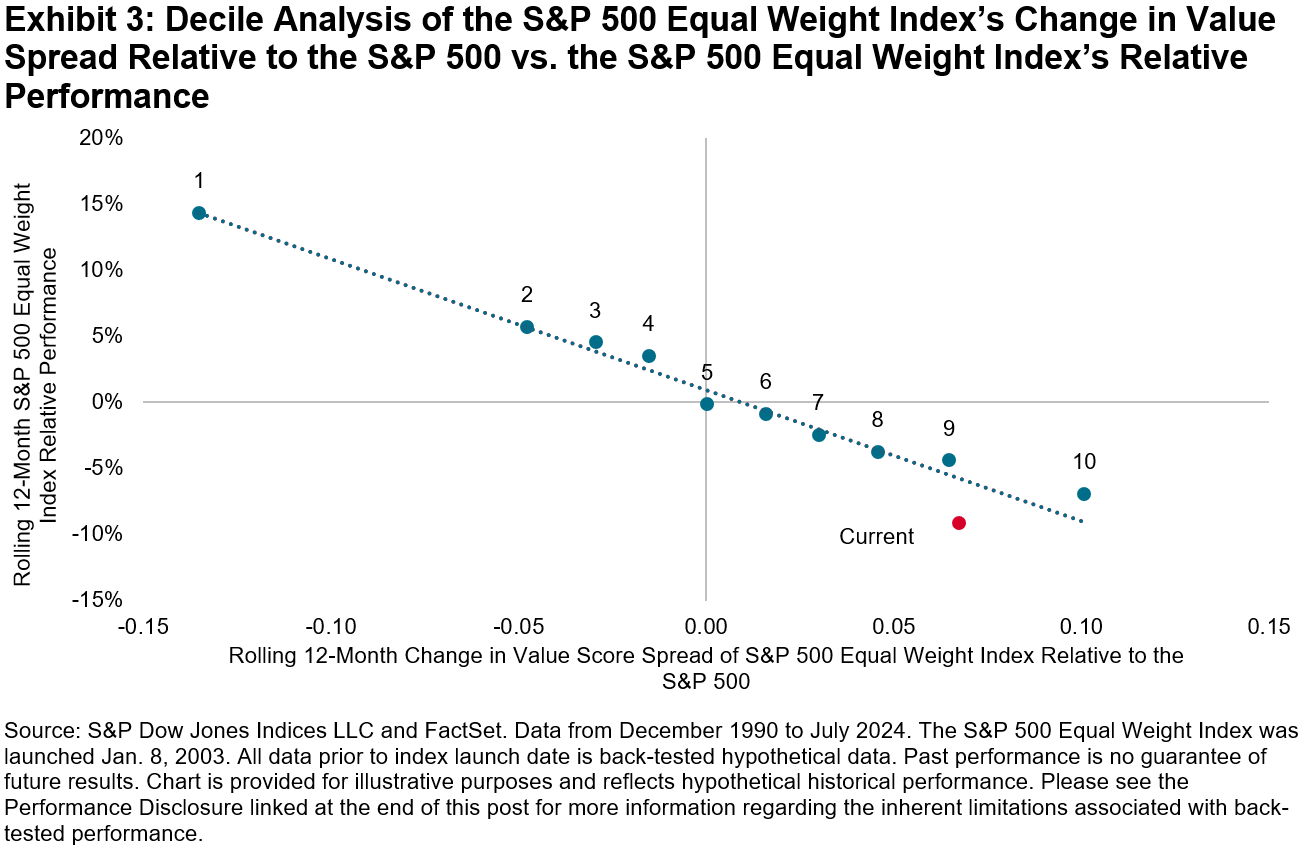
To provide further historical context, we group our database into deciles by their rolling 12-month change in value spread, and in Exhibit 3, we plot the average change in value spread on the x-axis, and the average relative performance of the S&P 500 Equal Weight Index on the y-axis. We again see an inverse relationship between changes in the index's value spread and its relative performance compared to its cap-weighted counterpart.

The current environment is situated just past decile 9, indicating that the S&P 500 Equal Weight Index has become relatively more undervalued compared to the S&P 500.

Whether we will experience a sustained pullback in mega-cap strength or a reversal in momentum remains to be seen. But if history is any guide, a potential decrease in the S&P 500 Equal Weight Index's value exposure corresponding with relative outperformance would not be surprising.


Drill Baby Drill: Commodity Performance in U.S. Election Years

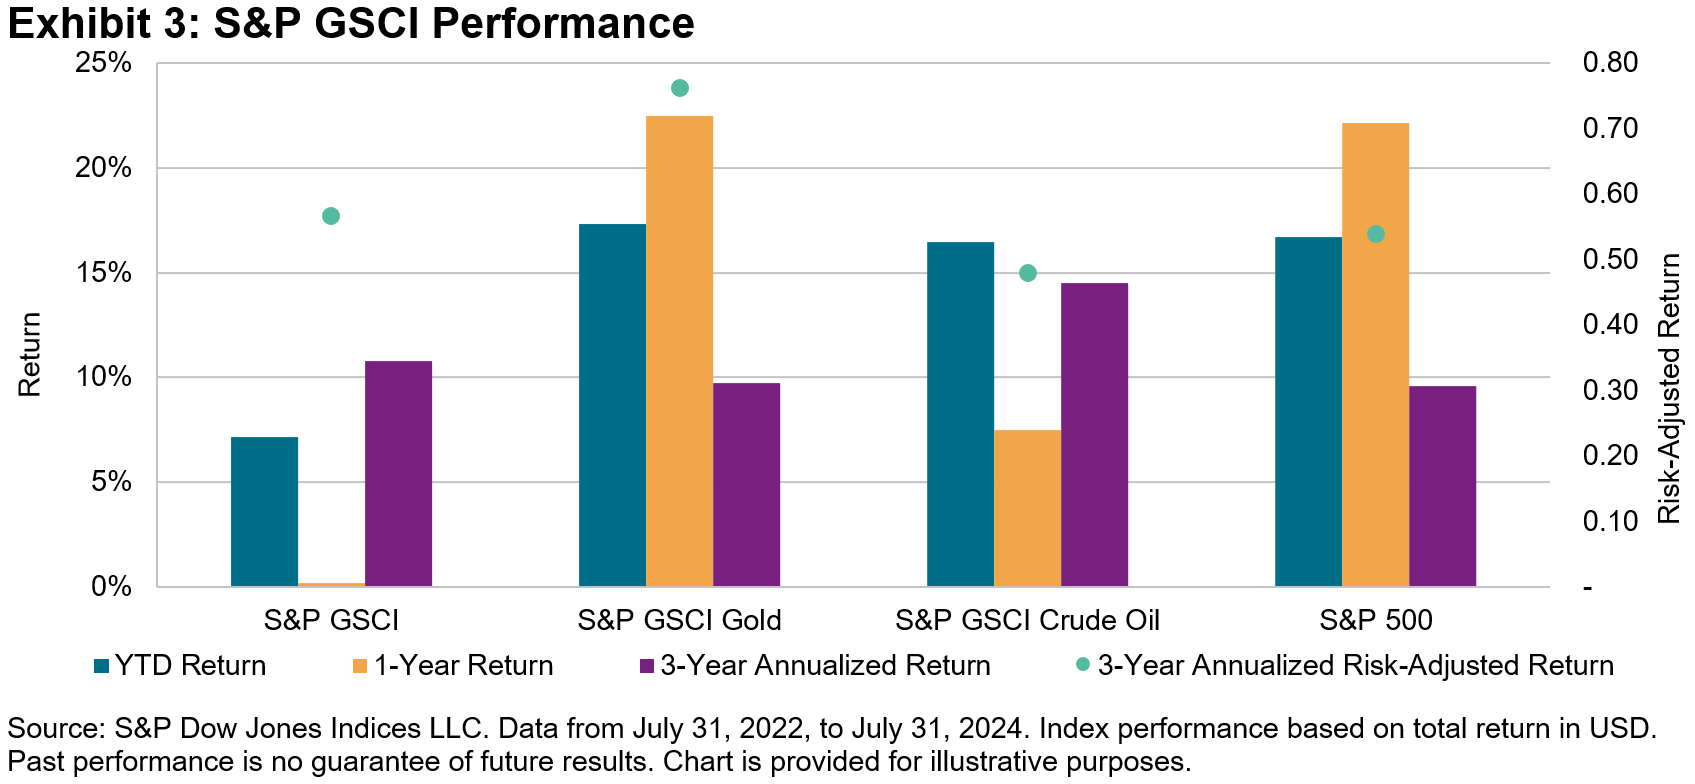
Following one of the more politically volatile months of this election year, commodity performance has delivered mixed results. The S&P GSCI Gold rallied 4.3%, while the S&P GSCI Crude Oil fell by the same amount. However, both gold and oil remained firmly up on the year, registering gains of 17.3% and 16.5%, respectively. Overall, they pared year-to-date gains back by 3.5%, finishing up 7.2%. With three months until the general election, we take a look at commodity performance during this crucial period in U.S. politics.

During the Republican National Convention, participants cheered at the prospect of the economic policies touted by the GOP nominee, Donald Trump. Chief among them are tariffs on foreign goods and the desire to ramp up production of U.S. oil. Both policies, if enacted, could have direct, albeit long-term, effects on the commodity markets. The likelihood of a Republican executive branch could help explain the steep moves during July in the S&P GSCI Crude and the S&P GSCI Gold. The potential increase in the supply of oil could help explain the fall in the S&P GCI Crude in the month; though countermeasures by OPEC+ and geopolitical events have contributed to volatility, according to S&P Commodity Insights. You can read more on what is driving the oil market as well as the outlook here and here. The prospect of increased tariffs and budget deficits could have contributed to inflationary worries, helping propel the S&P GSCI Gold up for the month.

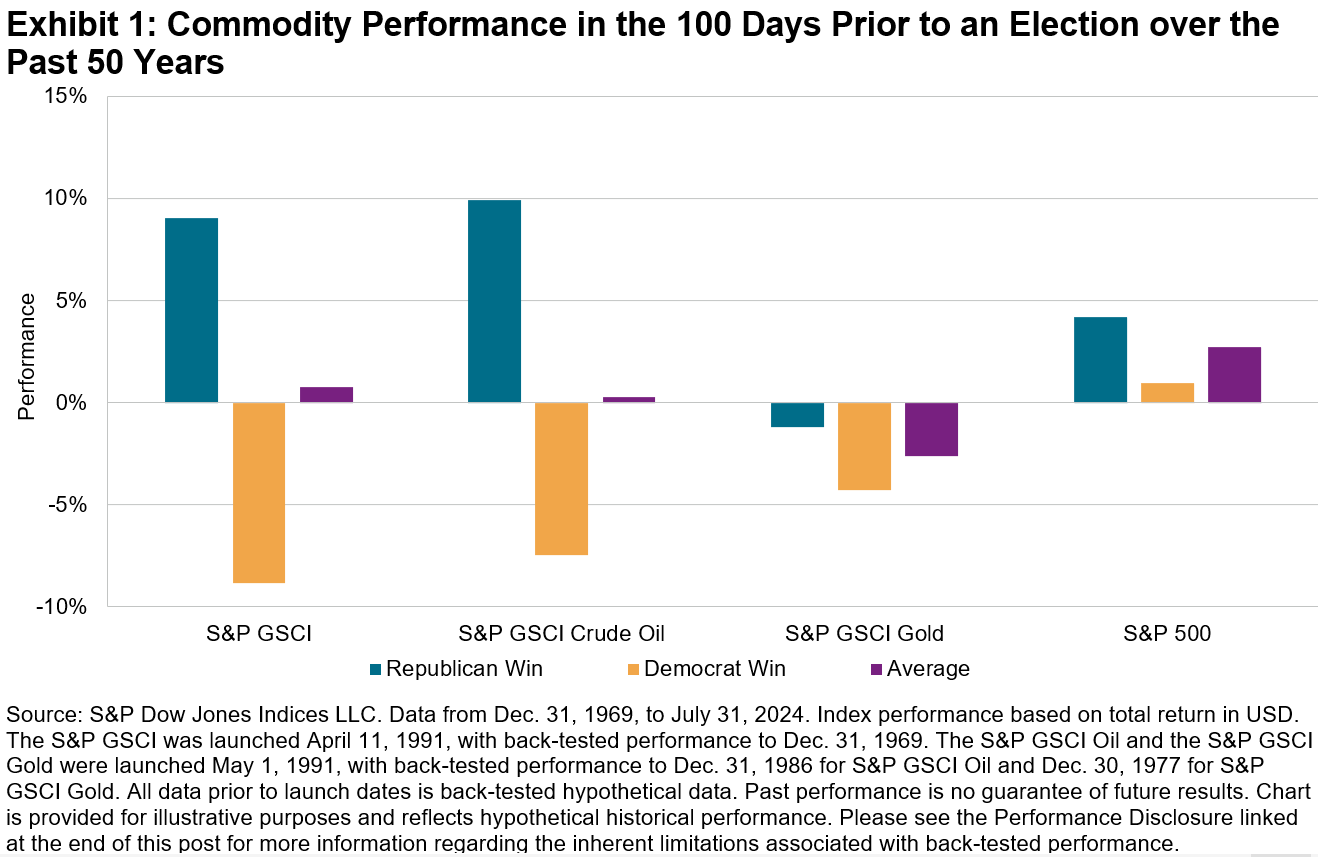
Looking back over the past 50 years of commodity performance during the run-up to presidential elections and the one year following them highlights stark differences based on which party goes on to take office. We measure both the 100 days leading up to an election as well as the one-year performance following election day. On average, the S&P GSCI has historically trended positive leading up to an election, and it has rallied 9% prior to a GOP win but retreated 8.8% before a Democrat has gone on to win (see Exhibit 1).

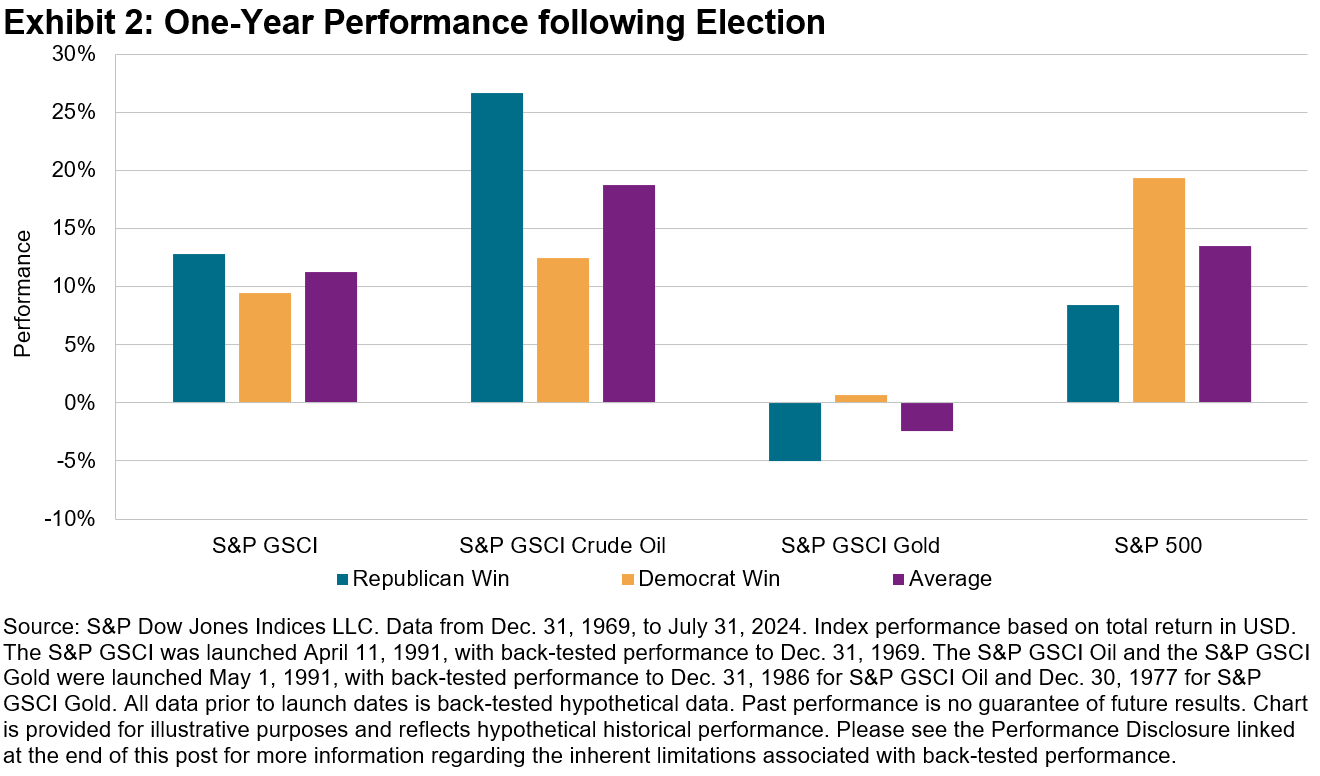
Regardless of winner, commodities have historically performed well, averaging 11.2% in the year following an election. Expanding across asset classes, commodities have outperformed stocks in the year following a GOP win, with oil contributing the largest average return of 26.7%, dating back to the 1988 election when oil futures first entered the S&P GSCI (see Exhibit 2). Historically speaking, the pursuit of expanding oil production by Republicans, or pursuing a policy to "drill baby drill," has led to substantial outperformance in the S&P GSCI Crude Oil, running contrary to what potential supply increases would do to dampen prices.

Balancing geopolitical and inflationary risks through a diversified commodity index like the S&P GSCI has historically led to less volatility than single commodities, while achieving positive correlation to inflation. The S&P GSCI has historically achieved returns in excess of 11% one year following an election, outperforming the S&P GSCI Gold with nearly half the volatility of the S&P GSCI Crude Oil over a three- and five-year period. Looking at the three-year annualized risk-adjusted returns, the S&P GSCI has outperformed the S&P 500 (see Exhibit 3).


Back to the Future

Contributor Image
Joseph Nelesen, Ph.D.

Head of Specialists, Index Investment Strategy

S&P Dow Jones Indices

In "Back to the Future," Marty McFly accidentally ends up 30 years in the past while using Doc Brown's time-traveling DeLorean. After realizing what has happened, he tries to get back to 1985 while not disrupting anything in the past that might adversely affect his life in the present.

Marty's main challenge was to save his own existence, and we all know he succeeds in the Hollywood ending, but what if he had a more difficult challenge like predicting which Latin American active managers might outperform in the future? While they may not be fusion-powered cars, SPIVA® and Persistence Scorecards act as time machines of sorts, allowing us to quantify the challenges of past decisions as well as their outcomes, and see what Marty would have faced.

For example, let's imagine Marty had accidently traveled back in time from 2023 to the end of 2018, and he tried to pick which funds would outperform over the next five years. What decisions might he have made with the best information available at that time?

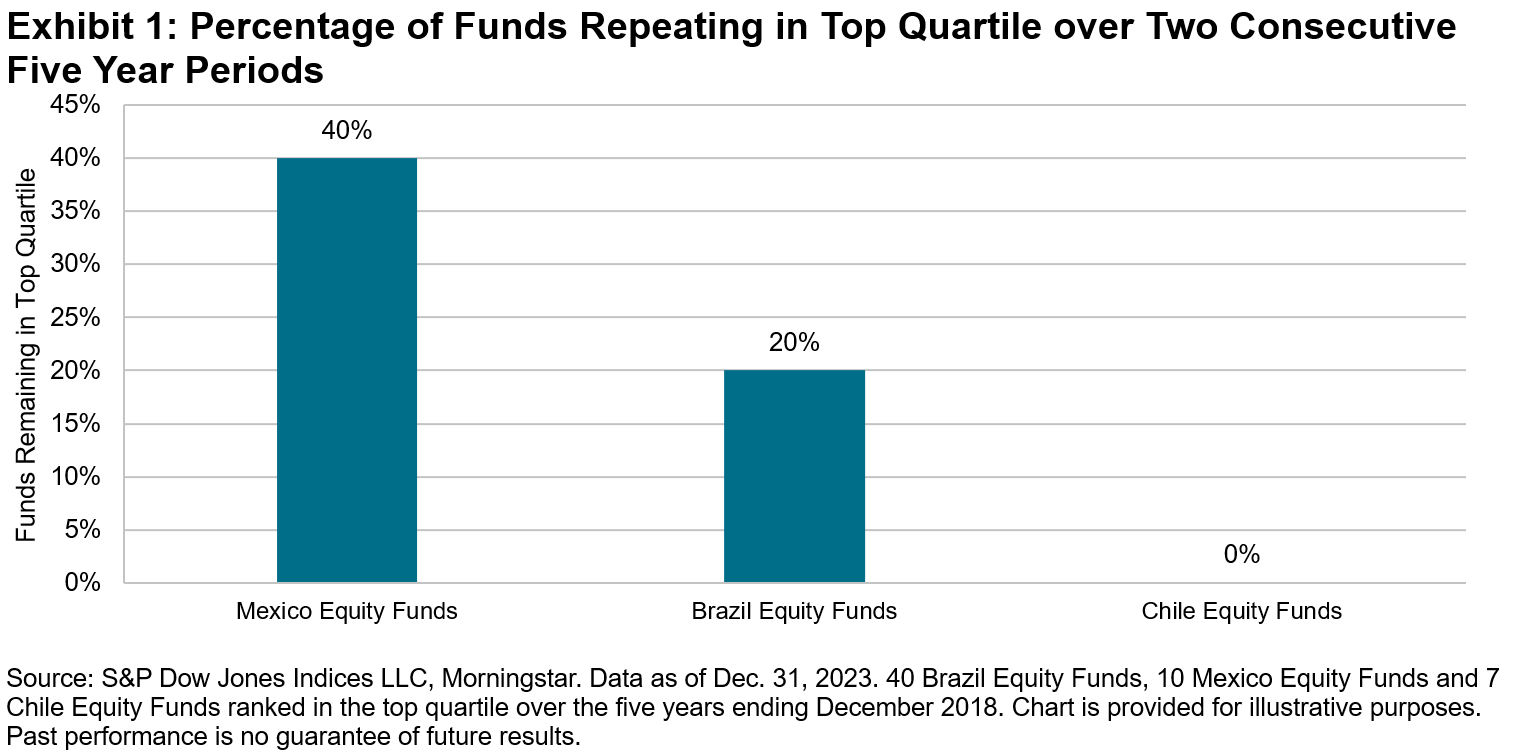
First, he might have chosen from high-ranked managers, believing that top performers stay on top. Based on the Latin America Persistence Scorecard for year-end 2023, 57 equity funds in Mexico, Brazil and Chile ranked in their respective top-quartiles over the five years ending in 2018, but only 12 of those funds remained in the top quartile through 2023 (see Exhibit 1).

Picking only from top-quartile funds, Marty's probability of predicting which funds would remain in the top quartile would have been just 21%, and a greater number of 2018's top-quartile funds (21) ended up in the bottom half by 2023. Nonetheless, let's assume he was lucky enough to pick a top-quartile manager in 2018 who also stayed in the top quartile through 2023. Would that have been sufficient to outperform its index?

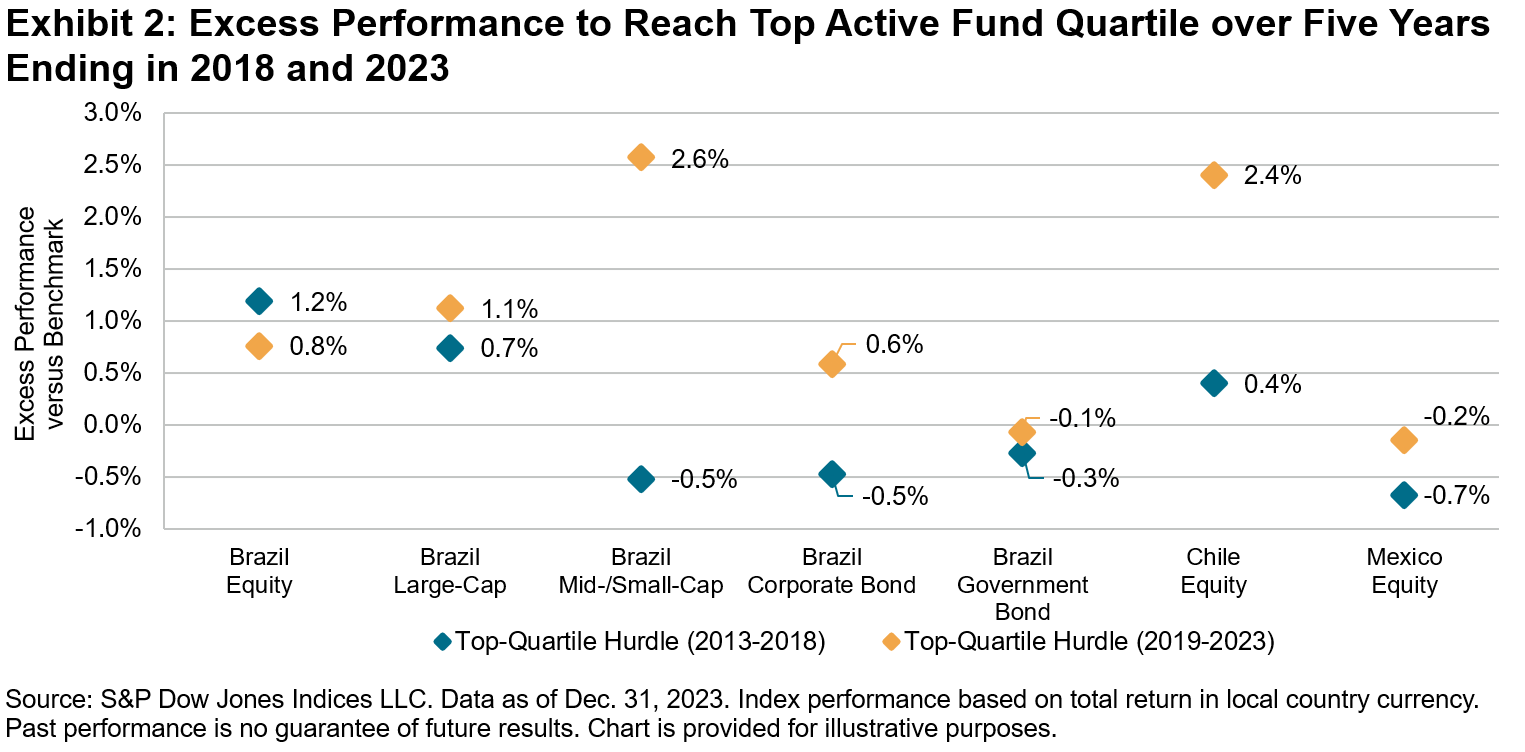
Data from the SPIVA Latin America Year-End 2023 and 2018 Scorecards show that this still would have been challenging for Marty. If we look at the excess performance needed for managers to reach the top quartile across various categories, we can see that in many cases, funds could have attained this distinction while still trailing their respective benchmark, as shown in Exhibit 2.

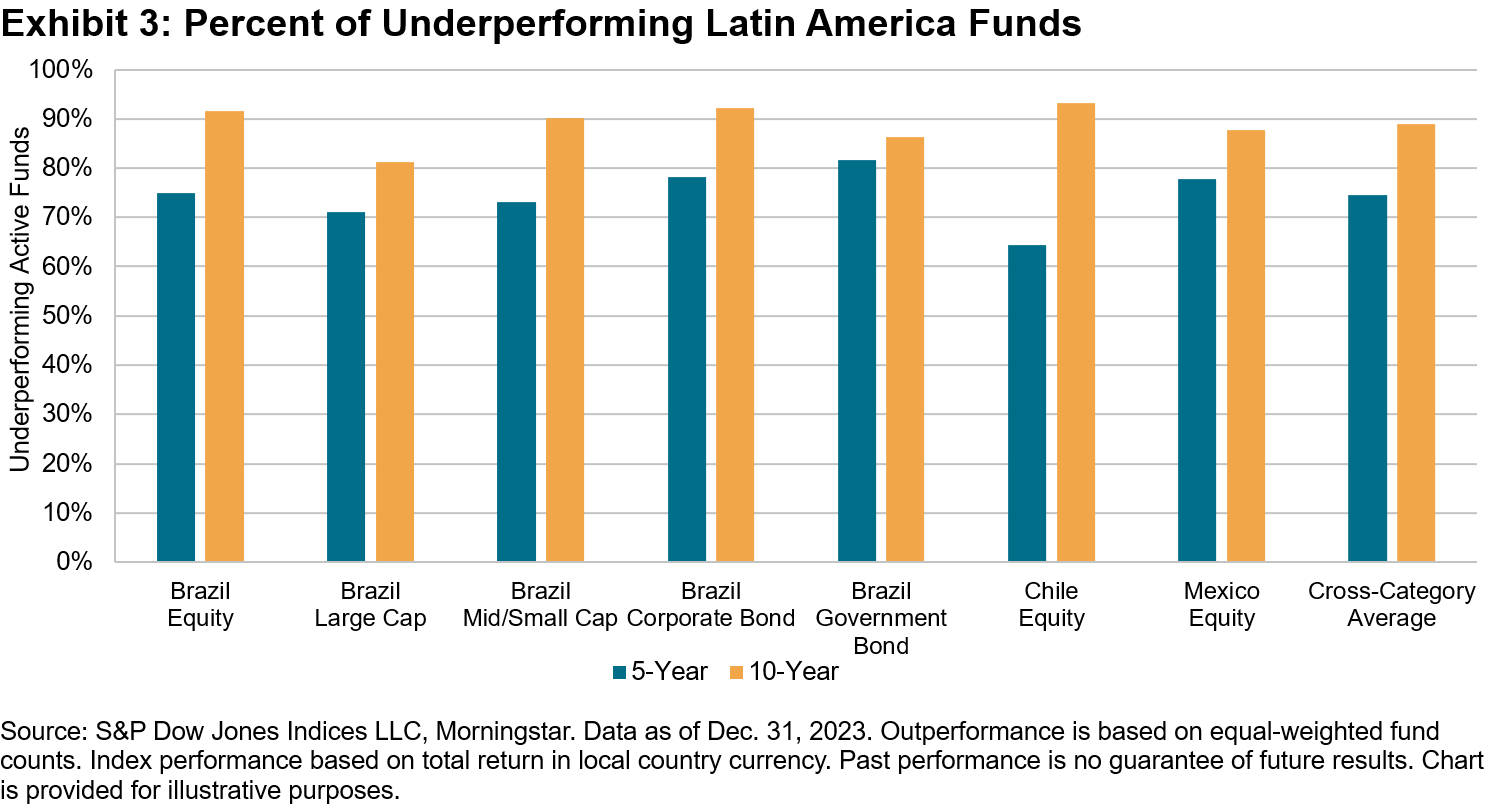
Ultimately, as shown in Exhibit 3, a cross-category average of 74% of Latin American funds underperformed their benchmarks over five years and 89% underperformed over 10 years. Even if Marty had successfully picked a fund that remained in the top quartile over two five-year periods, there is still a chance that the top-quartile fund would have trailed the index.

With the benefit of hindsight, we can clearly see how consistently challenging it is to predict the future of funds based on their past performance. Unlike Marty McFly, none of us have a time machine, a flux capacitor and a lucky bolt of lightning to go back and forth in time and change our decisions. But we do have something to guide our perspective on those choices that Marty couldn't imagine in 1955: the SPIVA Scorecard.