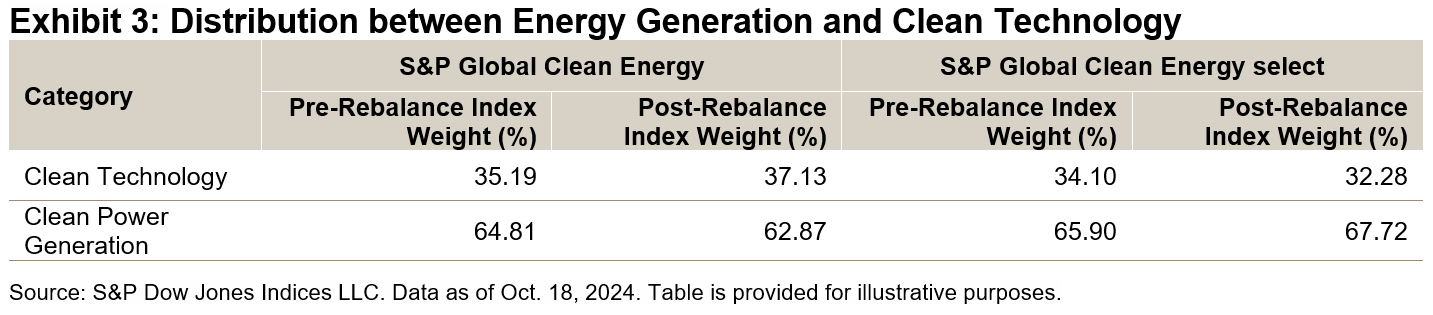

IN THIS LIST

Diversifying Exceptionalism

Rebalance Review of the S&P Global Clean Energy Index - H2 2024

S&P Israel 100 Index: Reflecting Israel's Potential

Carbon Intensity in the Middle East - An Index Perspective

Comparing the S&P Quality FCF Aristocrats Indices with the S&P Dividend Aristocrats

Diversifying Exceptionalism

Contributor Image
Anu R. Ganti

Head of U.S. Index Investment Strategy

S&P Dow Jones Indices

Despite recent sharp U.S. market declines after the Federal Reserve signaled fewer than expected rate cuts, much of recent year-end market commentary has been focused on U.S. exceptionalism and the divergence of U.S. equities compared to the rest of the world. The S&P 500® was up 24.8% YTD through Dec. 18, 2024, reaching 57 all-time closing highs so far this year, propelled by robust economic growth, AI-related enthusiasm and optimism surrounding President-elect Trump's return.

Exhibit 1 shows that U.S. outperformance is not a new phenomenon. The S&P 500 has significantly outperformed the rest of the world over the past fifteen years, with a cumulative return of 887% since Dec. 31, 2008, compared to an equivalent return of 320% for the S&P World Ex-U.S. Index.

We've noted previously that concentration trends can manifest at a country level. As a result of its outperformance, the weight of the U.S. component of our S&P World Index has risen accordingly from roughly 50% in 2009 to over 70% currently. Meanwhile, the U.S. dollar has strengthened in tandem, as illustrated by Exhibit 2, which may create potential headwinds for large-cap multinational companies that tend to have more overseas revenue exposures and tailwinds for smaller, more domestically sensitive stocks.

Turning our attention across the capitalization spectrum, the outperformance of U.S. equities broadened beyond large caps during the second half of the year, thanks to additional catalysts beyond dollar strength, including Fed rate cuts and post-election enthusiasm for potential impending tariff policies that may benefit smaller caps. Although mega caps have returned to favor so far in December, the S&P MidCap 400® and the S&P SmallCap 600® have outperformed the S&P 500 by 2.6% and 5.2%, respectively, since July 9, a key turning point for U.S. markets, as investors began to shift away from the Magnificent 7 and other mega caps toward smaller companies.

In addition to their stellar outperformance, U.S. equities are interesting to analyze for their diversification potential. In Exhibit 4, we calculate the spread in trailing 12-month volatility between the S&P World Index and S&P World Ex-U.S. Index. When this spread is positive, the inclusion of the U.S. increases volatility in the benchmark; when negative, the country acts as a diversifier. The negative spread that has occurred so far this year is an indication that the U.S. has become a volatility diversifier,1 consistent with the divergent performance observed earlier.

As we look ahead to 2025, while we do not know whether the U.S. market rally will be sustained or if smaller caps will maintain their momentum, we can acknowledge that if the outperformance of the U.S. compared to the rest of the world continues, the associated diversification properties may have important consequences for asset owners globally.


1We do acknowledge that the U.S. makes up more than 70% of the weight in the S&P World Index, but caveat that the U.S. component includes exposure to large multinational companies that have a diverse revenue base across geographies.


Rebalance Review of the S&P Global Clean Energy Index - H2 2024

Contributor Image
Abbie Zhang

Senior Analyst, Thematic Indices

S&P Dow Jones Indices

Launched in 2007, the S&P Global Clean Energy Index has been a headline benchmark for measuring clean energy-related companies' performance over the past 16 years. In April 2021, we launched the S&P Global Clean Energy Select Index to measure the 30 largest companies in global clean energy businesses listed on developed market exchanges.

Both indices had their semiannual rebalances on Oct. 18, 2024. The index methodology categorizes companies into four exposure score buckets ranging from 0 to 1, with a 0.25 increment, to measure their clean energy business purity. Exhibits 1 and 2 show the change in exposure before and after the October rebalance for both indices. For the S&P Global Clean Energy Index, the weighted average exposure score of the index increased slightly from 0.92 to 0.93. The S&P Global Clean Energy Select Index consists of 30 companies with an exposure score of 1 listed in the developed market exchanges (see Exhibit 2).

In the market allocation breakdown, significant changes in the S&P Global Clean Energy Index following the rebalance include a 6.41% increase in the weight of the U.K. and a 2.13% increase for Brazil, alongside an 8.80% decrease for the U.S. Meanwhile, for the S&P Global Clean Energy Select Index, Portugal's weight rose by 4.04%, while the weights of South Korea and Brazil experienced declines of 3.11% and 2.92%, respectively.

The S&P Global Clean Energy Index and the S&P Global Clean Energy Select Index track both the performance of clean energy technology firms and clean power generation companies (see Exhibit 3). During the recent rebalance, the index weight of clean technology in the S&P Global Clean Energy Index increased, primarily driven by a 1.12% rise in the index weight for the FactSet Revere Business Industry Classifications System (RBICS) subindustry of Wind Energy Equipment Manufacturing. Conversely, the index weight for clean power generation decreased, largely due to a 7.4% weight decrease in the RBICS subindustry of United States Northeast Electric Utilities.

The composition change of the S&P Global Clean Energy Select Index was different, featuring a decrease in clean technology weight alongside an increase in clean power generation weight. Within clean technology, there was a 3.39% drop in the RBICS subindustry of Photovoltaic and Solar Cells and Systems Providers. Meanwhile, clean power generation saw a 3.3% increase in the RBICS subindustry of Europe Mixed Alternative Wholesale Power and a 1.6% rise in the RBICS subindustry of Europe Solar Wholesale Power.

The inclusion or exclusion of constituents within the S&P Global Clean Energy Select Index could be a result of the change on exposure score, or it could be due to the market movements that changed the relative float market capitalization ranking of companies within the S&P Global Clean Energy Index. For exposure score information, please refer to S&P DJI's Client Resource Center.

S&P Global Clean Energy Index Performance YTD in 2024

Underperforming the S&P Global BMI YTD, the S&P Global Clean Energy Select Index was down 25.78% and the S&P Global Clean Energy Index was down 19.93% in USD total return terms. Dispersion was high among constituents of the S&P Global Clean Energy Index. SolarEdge Technologies (-83.12%), Shoals Technologies (-66.41%) and Hanwha Solutions Corporation (-61.58%) were among the lagging performers, while Suzlon Energy (up 61.24%) and NHPC (up 23.55%) made positive contributions, partially offsetting some of the losses.

We recently published the paper "Navigating the Clean Energy Transition: Market Dynamics and Performance Insights," which delves into the market dynamics around the clean energy transition. The paper outlines the energy transition process, provides an overview and performance review of the S&P Global Clean Energy Indices, discusses ongoing policy support for the energy transition and presents a quantitative analysis of performance. For those seeking a deeper understanding of these topics, the paper offers valuable perspectives on the current state and future potential of the clean energy transition.


S&P Israel 100 Index: Reflecting Israel's Potential

Contributor Image
Diego Zurita

Senior Analyst, Global Equities & Thematics

S&P Dow Jones Indices

The Israeli stock market has a unique landscape, offering stability and liquidity comparable to other well-established markets, while also providing regional diversification as the only developed market in the Middle East. In recent years, Israel has been a spotlight for technology and innovation, hosting many high-tech companies from industries like cybersecurity, biotechnology and software development. To highlight the significance of this market, S&P Dow Jones Indices offers the S&P Israel 100 Index.

The S&P Israel 100 Index measures the performance of the 100 largest and most liquid companies listed and domiciled in the Israeli stock market. Following a float-adjusted market capitalization weighting, the index is reconstituted and rebalanced quarterly to capture market trends. To reduce overconcentration, single constituent weights are capped at 8% and single GICS sectors are capped at 30% at each rebalancing. For more details about the index construction, the methodology can be found on the S&P Dow Jones Indices website.

Launched in August 2023, the S&P Israel 100 Index is calculated in U.S. dollars and new Israeli shekels with more than 12 years of daily index level data available. The index includes all 11 GICS sectors, with Financials having the biggest market cap weight at 31.9%, followed by Information Technology (19.0%) and Real Estate (13.0%), as of the end of November 2024 (see Exhibit 2).

After a year of volatility and an accompanying modest annual return of 4.8% in 2023, 2024 YTD returns for the S&P Israel 100 Index have seen multiple all-time highs. Having returned 23.4% YTD (as of November 2024), the index has maintained a similarly positive trend as the S&P 500 (up 28.1% YTD) and the S&P World Index (up 22.4% YTD), as seen in Exhibit 3.

The main contributors to the YTD performance of the S&P Israel 100 Index vary across sectors, with Financials playing a significant role, along with Teva Pharmaceutical Industries from the Health Care sector, whose growth has been attributed to an increase in revenue from both their generic and branded drugs, as well as semiconductor manufacturers (Tower Semiconductor Ltd and Nova Ltd) from the Information Technology sector, which have been boosted by increased interest around the AI space. The top 10 contributors of the index accounted for 72.3% of its performance (see Exhibit 4).

The Tel Aviv 125 Index, also known as the TA-125 Index, is one of the most broadly used benchmarks to reflect the performance of Israeli markets. The S&P Israel 100 Index has provided a differentiated return profile compared to the TA-125 Index, while exhibiting improved performance over the most recent 10-year period.

The S&P Israel 100 Index measures Israel's leading companies across the sector landscape. With a transparent, rules-based methodology, this index offers the possibility of geographical diversification among developed markets, given its focus on a country with unique characteristics. As the only developed market in the Middle East, the index reflects the distinct characteristics of Israel's dynamic economy.


Carbon Intensity in the Middle East - An Index Perspective

Contributor Image
Aran Spivey

Senior Analyst, Global Exchange Indices

S&P Dow Jones Indices

In December 2023, the COP28 UN Climate Change Conference was hosted in Dubai, once again putting the spotlight on global climate change action and handing the Middle East hosting responsibilities. Describing the current period as "the beginning of the end" of the fossil fuel era,1 this iteration of COP not only gave us the first global stocktake of progress against the 1.5°C by 2023 global warming target, but more specifically a unique opportunity to assess how the host region, the Middle East, stacks up in terms of both contribution to global warming and reduction of corporate carbon emissions.

Indices are a useful way to measure the performance of a basket of stocks, but they can also provide insight into the environmental credentials of listed companies. In this blog, we explore the carbon characteristics of the region via the S&P Pan Arab Composite and the S&P/Hawkamah ESG Pan Arab Index. The latter index measures the performance of the 50 top-performing stocks in the region, while incorporating environmental, social and governance (ESG) factors. The former index is a broad, float-adjusted, market-capitalization-weighted index with no specific ESG criteria incorporated, and acts as the benchmark for the ESG index.

Using S&P Global Trucost environmental data, we can assess how constituents of these indices have historically contributed to overall emissions and related metrics. This analysis enables us to explore a number of facets of climate transition. For example, which industries are the heaviest CO2 polluters? Which companies are leading the charge from a decarbonization perspective? How does the inclusion of ESG criteria in index design affect its carbon performance when compared to the benchmark?

Exhibit 1 provides us an overview of how the weighted-average carbon intensity (WACI) of the S&P Pan Arab Composite has increased over time.2 One noteworthy observation here is that corporate disclosure has improved with time, with more companies providing more thorough disclosure of their carbon performance. This is combined with improved modeling techniques on non-disclosing corporates.3

With overall emissions rising, which companies are most heavily contributing? Exhibit 2 provides an overview of which stocks have the greatest WACI, meaning that based on their weight in the index, they have the highest proportional CO2 emissions.

The S&P Pan Arab Composite has more stocks, meaning weights within the index are generally smaller than in the S&P/Hawkamah Pan Arab ESG Index. As a result, although ACWA Power Co has a WACI of 839.8, its smaller index weight minimizes its contribution to the overall WACI of the S&P Pan Arab Composite. Conversely, in the S&P/Hawkamah Pan Arab ESG Index, the lower number of stocks mean that they have greater weight in the index, leading to greater concentration. As a result, the overall index-level WACI of the ESG index has historically been higher.

As depicted in Exhibit 3, due to concentration within the S&P/Hawkamah Pan Arab ESG Index, it had a greater carbon intensity than its benchmark in 2021, 2022 and 2023.

Exhibit 4 depicts the overall country-level contribution of carbon intensity of the S&P Pan Arab Composite. As of June 2024, over one-half of the emissions of the index came from Saudi Arabia, while Kuwait was the second-largest contributor, at 14% of overall index emissions. This is aligned with country representation by market capitalization.

To identify sectors that are making progress, it is possible to compare the sector-level intensity and observe which sectors have seen reductions over time. Exhibit 4 shows the Trucost Revenue Sectors that have made the most progress since December 2019.

Coal Power Generation has experienced the largest reduction in intensity over this period, driven by Taqa Morocco's declining carbon intensity. However, overall emissions at an index level have increased, highlighting the need for corporate action on CO2 emissions.

This carbon analysis reveals that the S&P/Hawkamah ESG Pan Arab Index exhibited a higher WACI than its benchmark over the five-year period studied. While this finding highlights a notable disconnect between ESG scoring and actual carbon performance, it also emphasizes the evolving nature of ESG indices as they adapt to the complexities of sustainability metrics. While the S&P/Hawkamah ESG Pan Arab Index represents a significant step forward in promoting responsible investment practices in the region, encouraging companies to enhance their ESG performance and transparency, for those market participants seeking an improved carbon reduction at an index level, it may be the case that this should be factored into specific index design principles.

Ultimately, the S&P/Hawkamah ESG Pan Arab Index can serve as a valuable tool for assessing the ESG performance of companies within the region, as it integrates considerations for environmental, social and governance issues. As expectations on corporate sustainability proliferate, the index continues to act as a robust measurement of these crucial topics.


1See a summary of COP28 here: https://unfccc.int/cop28/5-key-takeaways

2For more information on metric calculation please see Index Carbon Metrics Explained.

3The full methodology available at Trucost Environmental Data: Methodology.


Comparing the S&P Quality FCF Aristocrats Indices with the S&P Dividend Aristocrats

Contributor Image
Elizabeth Bebb

Director, Factor & Dividend Indices

S&P Dow Jones Indices

While the S&P Dividend Aristocrats® Indices have been in existence for almost two decades, only now has the "Aristocrats" moniker been extended to a new series: the S&P Quality FCF Aristocrats® (Free Cash Flow Aristocrats) Indices. Like the S&P Dividend Aristocrats, this new series emphasizes consistency and the selection of high quality companies. While they share many core attributes, these two series offer differentiated exposure and track companies with distinct profiles. In this blog, we will compare these two series and explore how they can serve as complementary building blocks when paired together.

Methodology Comparison

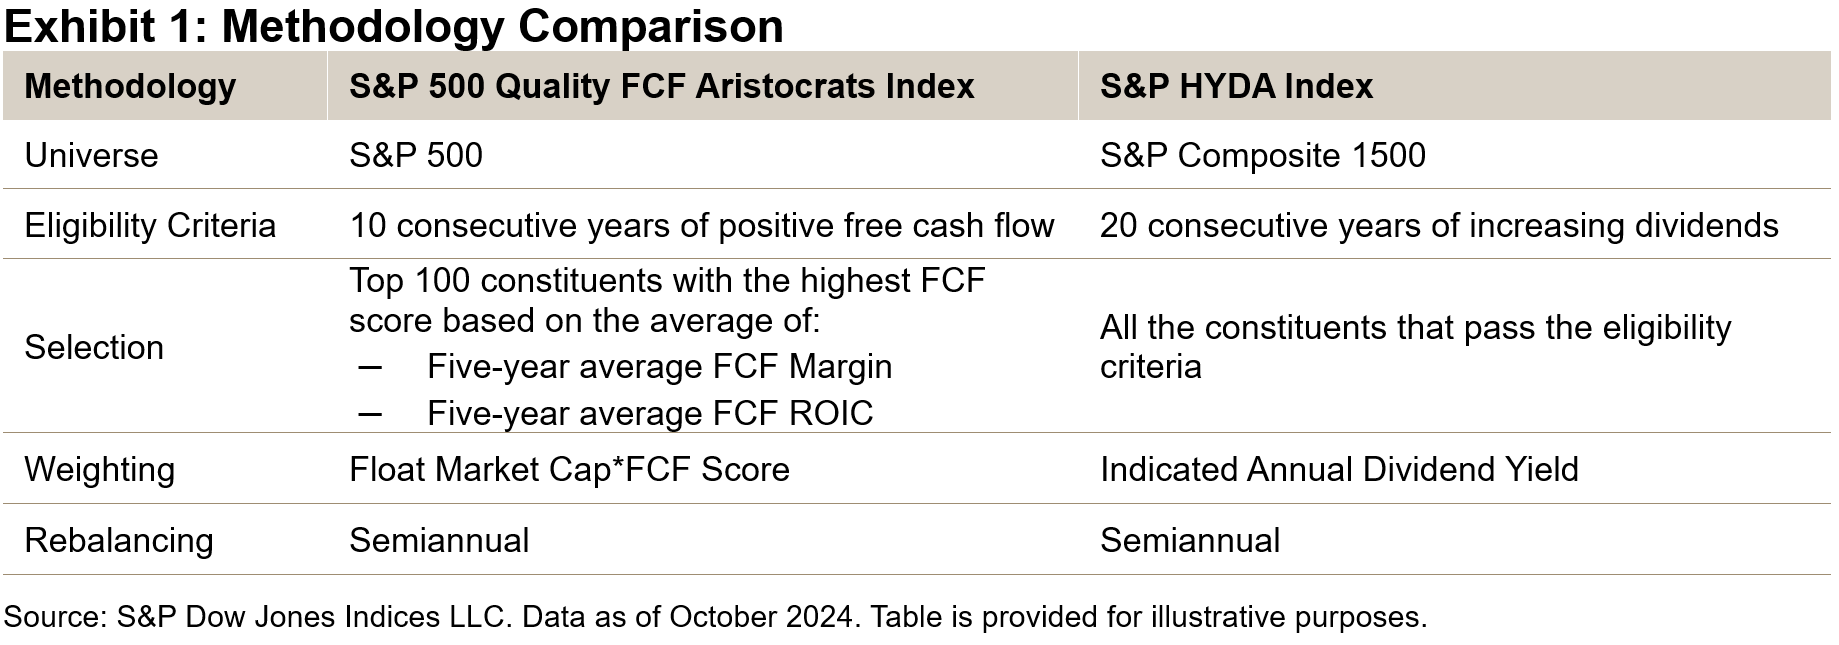
For the purposes of this blog, we will compare the S&P High Yield Dividend Aristocrats Index (S&P HYDA Index) with the S&P 500® Quality FCF Aristocrats Index, as both are based on a U.S. universe. The S&P HYDA Index is a dividend-focused strategy that tracks high-yielding large-, mid- and small-cap companies in the S&P Composite 1500® that have increased their U.S. dollar dividends for a minimum of 20 consecutive years. Comparatively, the S&P 500 Quality FCF Aristocrats Index is a free cash flow-focused strategy that tracks large-cap companies with a minimum of 10 consecutive years of positive free cash flow, along with high FCF margin and FCF return on invested capital (ROIC).

Index Characteristics

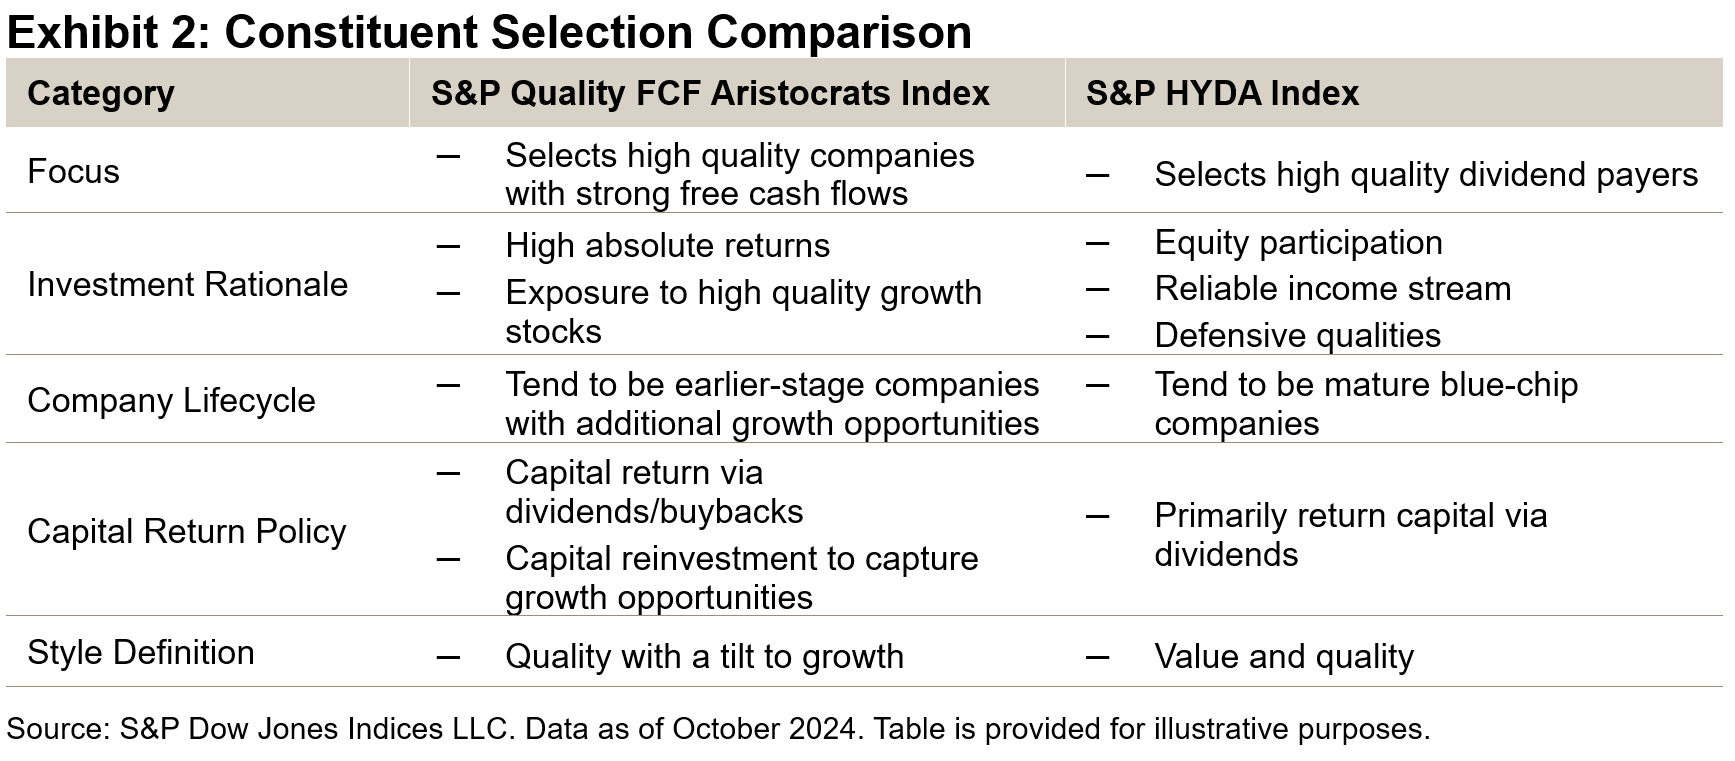
While both index series emphasize consistency as a key qualifier, they differ in their exposures and the types of constituents they track. The S&P HYDA Index aims to select high quality dividend payers, tilting to both value and quality. In contrast, the S&P 500 Quality FCF Aristocrats Index focuses on companies with high and consistent free cash flow, resulting in a purer focus on quality, as free cash flow measures true profitability and is less susceptible to manipulation, with a tilt to growth. This distinction reflects the company lifecycle: S&P HYDA Index companies are typically more mature, blue-chip firms, while the S&P 500 Quality FCF Aristocrats Index often comprises earlier-stage companies that tend to reinvest their capital at high rates of return to seize growth opportunities.

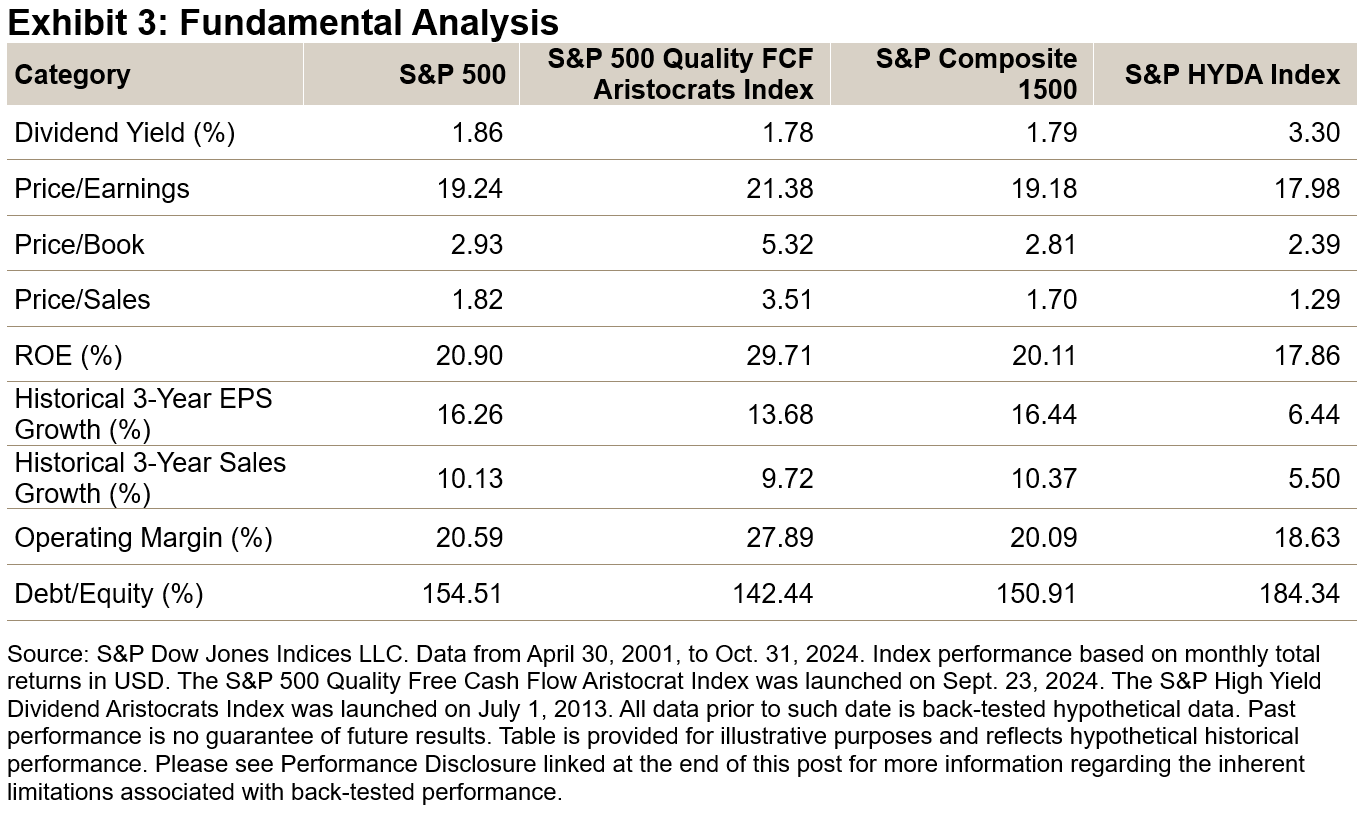
From a fundamental perspective, Exhibit 3 shows that the S&P HYDA Index tends to track companies with lower valuation multiples and higher yields. In contrast, the S&P 500 Quality FCF Aristocrats Index typically exhibits higher profitability, stronger sales and earnings growth, as well as elevated returns on equity.

Performance Comparison

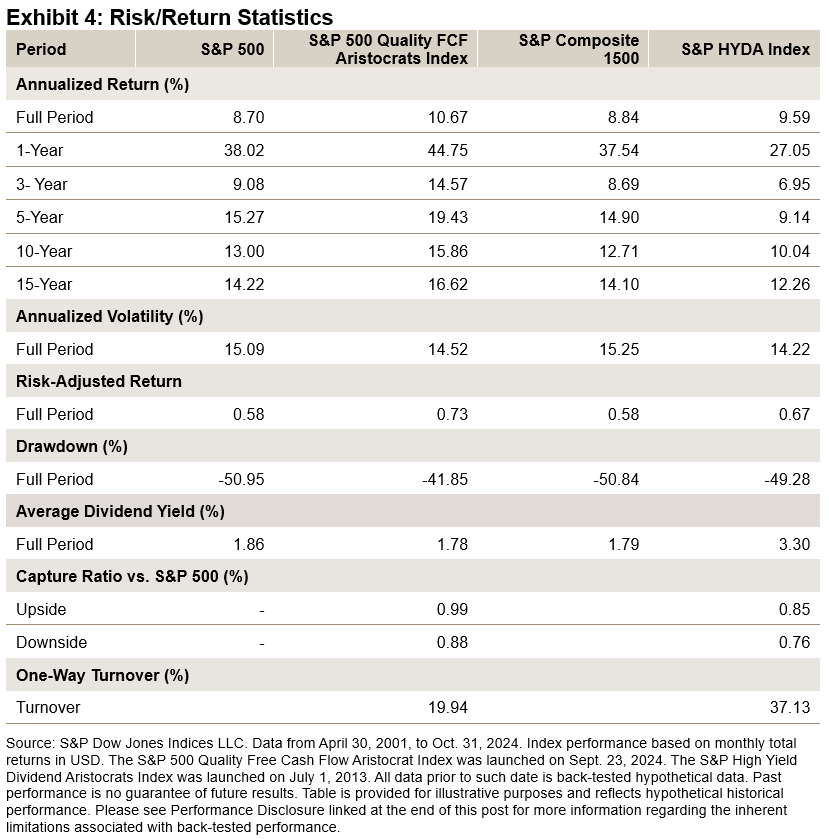
Both indices comfortably outperformed their respective benchmarks over the back-tested period since 2001 (see Exhibit 3), making a side-by-side comparison insightful. Notably, the S&P HYDA Index exhibited a lower upside capture ratio (0.85) but demonstrated strong defensiveness on the downside (0.76). The S&P 500 Quality FCF Aristocrats Index closely tracked the benchmark in up markets and showed moderate defensiveness on the downside, though not as robustly as the S&P HYDA Index.

Sector Comparison

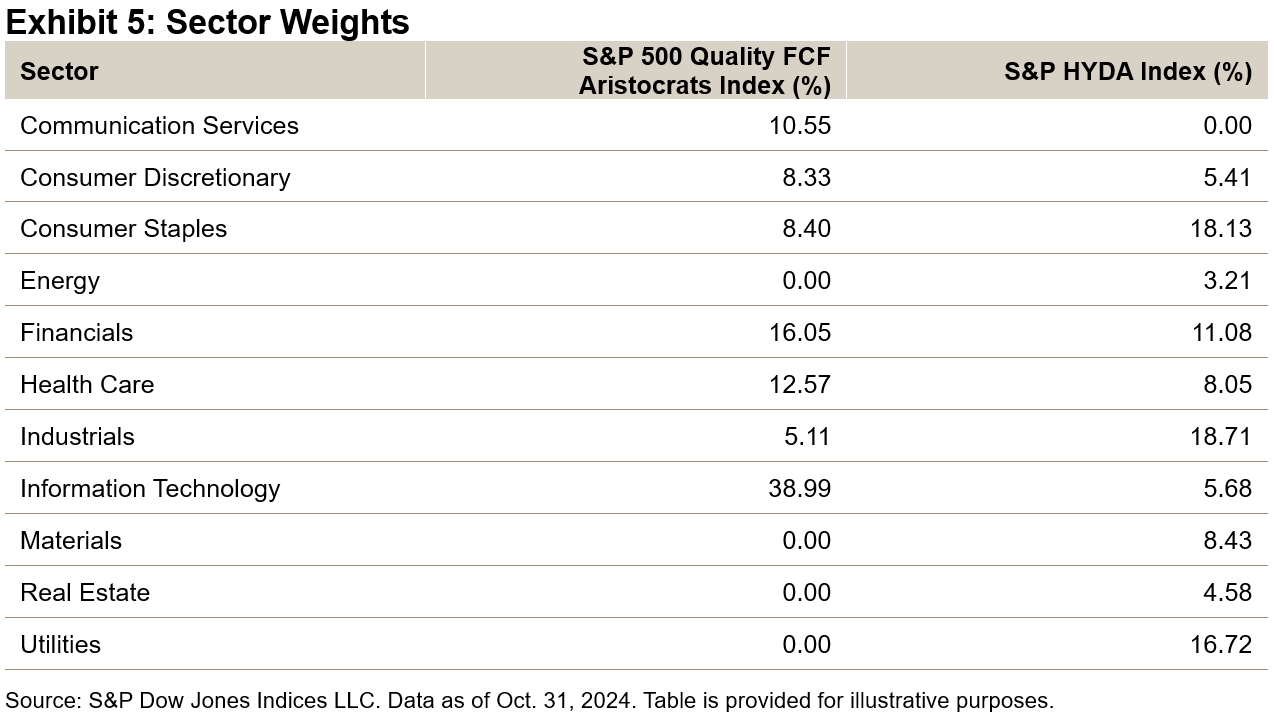
From a sector perspective, these indices could be considered complementary due to their contrasting sector overweights and underweights. The S&P HYDA Index generally favors defensive sectors such as Consumer Staples and Utilities, while the S&P 500 Quality FCF Aristocrats Index has a greater weight in secular growth sectors, including Information Technology and Health Care.

Pairing the S&P HYDA Index with the S&P Quality FCF Aristocrats Index

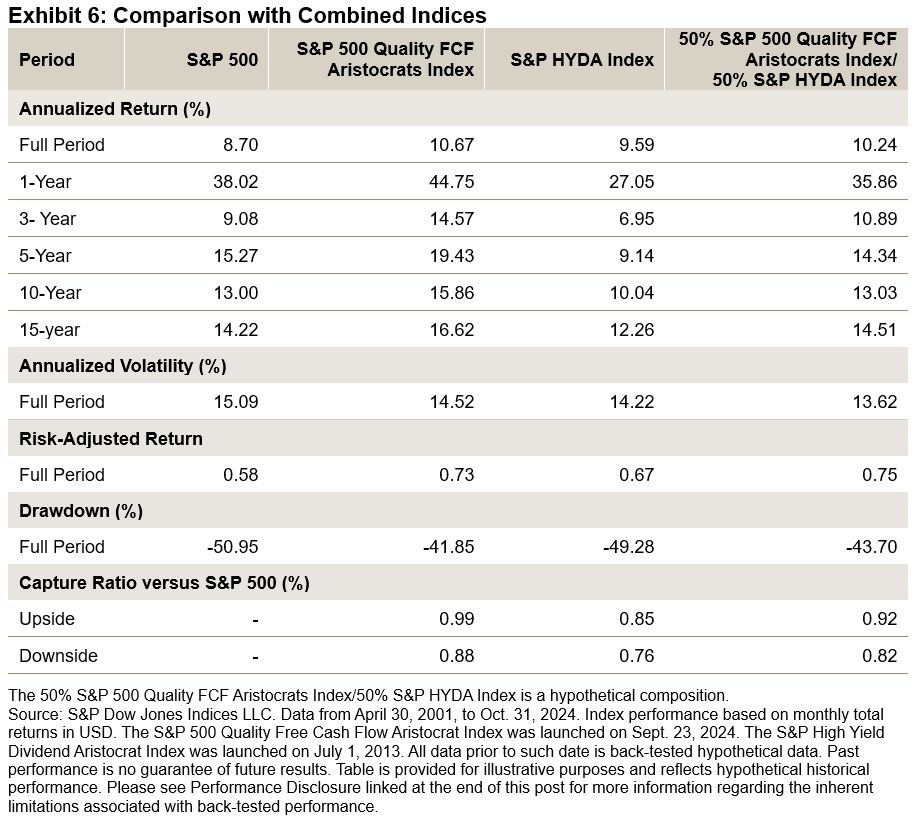
When choosing between these two indices, market participants should align their selection with their desired outcome. The S&P HYDA Index has historically tended to have equity participation with the potential for higher dividends and strong defensive qualities. The S&P 500 Quality FCF Aristocrats Index has demonstrated market-like upside capture ratios with enhanced quality, reduced downside risk and strong risk-adjusted returns. Alternatively, combining both indices may offer the best of both worlds, historically improving overall risk-adjusted returns and smoothing the impact of regime changes.

This new series of indices, while using the Aristocrats brand, has shown differentiated exposure versus the S&P Dividend Aristocrats. Compared with the S&P HYDA Index, the S&P 500 FCF Aristocrats Index has had low constituent overlap, higher weight in secular growth sectors and a pure focus on quality. We hope this blog has clarified the positioning of these two index series, demonstrating their potential as complementary tools.