
IN THIS LIST

Do Active Funds Outperform in Less-Efficient Markets?

Analyzing the Historical Performance of the S&P Quality FCF Aristocrats Indices across Macroeconomic Environments

2024 Open Interest Increase in iBoxx-Linked Futures

Rates, Risk and Relative Value

Performance Insights: The S&P 500 Equal Weight ESG Index

Do Active Funds Outperform in Less-Efficient Markets?

Active managers sometimes tout their ability to select stocks in markets that are considered less informationally efficient and those that offer larger rewards to successful stock pickers. Smaller companies and those in emerging markets are typically presented as examples. What are the grounds for debate, and what do over 20 years of SPIVA® Scorecards tell us about the historical record?

First, consider the efficiency argument. It is true that research coverage is broader and deeper in some markets than others, and it is intuitive to suppose that the likelihood of misvaluations is higher among more obscure companies. However, there is no reason to assume that the likelihood of undervaluation is higher than the likelihood of overvaluation; determining which is which may be no easier in well-researched markets than in less-researched ones.

Second, some markets do indeed offer larger rewards for successful active choices than other markets. One way to understand the magnitude of the opportunity set in a given market is through dispersion, which measures the degree of variation in the returns of an index's components over a specific period of time and at a specific level of granularity. When stock returns are more similar, dispersion is lower and the value of stock selection skill is accordingly lower. Conversely, when dispersion is high, opportunities may be greater.

In Exhibit 1, we plot monthly dispersion for the S&P SmallCap 600®, the S&P Emerging BMI and the S&P 500®. Over the past 23 years, dispersion was consistently higher in the first two indices compared to the third.

Drilling down, Exhibit 2 groups U.S.-based small-cap and emerging market active funds by the average dispersion registered in the category benchmark. We defined "low dispersion" as values falling below the 25th percentile, "high dispersion" as those above the 75th percentile and a third grouping encompassing all dispersion environments. In low dispersion environments, performance proved to be more challenging for large-cap and small-cap managers, with 67% and 73% of funds underperforming on average, respectively. However, even in high dispersion regimes, more than half of funds still underperformed in all three categories.
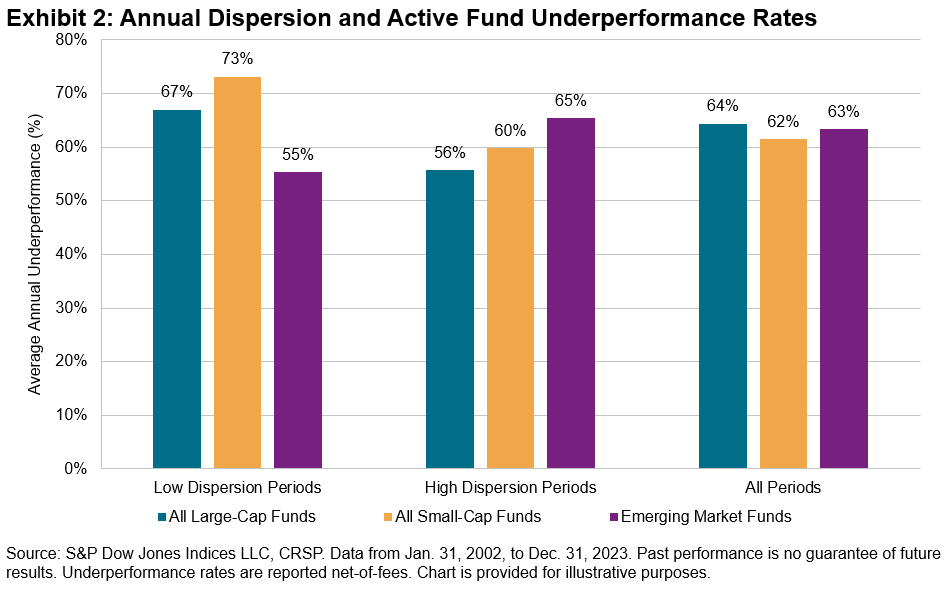
Exhibit 3 shows that only two years—2012 and 2019—saw the majority of managers in the Emerging Markets Equity category outperform, both of which coincided with relatively low dispersion environments. In contrast, there were only three years of majority outperformance for large-cap managers and six years for small-cap managers.1

All told, the rare success of active funds confirms that while there may be greater potential for outperformance in some markets, greater opportunity for outperformance is no guarantee of actual outperformance.
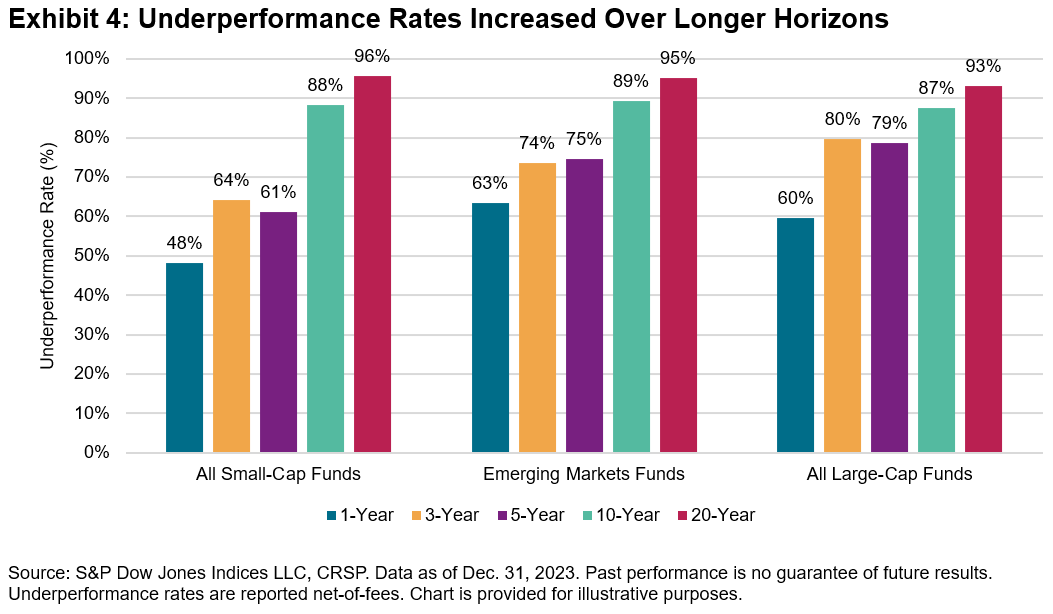
Over the long term, the statistics become even clearer. As summarized in Exhibit 4, regardless of the level of dispersion and whether managers are seeking alpha in widely researched markets like large-cap equities or more specialized areas, outperforming the benchmark over longer horizons remained particularly challenging.

Analyzing the Historical Performance of the S&P Quality FCF Aristocrats Indices across Macroeconomic Environments

Contributor Image
Wenli Bill Hao

Director, Factors and Dividends Indices, Product Management and Development

S&P Dow Jones Indices

S&P DJI recently launched a new family of indices known as the S&P Quality FCF Aristocrats which includes the S&P 500® Quality FCF Aristocrats® Index and the S&P Developed Quality FCF Aristocrats Index. A more comprehensive introduction to this family of indices can be found in this blog post.

Gaining insights into the historical performance of factor strategies across various macroeconomic environments is essential for risk mitigation and informed investment decisions.  In this blog, we will begin by analyzing the performance of these two newly launched indices across different economic regimes. Following that, we will compare the performance of the S&P 500 Quality FCF Aristocrats Index with that of another Aristocrats-branded index, the S&P High Yield Dividend Aristocrats, across the same four economic scenarios.

Macroeconomic Framework1

To assess performance across different economic environments, we use a framework that defines four distinct regimes based on whether growth2 and inflation3 are rising or falling. These regimes are organizing into four quadrants which are illustrated in Exhibit 1.

Considering the longer back-tested history available for the U.S. market compared to other developed markets, we present two distinct time horizons in our analysis (see Exhibit 2). The first time horizon spans 282 calendar months from May 31, 2001, to Oct. 31, 2024 for U.S. markets, while the second covers 222 calendar months from May 31, 2006, to Oct. 31, 2024, for developed markets. Exhibit 2 displays the number of months and relative frequency across each regime.

Performance Across Growth and Inflation Regimes

The historical risk/return characteristics of the S&P Quality FCF Aristocrats Indices and their respective benchmarks across the four economic regimes are illustrated in Exhibit 3. Historically, all the indices presented demonstrated highest absolute returns and risk-adjusted returns in the Rising Growth and Falling Inflation regime, followed by the Rising Growth and Rising Inflation regime. Conversely, these indices experienced much lower returns in the Falling Growth and Falling Inflation regime, with the worst returns—often negative—occurring in the Falling Growth and Rising Inflation regime.

Excess Returns4 in Four Economic Regimes

In this section, we analyze the macroeconomic performance of the S&P Quality FCF Aristocrats Indices in terms of their excess returns (ER) relative to their benchmarks (see Exhibit 4).

The S&P 500 Quality FCF Aristocrats Index consistently outperformed the S&P 500 in a Falling Growth environment, regardless of inflation trends. In the Rising Growth and Falling Inflation regime, its performance was comparable to that of the S&P 500. However, in the Rising Growth and Rising Inflation regime, it underperformed. This behavior indicates that the S&P 500 Quality FCF Aristocrats Index exhibits strong defensive characteristics whilst still meaningfully participating in market upside.

The S&P Developed Quality FCF Aristocrats Index consistently outperformed the S&P Developed LargeMidCap index by a wide margin in a Falling Growth environment, regardless of inflation trends. In the Rising Growth regime, its performance was slightly better than its benchmark. The results indicate that the S&P Developed Quality FCF Aristocrats index outperformed S&P Developed LargeMidCap in all economic regimes, meaning it was defensive in down markets while keeping pace strongly in up markets.

Comparison with the S&P High Yield Dividend Aristocrats

In a previous blog, we compared the S&P 500 Quality FCF Aristocrats Index with the S&P High Yield Dividend Aristocrats, demonstrating that these two indices provide differentiated exposure and track companies with distinct profiles. Now, let's examine how they perform across the defined macroeconomic regimes.

Overall, the indices have differentiated exposure across these regimes. The S&P High Yield Dividend Aristocrats achieved its highest excess returns during the Falling Growth and Rising Inflation environment. In contrast, the S&P 500 Quality FCF Aristocrats led the way during both Falling Growth regimes, regardless of the inflation regime. However, both indices underperformed relative to the broad market during the Rising Growth and Rising Inflation regime.

In conclusion, the S&P Quality FCF Aristocrats Indices have historically outperformed during periods of falling economic growth, regardless of the inflation regime. In times of rising growth, both indices performed in line with the benchmark during falling inflation; however, the S&P 500 Quality FCF Aristocrats lagged when inflation was rising. Furthermore, our analysis shows that the S&P 500 Quality FCF Aristocrats offer differentiated exposure compared to the S&P High Yield Dividend Aristocrats, highlighting their potential as complementary tools.

1 Hao, Wenli Bill and Rupert Watts, "A Historical Perspective on Factor Index Performance across Macroeconomic Cycles," S&P Dow Jones Indices LLC, Nov. 14, 2024.

2 Rising growth is defined as a positive monthly change in the U.S. Composite Leading Indicator (CLI) compared to the previous month, while falling growth is defined as a negative monthly change.

3 Rising inflation occurs when the three-month average of U.S. Consumer Price Index (CPI) exceeds that of three-year moving average, while falling inflation occurs when falling below.

4 Excess return measures how much the average monthly total return of each index exceeds that of its corresponding benchmark in each regime.


2024 Open Interest Increase in iBoxx-Linked Futures

Contributor Image
Nicholas Godec

Senior Director, Head of Fixed Income Tradables & Commodities

S&P Dow Jones Indices

In 2024, open interest in futures tracking the iBoxx iShares $ High Yield Corporate Bond Index and iBoxx iShares $ Investment Grade Corporate Bond Index rose considerably. Open interest in futures referencing the iBoxx $ Liquid Emerging Markets Sovereigns & Sub-Sovereigns Index also increased following its June 17, 2024, launch.

For the iBoxx iShares $ High Yield Corporate Bond Index, 2024 open interest expanded by 245% to USD 414.9 million, while the iBoxx iShares $ Investment Grade Corporate Bond Index realized growth of 238% to USD 267.4 million in 2024. This occurred alongside trading volumes of USD 12.4 billion and USD 10.1 billion, respectively, for futures tied to the iBoxx iShares $ High Yield Corporate Bond Index and iBoxx iShares $ Investment Grade Corporate Bond Index throughout the year.

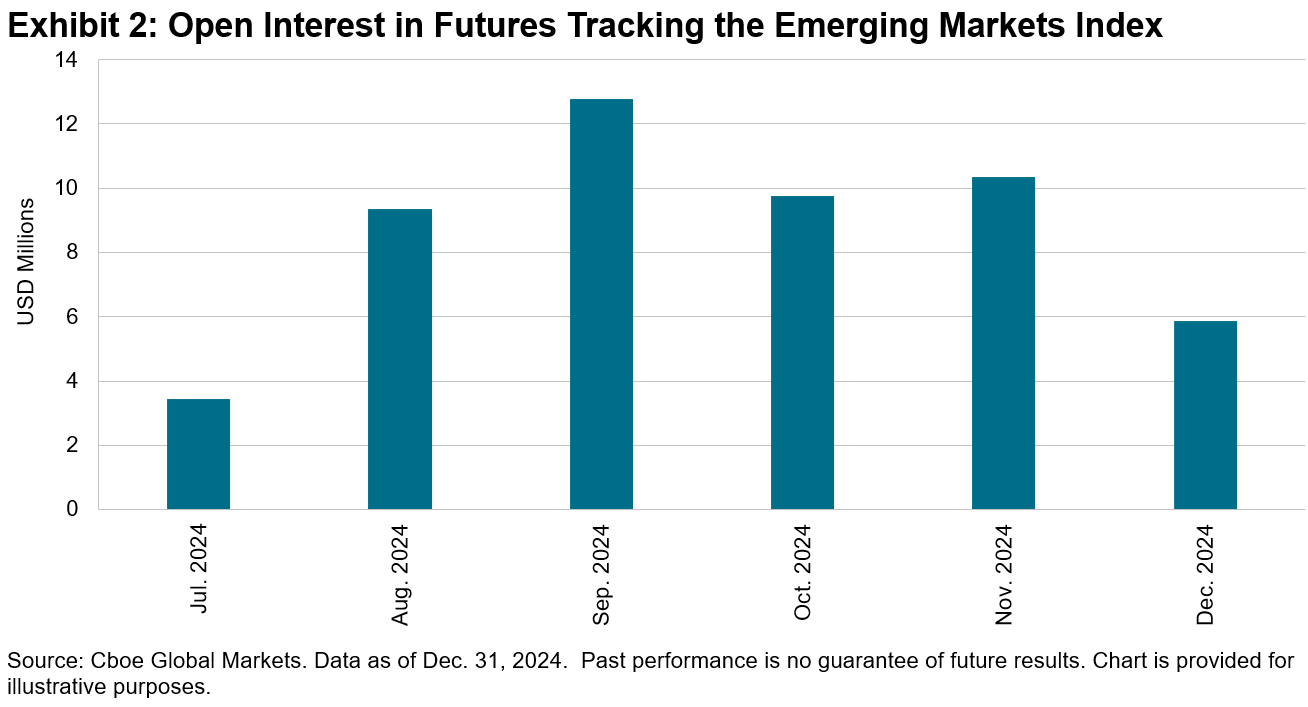
Futures tracking the iBoxx $ Liquid Emerging Markets Sovereigns & Sub-Sovereigns Index have traded USD 466.3 million in notional value since their June 17, 2024, launch. Average daily open interest initially rose from USD 3.5 million in July to a peak of USD 12.8 million in September, moderated to USD 9.8 million in October and USD 10.3 million in November, and ended the year at USD 5.9 million in December.

The growth in iBoxx-linked futures open interest highlights the uptake of these indices within the tradable credit ecosystem, while the launch of futures tracking the iBoxx $ Liquid Emerging Markets Sovereigns & Sub-Sovereigns Index indicates demand for additional measures and trading tools across credit market segments. As index-based solutions evolve, these developments underscore an ongoing shift toward broader, more flexible mechanisms for managing and accessing credit exposures.

For more information, please see 2024 Fixed Income Review: Elevated Yields and Increase in Index-Linked Futures Trading.


Rates, Risk and Relative Value

Contributor Image
Anu R. Ganti

Head of U.S. Index Investment Strategy

S&P Dow Jones Indices

It is clear that the rapid rise of the 10-year U.S. Treasury yield could have significant implications for active bond manager performance, as well as bond market volatility dynamics. But how might this affect the equity market? Another important role of U.S. Treasury yields is to act as a risk-free rate to compare to the market return, the excess return of which is known as the equity risk premium.

Coupled with rising yields and continuous record highs for the stock market, Exhibit 1 shows that the S&P 500® equity risk premium, measured here as the difference between the S&P 500 trailing 12-month earnings yield versus the 10-year U.S. Treasury yield, has plummeted over the past year, most recently entering negative territory. The last time the equity risk premium was below zero was following the burst of the Tech bubble during the early 2000s.

While the equity risk premium may indicate that equities seem relatively expensive compared to bonds, we do caveat that as of Jan. 21, 2025, Q4 2024 S&P 500 earnings season has started off on a solid note, particularly among the big banks, and if earnings growth continues, that might help to support current valuations.

We can also analyze equities and bonds from an income lens by comparing the market's dividend yield to 10-year U.S. Treasury yields. Exhibit 2 illustrates that the yield on the 10-year U.S. Treasury of 4.6% has significantly outpaced the S&P 500 trailing 12-month dividend yield, which has declined over the past couple of decades to 1.3% as of Jan. 17, 2025.

Bonds may seem relatively better positioned from a valuation and income vantage point, but their diversification potential is also interesting to examine. We observe in Exhibit 3 that correlations between equities and bonds, as measured by The 500™ and S&P U.S. Treasury Bond Current 10-Year Index, have recently turned negative. After witnessing positive correlations for most of 2024, this reversal, if sustained, might be indicative of a tailwind for enhanced risk-adjusted performance for combinations of both asset classes.

As we enter a new presidential regime, filled with many uncertain variables, we may not know the future trajectory of bonds or equities, but understanding their historical value, income and diversification characteristics could aid investors to adapt accordingly.


Performance Insights: The S&P 500 Equal Weight ESG Index

Since its launch in July 2022 to year-end 2024, the S&P 500® Equal Weight ESG Index achieved a cumulative outperformance of 0.86% compared to its benchmark, the S&P 500 Equal Weight Index. Gaining insight into the factors behind this outperformance highlights important aspects of environmental, social and governance (ESG) attributes that function differently from those in market-cap indices like the S&P 500 ESG Index.

To investigate the ESG attributes contributing to the S&P 500 Equal Weight ESG Index's performance, we created hypothetical ESG quintile compositions by count and reconstituted them annually. This was done by ranking the S&P 500 Equal Weight Index's constituents based on their ESG scores and assigning them to one of the five compositions, from highest to lowest ESG score, akin to previous assessments1 conducted on the S&P 500 ESG Index. The hypothetical equal-weighted performance of these compositions was then calculated and used to create a Brinson-like ESG attribution analysis,2 teasing out the importance of ESG score exposures in the performance of the S&P 500 Equal Weight ESG Index.

Exhibit 1 illustrates the results of this analysis, measuring the contribution of ESG quintile weighting and stock selection effects to the S&P 500 Equal Weight ESG Index's excess return relative to the S&P 500 Equal Weight Index since its launch.3 To emphasize the relative impact of ESG quintile weighting and stock selection effects, the exhibit shows the proportion of the total impact, with their absolute values summing to 100% and the actual return impact shown in the labels.

Our findings reveal that the S&P 500 Equal Weight ESG Index's performance was predominantly driven by stock selection effects rather than ESG quintile weighting effects. Specifically, stock selection contributed 2.65% to the index's excess return, while ESG quintile weighting had a negative impact of 1.79%. This resulted in a total cumulative excess return of 0.86%. Of the five ESG quintiles, the ESG quintile weighting effect exceeded the stock selection effect in just one: Quintile 1.

This conclusion contrasts with the performance drivers observed in the S&P 500 ESG Index during the same period, as illustrated in Exhibit 2. The S&P 500 ESG Index achieved a cumulative excess return of 0.91% against the S&P 500, with more than 60% of this excess return driven by ESG quintile weighting effects. 4

The varied performance drivers highlight the significant impact that index construction methodologies can have on performance. The S&P 500 Equal Weight ESG Index5 can benefit from an approach that emphasizes the selection of companies with higher ESG scores across market capitalizations. This could enable it to tap into the value generated by smaller firms, which can be overlooked in cap-weighted indices.

As the growing emphasis on sustainable investing continues to shape market participants' preferences and the drivers of relative performance in the S&P 500 Equal Weight Index6 continue to attract attention, these findings could serve as a crucial reference for market participants looking into this index's ESG variant. For those interested in exploring more about S&P DJI's sustainability-focused indices, additional information is available in the Sustainability Index Dashboard.

The posts on this blog are opinions, not advice. Please read our Disclaimers.

1 For a thorough description of the hypothetical ESG quintile compositions and the drivers behind the excess return in the S&P 500 ESG Index, see Beyhan, Maya, "Charting New Frontiers," S&P Dow Jones Indices LLC, Sept. 06, 2024.

2 For more information on this widely used performance attribution model, see Brinson, Gary P., L. Randolph Hood and Gilbert L. Beebower, "Determinants of Portfolio Performance," Financial Analysts Journal, July-August, 1986.

3 Analysis carried out using Portfolio Analytics on S&P Capital IQ Pro.

4 Analysis carried out using Portfolio Analytics on S&P Capital IQ Pro.

5 See the S&P Equal Weight ESG Indices Methodology.

6 For a thorough overview of the potential sources and drivers of relative performance in the S&P 500 Equal Weight Index, see Ganti, Anu R., Tim Edwards and Hamish Preston, "Worth the Weight," S&P Dow Jones Indices LLC, July 23, 2024.