
IN THIS LIST

Picking a Path with S&P 500 Sectors

Cerulli Associates Publishes Whitepaper on Redefining the Role of Index Providers

Private Credit vs. Public Debt and Traditional Financing

The S&P 500 GARP Index: Strong Fundamental Performance Amid a Steep Valuation Discount

Strong since Launch: The S&P 500 High Dividend Growth Index

Picking a Path with S&P 500 Sectors

Contributor Image
Joseph Nelesen, Ph.D.

Head of Specialists, Index Investment Strategy

S&P Dow Jones Indices

In February 2025, U.S. equity markets reflected general unease over an unpredictable future. Worries about the probability of tariffs and their impact on growth and inflation weighed on the minds of investors who also had to contend with weaker economic data and questions about the sustainability of mega-cap tech earnings. Against this backdrop, the S&P 500® exhibited striking bouts of intraday volatility yet finished the month in negative territory. In Exhibit 1, we show February performance of The 500™ along with each of its 11 component GICS sectors. February was the fourth month in a row that the sector spread (the difference between highest- and lowest-performing sectors) reached double digits, at 12.0%. Consumer Discretionary, Information Technology and Industrials finished the month trailing The 500, which itself dropped 1.3%. But beyond those three sectors, the other eight outperformed, exhibiting strength among traditionally defensive segments.

Headwinds and tailwinds affecting each sector in January generally persisted in February, as Consumer Discretionary and Information Technology extended their previous month's underperformance, while eight other sectors outperformed The 500 in February, and nine sectors surpassed the broad benchmark YTD (see Exhibit 2). Industrials was the only sector that trailed slightly in February yet maintained excess performance YTD.

In a previous blog, we kicked off sector analysis in 2025 with a review of recent research detailing the performance of two blends of indices, each comprising traditionally cyclical and defensive sectors. Bucketing sectors into defensive and cyclical blends based on their risk characteristics and tendencies to outperform during rising or falling markets can allow for rational tilts based on owning sectors that offer relatively better performance in each environment.

As a reminder, we use the same two approaches below to understand sector performance YTD.1

  • Cyclical Blend: An equal-weighted combination of five cap-weighted cyclical sectors (Information Technology, Financials, Materials, Consumer Discretionary and Industrials), rebalanced monthly.
  • Defensive Blend: An equal-weighted combination of five cap-weighted defensive sectors (Utilities, Energy, Consumer Staples, Health Care and Communication Services), rebalanced monthly.
Exhibit 3 illustrates the hypothetical performance of each approach YTD through February 2025, showing both the widening outperformance margin of defensive sectors along with the resilience of equally weighting cyclical sectors, as both the defensive and cyclical blends outperformed The 500.

Although two months of 2025 are in the rearview mirror and, in many ways, the road ahead remains unclear, the performance of S&P 500 sectors sheds some light on how investors view prospects for different segments of the economy and provides a useful framework for making thoughtful tilts in preparation for whatever comes next.

1 Cyclical and defensive blends are comprised of the top five and bottom five sectors as ranked by historical beta and volatility. Real Estate, ranked in the middle of the 11 S&P 500 sectors, is excluded from this analysis.


Cerulli Associates Publishes Whitepaper on Redefining the Role of Index Providers

The financial services consulting firm, Cerulli Associates, recently published a research study on the use of index-based products within the U.S. retail wealth management market. Their whitepaper aims to shed light on how asset managers, asset allocation model portfolio providers, wealth manager home offices and financial advisors can better utilize index provider solutions.1

The study is the culmination of 293 financial advisor survey results, which are diversified across channel, practice assets under management (AUM), core market client size and advisor age. It excludes advisors with less than USD 50 million in AUM and those with more than 25% in institutional assets or defined contribution plans. The paper also aggregates the findings of 25 executive interviews with asset managers, technology providers, wealth manager home offices and individual financial advisors.

According to the research, the U.S. wealth management industry is experiencing a shift in value proposition where end-investors are increasingly relying on their financial advisor for their financial planning expertise rather than their investment management acumen. When asked to identify which factors are most important when selecting an advisor, 57% of affluent (i.e., USD 100,000 or more in investable assets) clients indicated that an advisor who takes the time to understand their needs and goals is extremely important, while only 45% said the same about the performance of their investments relative to the overall market.2 Fund flow data supports this shift as the positive growth of index-based exchange-traded funds (ETFs) and mutual funds, as well as direct indexing separately managed accounts (SMAs), have outpaced their actively managed counterparts, a trend that is projected to continue through 2028 (see Exhibit 1).

Although Cerulli Associates forecasts increased usage of index-based strategies, Exhibit 2 indicates that advisors currently pursue an active approach in sub-asset classes they perceive as being less informationally efficient, such as small-cap equities, international fixed income, U.S. taxable and municipal fixed income, options-based assets and real assets. However, a future shift could be in the cards. Cerulli Associates' research suggests that financial advisors could expand their usage of index-based products beyond equities to fixed income as well,3 paralleling the growth of indexing in fixed income.4

In addition to surveying advisors on how they utilize index-based products, they also extracted insights on how they evaluate them. For example, Exhibit 3 shows that 82% of advisors indicated that the quality of the index design and methodology was a top-three factor when considering the index that underlies an ETF, and 60% of advisors said the same of index provider content and education. To learn more about how financial advisors think about index providers, Cerulli Associates created a series of advisor profiles located in the appendix of the whitepaper.

As the landscape of index-based products becomes increasingly crowded, the recent findings from Cerulli Associates highlight that asset and wealth managers should thoughtfully consider how to leverage index providers' solutions to stand out from the crowd.5 Strategies include going beyond traditional index data to drive product development and leveraging brand and content for product marketing and distribution. Embracing these strategies can not only differentiate firms but may also position them for success in the evolving retail wealth management market.


1 The Cerulli Associates whitepaper "Redefining the Role of Index Providers" was sponsored by S&P Dow Jones Indices.

2 Please see page 4 of Cerulli Associates' "Redefining the Role of Index Providers".

3 Please see page 10 and 11 of Cerulli Associates' "Redefining the Role of Index Providers" for more information on ETF product growth.

4 For more information on the growth of indexing in fixed income, please read "The Hare and The Tortoise - Assessing Passive's Potential in Bonds".

5 Please see section 4, pages 12-17 of Cerulli Associates' "Redefining the Role of Index Providers" for more information.


Private Credit vs. Public Debt and Traditional Financing

Contributor Image
Nicholas Godec

Senior Director, Head of Fixed Income Tradables & Commodities

S&P Dow Jones Indices

The private credit market has grown significantly, becoming a key component of the global financial landscape. Traditional banks have tightened lending practices due to increased regulatory scrutiny and risk aversion following the 2008 Global Financial Crisis. In response, private credit has emerged as an alternative for businesses facing challenges in securing financing from traditional sources.

This blog explores the factors driving private credit's rise and how it compares to public debt and traditional financing.

A Multi-Layered and Growing Market

Several factors have fueled private credit's expansion, including institutional investors' pursuit of yield, increased market sophistication and greater awareness of the segment's unique characteristics.

Private credit includes diverse debt strategies, such as senior debt, subordinated capital and credit opportunities. Senior debt funds offer secured loans for acquisitions and restructurings, benefiting from priority claims on assets. Subordinated capital (mezzanine funds) sits between equity and secured debt, often financing buyouts while generating interest payments. Credit opportunity funds invest in various credit instruments across global markets, including distressed debt and structured finance, providing potential for diversification.

Private Credit vs. Public Debt: Liquidity and Accessibility

Private credit and public debt differ in liquidity and market accessibility. Private credit refers to debt investments that are not publicly traded and typically issued by non-bank lenders. These instruments are often illiquid, with lock-up periods restricting sales. However, this illiquidity may result in higher yields compared to public debt.

Public debt, including corporate bonds and government securities, trades in the public bond market, offering greater liquidity with expanded access for prospective buyers or sellers. This accessibility allows individual and institutional investors to easily participate. However, increased competition often results in lower yields.

For investors, the liquidity tradeoff is crucial. Private credit's illiquidity requires a longer investment horizon, whereas public debt's liquidity provides flexibility but potentially lower yields than can be found in private debt markets.

Transparency and Reporting Standards in Private vs. Public

A key distinction between private credit and public debt is transparency. Public debt is subject to strict regulatory requirements, including standardized disclosures and regular reporting. This enables investors to make informed decisions based on widely available financial data.

Private credit, however, lacks uniform reporting standards. Borrowers are not always required to disclose financial information publicly, and reporting practices vary across issuers. This opacity makes due diligence and fund manager expertise critical in assessing credit risk.

To mitigate transparency challenges, private credit lenders rely on strong borrower relationships, detailed covenants and negotiated reporting requirements. Even so, investors must be comfortable with less readily available information, making trust in their fund managers essential.

Private Credit: Filling the Gaps Left by Banks

The lending landscape has evolved since the 2008 financial crisis. Traditional banks—once primary credit providers—face stricter regulations, limiting their ability to lend, particularly to middle-market businesses and specialized sectors. Higher capital requirements and risk management constraints have reduced their exposure to certain loan types.

Private credit lenders have stepped in, offering capital alternatives to businesses that may not meet traditional lending criteria. These non-bank lenders provide financing solutions with greater flexibility, including tailored repayment schedules, customized covenants, and the ability to underwrite complex transactions.

By serving businesses overlooked by traditional banks, private credit supports economic growth, particularly among small- and medium-sized enterprises (SMEs), which are widely viewed as key contributors to innovation and employment.

Synergies Between Private Credit and Traditional Lending

While private credit and bank lending are often seen as competitors, they also complement each other. Banks may originate loans and syndicate portions to private credit funds, managing risk while continuing to serve clients.

Additionally, banks and private credit firms may co-lend on larger transactions, combining resources and expertise. Such partnerships allow banks to remain engaged in lending while meeting regulatory requirements, while private credit firms gain access to larger, more complex deals.

Learn more in our recent analysis, "The Rapid Rise of Private Credit."

Don't miss our next blog where we explore the opportunities and risks associated with private credit.

This blog was co-authored by Ricky LaBelle and Greg Vadala.


The S&P 500 GARP Index: Strong Fundamental Performance Amid a Steep Valuation Discount

Contributor Image
George Valantasis

Director, Factors and Dividends

S&P Dow Jones Indices

GARP (growth at a reasonable price) has long been a staple investment strategy, but it was popularized by investing legend Peter Lynch after the Magellan Fund posted a remarkable average annual return of 29.2% from 1977 to 1990.1 As the name implies, it's a strategy that seeks to strike a balance of tracking stocks with both growth and value characteristics. While the S&P 500® GARP Index has historically outperformed over the long term, its recent underperformance relative to the S&P 500 in 2024 has led to a situation where it is no longer trading at a "reasonable" price, but rather at a "historically cheap" price relative to The 500™. Interestingly, this blog will reveal that the current valuation disconnect occurs during a period of particularly strong fundamental performance factors for the S&P 500 GARP Index.

Valuation Comparison

Exhibit 1 illustrates the historical trailing 12-month price-to-earnings (P/E) ratio discount of the S&P 500 GARP Index relative to The 500 since June 1995. As of Jan. 31, 2025, the current discount is 51.0%, attributed to The 500's P/E ratio of 28.3 compared to the S&P 500 GARP Index's P/E ratio of 13.9.

As Exhibit 1 shows, the discount has historically tended to mean revert when reaching extended levels, with another notable divergence occurring in June 2000 when the discount peaked at 59% near the Tech Bubble. In the one-, three- and five-year periods following June 2000, the S&P 500 GARP Index outperformed The 500 by 25%, 45% and 78%, respectively.

Growth Comparison

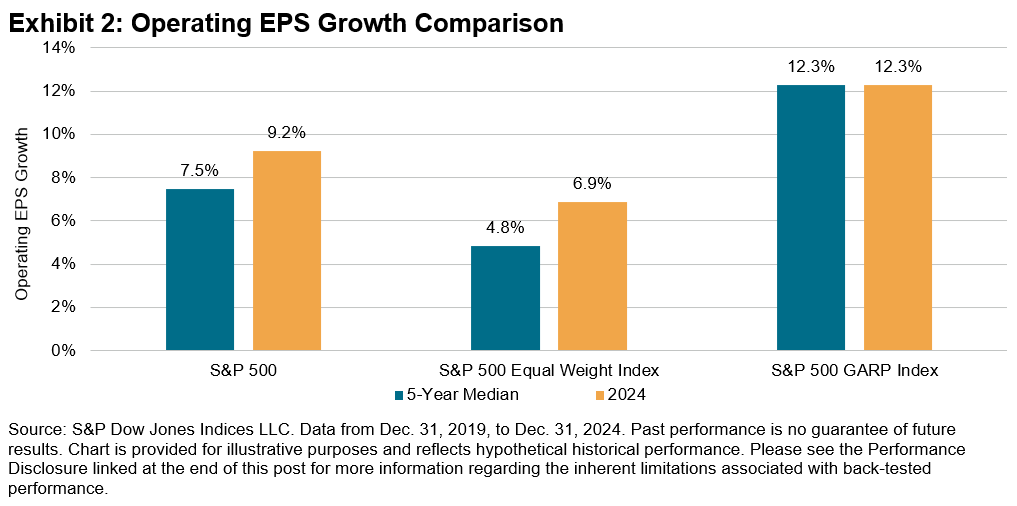
Exhibit 2 shows that the S&P 500 GARP Index's 2024 operating earnings per share (EPS) growth rate is in line with its five-year median of 12.3%. Both figures indicate a significant premium compared to the operating EPS growth rates of The 500 and the S&P 500 Equal Weight Index in 2024. The five-year median is presented instead of the average due to the volatility of operating EPS, particularly during the 2020-2022 COVID-19 period, which can distort the average calculation.

Quality Comparison

The same trend observed in the operating EPS growth comparison is evident in the quality comparison as well. As shown in Exhibit 3, the S&P 500 GARP Index's 2024 return on assets (ROA) of 4.9% is 24% higher than its five-year average of 3.9%. In comparison to The 500 and the S&P 500 Equal Weight Index, this 4.9% ROA reflects a 31% and 100% increase, respectively.

The S&P 500 GARP Index's 2024 return on equity (ROE) of 17.0% is 10% above its five-year average and is closely aligned with The 500's 2024 ROE of 17.3% (see Exhibit 4). Compared to the S&P 500 Equal Weight Index's ROE of 11.0%, the S&P 500 GARP Index's ROE reflects a 54% premium.

Conclusion

Despite its notable valuation discount, the S&P 500 GARP Index's 2024 fundamental performance—assessed through growth and quality metrics—was strong compared to both its benchmarks and its historical performance. The S&P 500 GARP Index demonstrated strong fundamental performance in 2024 while simultaneously trading at one of its widest valuation discounts since the Tech Bubble peak in 2000.


  1. "Betting on the Market Pros: Peter Lynch." PBS.


Strong since Launch: The S&P 500 High Dividend Growth Index

Contributor Image
Hugo Barrera

Senior Analyst, Factors and Dividends Product Management

S&P Dow Jones Indices

While the market offers many dividend strategies, few incorporate dividend forecasts to provide a forward-looking assessment. The S&P 500® High Dividend Growth Index utilizes the industry-leading S&P Global Dividend Forecasting dataset to select constituents from the S&P 500 that are projected to have the highest dividend yield growth. This innovative index applies a unique methodology, tracking companies based on a dividend growth score calculated by subtracting 12-month trailing yield from the 12-month forecasted yield.

Launched on Oct. 23, 2023, the S&P 500 High Dividend Growth Index has made a strong start, outperforming other well-known dividend indices. Furthermore, it has historically shown higher dividend yields and dividend growth rates than The 500™.

In this blog, we will examine the historical characteristics of this index, including its risk/return profile, dividend yield and dividend growth rate. We will also assess its dividend contributions over time and review its sector allocations throughout the years.

Performance since Launch

The S&P 500 High Dividend Growth Index has outperformed other leading dividend strategies both YTD and since its launch, posting returns of 5.75% and 30.51% over those periods, respectively. Exhibit 1 shows that in 2024, the index posted strong performance with a 16.26% return, outperforming most dividend strategies.

Similarly, the S&P 500 High Dividend Growth Index has exhibited solid performance in line with its benchmark, which is not an easy feat given the recent strong performance of mega-cap stocks.

Long-Term, Back-Tested Performance

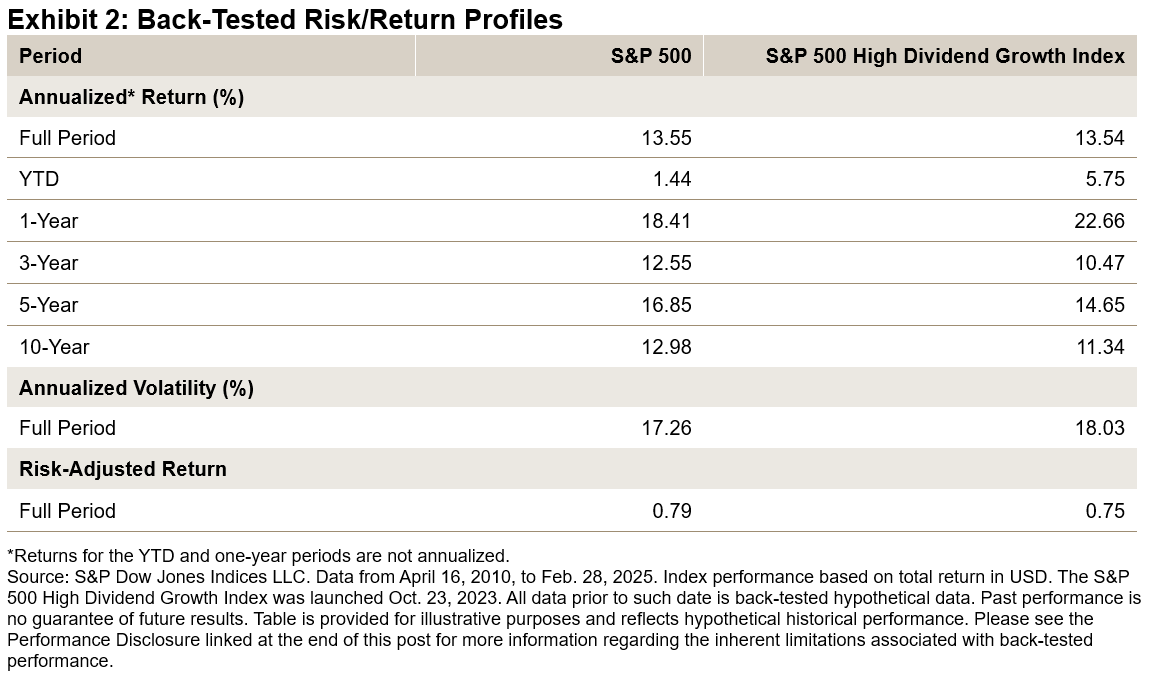
Since 2010, which includes back-tested performance, the S&P 500 High Dividend Growth Index has posted a robust annualized return of 13.54% and a risk-adjusted return of 0.75. The S&P 500 High Dividend Growth Index's performance has closely aligned with The 500, a notable achievement given the dominance of growth-oriented stocks over the past decade (see Exhibit 2).

Dividend Yield

As shown in Exhibit 3, the dividend yield of the S&P 500 High Dividend Growth Index consistently outpaced the dividend yield of The 500 from 2011 to 2025. On average, the S&P 500 High Dividend Growth Index's dividend yield was 3.09%, outperforming The 500's dividend yield (of 1.82%) by 1.27%.

Dividend Growth Rate

From 2011 to 2025, the S&P 500 High Dividend Growth Index and The 500 grew their dividends at annual rates of 10.6% and 8.8%, respectively. More recently, from 2023 to 2025, the S&P 500 High Dividend Growth Index's dividend growth rate was 8.7%, surpassing The 500's 6.5% rate (see Exhibit 4).

Dividend Contributions

As displayed in Exhibit 5, dividends contributed a greater percentage to the total return of the S&P 500 High Dividend Growth Index than to the total returns of the market-cap and equal-weight benchmarks, as well as style indices like value and growth. Notably, the dividend contributions of the S&P 500 High Dividend Growth Index were 9.8 percentage points higher than those of The 500.

Sector Weights

Exhibit 6 shows how the sector weights of the S&P 500 High Dividend Growth Index have changed over time. On average, the largest sector weights in the index have been Financials, Industrials, Utilities and Information Technology. For a dividend strategy, the weights across the sectors have been overall balanced.

Conclusion

The S&P 500 High Dividend Growth Index combines forward-looking and historical metrics for constituent selection. Its innovative design has historically delivered higher dividend yields and growth rates than its benchmark, all while maintaining strong total returns. Although this index has only been live for just over 12 months, it is noteworthy that it has outperformed similar high dividend yield and dividend growth indices by posting strong returns over this period.