
IN THIS LIST

Introducing the S&P 500 Top 20 Select Indices

Profitability Matters in Canadian Small Caps

Sector Neutrality - An Essential Mechanism within the S&P 500 ESG Leaders Index

The Taxing Effect of Taxes

S&P/ASX 200 High Dividend Index: Q3 2024 Performance Attribution

Introducing the S&P 500 Top 20 Select Indices

Contributor Image
Fei Wang

Associate Director, Private Market Indices

S&P Dow Jones Indices

The S&P 500® is widely regarded as the best single gauge of U.S. large-cap equities. Among the 500 companies in the index, the largest names have drawn the most attention due to their outperformance in recent years. To address the increasing interest in mega-cap stocks in the S&P 500, S&P DJI recently launched the S&P 500 Top 20 Select Index Series, adding them to our existing offerings of the largest companies in the S&P 500.

The S&P 500 Top 20 Select Index series currently comprises three headline indices: the S&P 500 Top 20 Select Index, the S&P 500 Top 20 Select 35/20 Capped Index and the S&P 500 Top 20 Select Uncapped Index.

These indices measure the performance of the largest 20 companies in the S&P 500 with different capping mechanisms, which are designed with various diversification requirements in mind. They undergo quarterly reconstitution and rebalancing to reflect the latest market dynamics.1

Why Top 20 Select?

The S&P 500 serves as the benchmark for the large-cap market segment, while the S&P 500 Top 20 Select Index series focuses on the top 4% of the companies by count. The S&P 500 Top 20 Select Index series has outperformed the S&P 500 in the past five years, except for 2022, as well as over longer time horizons (see Exhibit 2).

Generally, a larger market capitalization indicates a company's leadership within its respective sectors and industries, superior performance relative to its peers, and lower volatility during market turbulence. As of Oct. 31, 2024, the largest 20 companies' aggregate weight in the S&P 500 was 46%, and they contributed more than 60% of the index's return YTD.2

Exhibit 3 shows that the S&P 500 Top 20 Select Index's weighted average market capitalization has consistently doubled that of the S&P 500 over the past two decades. The divergence between weighted average and simple average market cap of the S&P 500 Top 20 Select Index further highlights the increasing concentration of market value in the largest companies in recent years.

A selection of 20 companies allows sufficient coverage of the best-performing sectors while reducing potential turnovers. For example, Information Technology has been the best-performing sector in recent years, led by Apple, Microsoft and Nvidia. Due to this dynamic, the sector accounted for nearly half of the S&P 500 Top 20 Select Index weight, compared to less than one-third in the S&P 500. The other leading sectors are more comparable with their representations in the S&P 500. In contrast, Materials, Industrials, Utilities and Real Estate are entirely absent, suggesting that these sectors are not favored under the current market conditions (see Exhibit 4).

In our next blog, we'll explore the S&P 500 Top 20 Select Index's historical and relative performance.

1 For more information on index construction, please see the S&P U.S. Indices Methodology. For more information on the capping thresholds, please refer to the Regulatory Capping Requirements section of S&P Dow Jones Indices' Equity Indices Policies & Practices Methodology.

2 Contribution calculation is based on S&P 500 (Total Return). Year-to-date (YTD) data from Dec. 31, 2023, to Oct. 30, 2024. YTD data is not annualized.


Profitability Matters in Canadian Small Caps

Contributor Image
Anna Mittra

Associate Director, Global Exchanges

S&P Dow Jones Indices

As the S&P/TSX SmallCap Select Index celebrates its fifth anniversary, it's an opportune time to reflect on the index's performance, construction and composition compared to the benchmark S&P/TSX SmallCap Index. With a five-year live track record, the select index has demonstrated its ability to measure the Canadian small-cap segment with higher total returns and lower volatility.

Understanding the S&P/TSX SmallCap Select Index

The S&P/TSX SmallCap Select Index employs the same methodological framework as our existing S&P Global SmallCap Select Index Series, but it utilizes the S&P/TSX SmallCap Index as its selection universe. To qualify for inclusion, companies must achieve two consecutive years of positive earnings per share. As a safeguard, companies that report two consecutive years of negative earnings are removed from the index. To enhance replicability, we also exclude the smallest 20% and the least liquid 20% of companies. The index is weighted by float market capitalization and is rebalanced semiannually in June and December.

As of Oct. 31, 2024, the S&P/TSX SmallCap Select Index included 135 of 243 S&P/TSX SmallCap Index constituents, representing 66% coverage by index weight. As illustrated in Exhibit 2, the S&P/TSX SmallCap Select Index showed a higher average median daily value traded (MDVT), representing enhanced liquidity. By focusing on a smaller subset, the select index eliminates less actively traded stocks. This targeted approach emphasizes securities with higher turnover and size, potentially translating to increased capacity and replicability compared to the benchmark index.

Long-Term Track Record of Outperformance

Over the past twenty years, the S&P/TSX SmallCap Select Index outperformed the benchmark S&P/TSX SmallCap Index by approximately 2% per year with lower volatility. The S&P/TSX SmallCap Select Index rebounded more quickly during periods of extreme volatility compared to its benchmark, possibly thanks to its emphasis on liquidity and financial stability. This trend is particularly evident during times of market stress, such as the COVID-19 pandemic and its aftermath, when smaller, less liquid companies typically faced larger losses than their more stable peers.

The S&P/TSX SmallCap Select Index has outperformed the benchmark during several periods, as shown in Exhibit 4. The index also experienced lower volatility, as reflected by its lower standard deviation, indicating more consistent returns and reduced exposure to the sharper price fluctuations that were seen in the broader S&P/TSX SmallCap Index.

The S&P/TSX SmallCap Select Index has shown strong performance relative to the benchmark, with a hit rate of 69.2% during down months, suggesting its resilience in volatile markets. The lower down-market capture ratio indicates that the index was less affected by the market's downside, providing additional stability during the market decline.

In conclusion, the S&P/TSX SmallCap Select Index demonstrates that a more targeted approach that excludes companies deemed less profitable along with the smallest and least liquid securities has historically improved long-term total returns, reduced risk and enhanced liquidity compared to the broader Canadian small-cap segment.


Sector Neutrality - An Essential Mechanism within the S&P 500 ESG Leaders Index

Contributor Image
Stephanie Rowton

Senior Director, Tokenization and U.S. Equities

S&P Dow Jones Indices

The S&P 500® ESG Leaders Index seeks to provide a measurement of U.S. equities while incorporating ESG (Environment, Social, and Governance) factors.1 The index maintains similar industry weights to the S&P 500 while implementing stricter ESG eligibility criteria.

A common misconception is that all ESG indices remove or underweight sectors deemed environmentally damaging, such as Energy or Utilities. However, removing entire sectors may result in a shift in weight toward other sectors, potentially creating sector bias and concentration risk. Rather than excluding sectors, the S&P 500 ESG Leaders Index selects companies that perform highest when considering specific ESG metrics.

Exhibit 1 illustrates how the S&P 500 ESG Leaders Index maintains low active share in relation to the benchmark index, in each sector, with the sector active share at 6.41%, highlighting broad sector neutrality. However, using ESG metrics as the criteria to determine index inclusion will naturally result in deviations from the underlying index. This is particularly evident when a sector has several constituents deemed ineligible or a company with a high float market cap (FMC) is excluded. Typically, the more a methodology integrates stricter sustainability criteria, the greater the active share.

The S&P 500 ESG Leaders Index methodology selects constituents on a relative basis1 within each GICS® industry group, resulting in low active share within sectors. However, in certain instances, sectors may be over- or underweighted relative to the underlying index, causing deviation. This is illustrated by the active share at the index level reaching 41.15%, which is driven by both disparity in index constituents with the S&P 500, as mentioned previously, as well as weights (see Exhibit 1).

The index selection process targets 50% of uncapped FMC from each GICS industry group in the S&P 500, selecting companies in decreasing order using S&P Global ESG Scores (see Exhibit 2). However, specific exclusions (such as exclusions based on specified business activities) may prevent an industry group from meeting the 50% target. This could be a result of the industry lacking enough eligible constituents or the FMC weight of eligible constituent weights not reaching the target.

If this happens, excess industry weight is distributed proportionately among the remaining index constituents. If eligible constituents with higher FMC weighting are selected, any additional weight allocation may result in a sector overweight (see Exhibit 3). To prevent single-stock concentration, a constituent cap1 is integrated as per the S&P 500 ESG Leaders Indices methodology.

The S&P 500 ESG Leaders Index has provided a measurement of U.S. equities with an ESG lens and maintained similar industry group weights as the S&P 500. By utilizing index construction to maintain broad sector neutrality, the index historically reduced the impact of sector-driven performance, increased the impact of stock selection and produced low tracking error versus the S&P 500.3 Consequently, the success of the index is not solely measured through its performance but also by how closely its industry group weights—and, by extension, sector weights— remain similar to the S&P 500.

1 See Rowton, Stephanie and Maria Sanchez, "The S&P 500 ESG Index: 5 Years of Defining Core Through an ESG Lens," S&P Dow Jones Indices LLC, Aug. 7, 2024.

2 A maximum single-company weight cap (5%, company weight in the S&P 500 ESG Index) is applied to the final index constituents.

3 Beyhan, Maya, "Understanding the Outperformance of the S&P 500 ESG Leaders Index through a Sectoral Lens," S&P Dow Jones Indices' Indexology® Blog, Oct. 24, 2024.


The Taxing Effect of Taxes

"Be thankful I don't take it all, cause I'm the taxman." George Harrison (The Beatles) in "Taxman"

For over 20 years, S&P Dow Jones Indices has compared index performance against actively managed funds and published the results in the SPIVA® Scorecards. Active funds have often struggled to match the returns of capitalization-weighted benchmarks like the S&P 500® or the S&P Composite 1500® (see the SPIVA Global Mid-Year 2024). But even outperforming active managers have faced headwinds, including typically higher fees and particularly taxes, which can significantly erode performance, leaving even fewer managers capable of outperforming in the long run.

The SPIVA After-Tax Year-End 2023 Scorecard analyzes the cumulative effect of taxes on investor returns for broad U.S. domestic equity categories, demonstrating the improbability of beating a benchmark after accounting for taxes on capital gains and other distributions. In 2023, across the All Domestic Funds, All Large-Cap Funds and Large-Cap Core Funds categories, 79%, 66% and 74% of active managers underperformed their benchmarks after taxes, respectively. Fund manager underperformance rates worsened considerably compared to 2022, particularly for All Domestic Funds (see Exhibit 1).

A key reason for the higher underperformance rates in 2023 is that the impact of taxes on the returns of active funds was generally greater compared to the equivalent tax impact on the respective benchmarks. The 2023 median after-tax returns for All Domestic Funds, All Large-Cap Funds and Large-Cap Core Funds lagged their pre-tax medians by 1.2%, 2.8% and 2.1%, respectively, compared to 1.5%, 1.1% and 1.0%, respectively, in 2022. These differentials were considerably larger compared to the less than 0.5% impact for both the benchmark S&P 1500® and S&P 500.

If the impacts of taxation on actively managed funds weren't damaging enough, the sharp increase in long-term mutual fund outflows over the past couple years may have led to another unfortunate scenario for taxable investors. During 2022 and 2023, long-term U.S. mutual funds experienced a combined USD 1.765 trillion in net outflows.1 These persistent outflows may have triggered tax bills for investors even in strong-performing markets.

While 2023 was a much different market regime than 2022 (characterized by a sharp rise of 26.3% and a severe downturn of 18.1%, respectively, for the S&P 500), one thing was the same in both years: active managers in broad U.S. equity categories found it difficult to beat their benchmarks, particularly when tax bills came due. To learn more about the effect of taxes on fund performance, please see the SPIVA After-Tax Year-End 2023 Scorecard.

The author would like to thank Joe Nelesen, Davide Di Gioia and Grace Stoddart for their contributions to this post.

1   For more detail on long-term U.S. mutual fund flows, please see figures 3.3 and 3.4 (pages 46-48) in the 2024 Investment Company Fact Book.


S&P/ASX 200 High Dividend Index: Q3 2024 Performance Attribution

Contributor Image
Izzy Wang

Associate Director, Factors and Dividends

S&P Dow Jones Indices

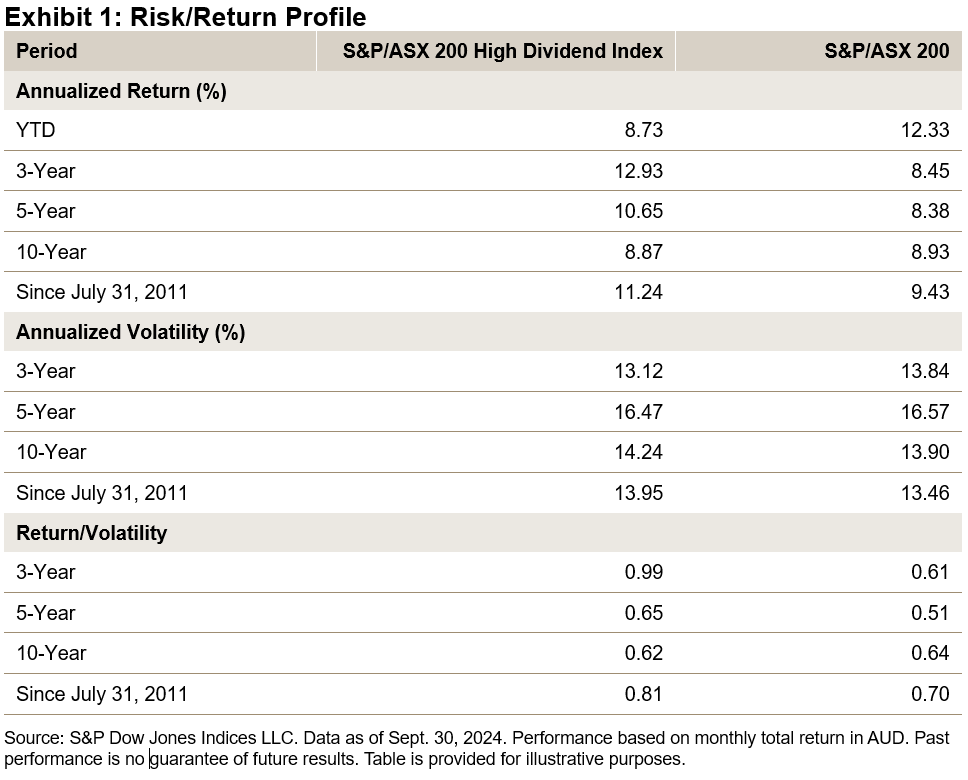
The S&P/ASX 200 High Dividend Index seeks to measure the performance of the 50 companies with the highest 12-month forecast dividend yield from the S&P/ASX 200. Historically, the index has consistently delivered higher-than-market dividend yield and long-term outperformance against its benchmark. From July 2011 to September 2024, the index had an average trailing 12-month gross dividend yield of 5.5% and an annual excess return of 1.8% compared with the S&P/ASX 200.

Exhibit 1 shows the historical performance of the S&P/ASX 200 High Dividend Index. Year-to-date, the index experienced short-term underperformance against the market, lagging the S&P/ASX 200 by 3.6% as of Sept. 30, 2024. To better understand the source of the excess return, we are taking a closer look at the index's short-term and long-term performance.

As Exhibit 2 shows, the YTD underperformance against the S&P/ASX 200 could be largely attributed to an overweight in the Energy and Materials sectors and an underweight in the Information Technology and Real Estate sectors. Increased weight in some high-yielding mega-caps such as Woodside Energy Group and Fortescue Ltd was the primary reason for the overweight in Energy and Materials. Lacking weight in Information Technology and Real Estate aligns with a high-dividend-yield strategy based on the S&P/ASX 200 Ex-A-REITs universe.

While overweighting Energy and Materials in the S&P/ASX 200 High Dividend Index has not delivered excess return YTD, it has been a major contributor to the long-term outperformance since 2021. From Dec. 31, 2020, to Sept. 30, 2024, the S&P/ASX 200 High Dividend Index had a total return of 68.2%1 in contrast to 46.5% from the S&P/ASX 200. We can mainly attribute the outperformance to allocation effect rather than selection effect (see Exhibit 3). Financials, Materials, Health Care, Energy and Consumer Staples were the largest contributors. Over the longer term, the S&P/ASX 200 Index underweighted Health Care and Consumer Staples, while overweighting Financials, Materials and Energy.

To sustain a higher-than-market dividend yield level, the index selects eligible stocks from the S&P/ASX 200 based on forecast dividend yield. Some familiar names may be excluded due to low yield ranking. As of the July 2024 rebalancing, Wesfarmers, Commonwealth Bank Australia and Macquarie Group had a forecast dividend yield of approximately 3.5%, which is relatively low compared with the weighted average dividend yield of 5.5% for the S&P/ASX 200 High Dividend Index.

As Exhibit 4 shows, the S&P/ASX 200 High Dividend Index has been able to maintain a dividend yield that is about 1.5% higher than the market level for the past 10 years. As of Sept. 30, 2024, the trailing 12-month dividend yield of the S&P/ASX 200 High Dividend Index is 5.14%, while that of the S&P/ASX 200 is 3.47%.

Like all factor indices, the S&P/ASX 200 High Dividend Index has experienced performance reversions during the short term. More importantly, the index consistently targets companies with high dividend yield and has historically delivered some excess return in the long term.

1 FactSet generated index return (see Exhibit 3) is 0.8% less than the official cumulative index total return of the S&P/ASX 200 High Dividend Index.